

Improving your relationship with money Investing & Personal Finance 176K+ on Instagram | Join our FREE Newsletter 👇🏼
Mumbai, India
Joined July 2020
- Tweets2.6K
- Following189
- Followers982
- Likes2.1K




Indians aren't selling their gold. They're borrowing against it.
Gold loans against jewellery jumped ~105% in a year to ₹5.1 lakh crore by May 2026.
Rising gold prices are making jewellery a bigger source of credit.
But default on repayment, and you risk losing the gold.
Not every rupee in your portfolio needs equity risk.
FDs, liquid funds, PPF, EPF, NPS and government securities serve different purposes.
Match your fixed income investments to your goals, timeline and liquidity needs.
Give every rupee a purpose.
"Zoom out. Don't panic. Stay invested."
But what if you need that money soon?
Review your emergency fund, asset allocation and upcoming goals.
Money needed in 2 years shouldn't take the same risks as money invested for 15.
Zoom out on markets. Don't zone out on your finances.
Worried about a recession?
A falling stock market doesn't automatically mean one is coming.
Build an emergency fund, maintain independent health insurance, clear expensive debt and be careful with new EMIs.
You can't predict uncertainty. You can prepare for it.
Markets falling? Don't panic.
Build an emergency runway, keep near-term expenses out of equity and know what you can cut if the downturn continues.
You don't need to predict the recovery.
You need a plan.
Review, don't react.

Children’s funds have grown 160% in 5 years, with over ₹25,000 crore invested.
But the lock-in means less flexibility.
A separate SIP may offer more control. The right choice depends on your goal, timeline and risk tolerance.
Equity isn't the villain. Concentration is.
In 2025, gold returned ~72%, silver 120%+, while the Nifty 500 returned 7%.
Don't chase last year's winners. Build a portfolio around your goals, not recent returns.
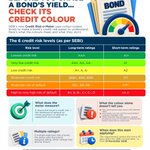
A high bond yield looks attractive, but what's the risk?
SEBI’s new Credit Risk-o-Meter uses 6 colour-coded levels to show credit risk.
From 21 November 2026, the new disclosure requirement kicks in.
Check the risk, not just the yield.

A weaker rupee can make imports, foreign travel and overseas education cost more.
But it can also boost rupee returns on international investments.
For foreign investors in India, the reverse can happen.
Currency movements affect your money beyond forex.
Equal inheritance doesn't always mean equal outcomes.
Assets can differ in liquidity, value and usefulness to each child.
Inheritance planning isn't just about dividing wealth. It's about leaving your children options.
RBI raised the repo rate from 5.25% to 5.50%.
Borrowers: floating-rate loans may get costlier.
Savers: deposit rates may rise too.
But the bigger question is transmission.
Watch inflation, growth, loan rates and deposit rates next.

Your SIP may not be the problem. Your index might be.
13 stocks making up ~33.7% of the Nifty returned just 0.8% annually from Sep 2021–Aug 2026.
The Nifty returned ~7.1%. Excluding them, ~11%.
An index fund is also a bet on its biggest constituents.
India’s economy can grow while the stock market falls.
GDP looks backward. Markets price the future.
Crude, a weaker rupee, FII outflows and valuations can matter more in the short term.
The economy and stock market are connected. But they aren't the same thing.
Is India too expensive, or are we comparing it wrong?
Nifty trades at ~19.6x P/E, below its 10-year median of ~23.3x.
Yet MSCI India still trades at a premium to emerging markets.
The question isn't whether India is expensive.
It's whether earnings justify the premium.
No kids doesn’t automatically mean a smaller retirement corpus.
You may save on education and wedding costs, but you also need to plan for healthcare, caregiving and assisted living.
Think beyond one number: essentials, lifestyle and future care.
Indian real estate is booming. But not every part of it is.
Q1 2026 home sales rose 8%, but homes above ₹1 crore grew 30%, while sub-₹1 crore homes fell 24%.
Real estate isn't one market. Segment and location matter.
The market is down. Your plan doesn’t have to be.
Nifty is down ~10% this year. Corrections are part of investing.
Emergency fund. Right time horizon. Discipline.
Sometimes, prices change. Your plan doesn’t have to.
Ganpati Bappa moves more than emotions. He moves an entire economy. 🙏
Mumbai’s Ganeshotsav drives business across artisans, vendors, decorators and local shops.
With 2,500+ public mandals and ₹45,000–50,000 crore in estimated activity, Bappa is an economic force.
Forgotten mutual fund investments could still have money in them.
SEBI data shows ₹3,811 crore of unclaimed mutual fund money.
MF Central’s MITRA can help trace folios inactive for 10+ years.
Check yours. And your parents’ too.