

Trader || Alpha Threads 🧵 || DeFi Maxi ||
Joined November 2021
- Tweets56.5K
- Following15.4K
- Followers109K
- Likes105K



Pinned Tweet
GM CT
I am in this space for like 6 years and there are some secrets that I wish I could send back in time to myself.
1-Secure profits in BTC, ETH, stablecoins, and fiat. Don't gamble them away.
2-Cult projects can profit but exit before the crash.
3-Avoid locking tokens for excessive yield; it's risky.
4-Guard your attention; avoid Crypto drama distractions.
5-Beware of over-optimizing yields; more yield often means more risk.
6-Be skeptical of advice; many have agendas.
7-Favor market leaders in new narratives.
8-Simplicity beats using countless tools.
9-Information flow hierarchy matters; Twitter shills come last.
10-Alpha comes from knowledge or hard work.
11-History repeats; recognize patterns.
12-Position early; FOMO means you might be late.
13-Focus on portfolio %, not $ value.
14-Cut losers early; don't let them grow.
15-Keep a crypto journal; learn from mistakes.
16-Fundamentals matter less in a bull market.
17-Incentives drive prices; watch airdrops and rewards.
18-No one's too big to fail; protect your funds.
19-It's about risk management, not perfection.
20-Narrow your focus; stay informed in chosen sectors.
21-Don't dwell on macro; focus on capital flow.
22-Trade sober, rested, and focused.
23-Stablecoins aren't always stable; use fiat if needed.
24-Concentrate to grow; diversify to protect.
25-Develop trading systems; emotions kill gains.
26-100x returns through trading are rare.
27-New projects attract more attention.
28-Be cautious of advice on Crypto Twitter.
29-Expand beyond Crypto content for knowledge.
These principles may change, but my belief in #DeFi's potential remains unwavering.
Share and save for future reference during the next bull run.
30+ Early-Stage Crypto Projects Worth Watching
While most attention goes to established projects, smaller teams are building across AI, DeFi, trading, RWAs, and NFTs.
Here’s my research watchlist.
1. AI & Agent Infrastructure
➜ @TryNoahAI — Build dApps and AI agents from prompts.
➜ @instinct_xyz — AI trading infrastructure backed by YC.
➜ @AntSeed — P2P AI marketplace. Raised $2.4M.
➜ @Tensorcash — AI inference verification and settlement.
➜ @CommonFoundry — GPU-powered PoW and AI infrastructure.
➜ @indexnetwork_ — Social network for personal AI agents.
2. AI-Powered Trading
➜ @weftfinance — Automates trading strategies.
➜ @XStableAI — AI-powered gold, silver, and FX trading.
➜ @listendotmoney — Agentic DeFi trading.
➜ @Ulys_AI — Turns ideas into AI-powered trades.
➜ @silhouette_ex — Block trading on Hyperliquid.
3. DeFi, RWAs & Infrastructure
➜ @multiliquid_xyz — Instant RWA liquidity. Raised $8M.
➜ @alloco_fi — Tokenized investment strategies.
➜ @paxoslabs — Onchain asset distribution.
➜ @flexmeow — Fixed-rate lending markets.
➜ @fhenix — Confidential smart contracts.
➜ @Bramble_fi — Privacy-focused Starknet wallet.
4. Launchpads & Gaming
➜ @AscendLaunch — Elysium ecosystem launchpad.
➜ @Torchpaddotfun — Robinhood Chain token launchpad.
➜ @districtxyz — Solana and Base launchpad.
➜ @Evolutdotfun — Memecoin launchpad.
➜ @eloscapeHQ — Virtual mining on Elysium.
➜ @traded_gg — Global collectibles marketplace.
5. More Projects to Research
➜ @ChopLogsApp — Volatility farming.
➜ @IntelTrade — Hyperliquid market intelligence.
➜ @ImperialPerps — Unified Solana perps terminal.
➜ @signo_fi — AI-powered DeFi automation.
➜ @suno_finance — Onchain solar investments.
6. NFT Watchlist
➜ @nuloraio — Monero-based NFTs.
➜ @0xCyberThrone — 8,888 robot NFTs.
➜ @Villagers_RH — 9,999 NFTs on Robinhood.
➜ @OranguNation — Animated NFT universe.
➜ @GigaLegendsLTD — Ethereum NFTs from Gigaverse.
Not every project will succeed, but early research can reveal opportunities before they attract wider attention.
Which ones are on your radar?

Everyone wants tokenized stocks onchain.
Far fewer people talk about who’s going to provide the liquidity.
That’s the part of @Oly_Dao I find worth watching.
OLY already trades against tokenized NVDA, TSLA, BTC and ETH on Robinhood Chain, while its broader model draws on staking revenue, Uniswap fees and trading activity.
The opportunity isn’t necessarily in launching another tokenized asset. It’s in providing the liquidity those assets need to trade.
Of course, having pools doesn’t automatically mean meaningful revenue. That depends on whether trading activity actually develops.
But if tokenized equities become a serious onchain market, I suspect the infrastructure around them will matter just as much as the assets themselves.
The liquidity thesis is worth digging into: OLY.IO
🤝 Paid partnership

Hard truth most founders learn too late:
You can build a product that’s 10x better than your competitors and still lose.
Why?
Because the market doesn’t always reward the best technology. It rewards the products people actually know about and use.
You could spend years building something revolutionary, but if nobody discovers it, none of that innovation matters.
Meanwhile, an average product with great marketing, strong partnerships, and smart distribution can dominate an entire market.
That’s what many founders underestimate.
Building a great product is only half the battle.
Getting people to care about it is what separates successful startups from forgotten ones.
The best product doesn’t always win. The best distributed product often does.

Tokenized stocks in DeFi grew 2,451% to $300M in a yeae.
But I think the distribution tells the real story.
The top 5 assets account for 35.4% of deposits, while the other 2,047 share 64.6%.
That’s roughly $95K per asset on average across the long tail.
To me, this highlights a gap between tokenization and actual collateral utility.
More assets onchain doesn’t automatically mean deeper liquidity or safer lending markets.
And $300M deposited tells us little about how much credit those assets actually support.
Is DeFi building a genuine lending market for tokenized equities, or mostly accumulating assets that remain difficult to borrow against?

Tokenized stocks are slowly but surely becoming DeFi collateral.
$300.1M in tokenized stocks is now deposited in DeFi, up 2,451.5% in a year.
STRCx 15.6%
FWDI 7.2%
SPYx 5.4%
Spread across a total of 2,052 assets.
Data: @tokenterminal

Grvt 2.0 is starting to look like more than just another crypto perp platform.
Following its 1.1M $GRVT buyback and burn, @grvt_io is preparing to launch Stable Funding Perps in November.
Stocks, forex, commodities and indices in one account, with zero trading fees and daily funding.
The goal is 1,000+ markets by year end.
I like the idea of trading different markets without constantly switching platforms.
Liquidity and execution will be the real test, but I’m interested to see how this plays out.

What interests me about @grvt_io goes beyond its 11% target APY.
It’s the idea of earning yield while using eligible assets as trading margin.
On paper, that sounds like a major improvement in capital efficiency.
Your funds aren’t necessarily limited to one purpose anymore.
But here’s what I think traders should pay attention to.
Earning yield on collateral doesn’t automatically make a trading strategy more profitable.
Liquidity, liquidation risk and the reliability of the underlying yield strategy still matter.
That’s why Grvt 2.0 is an interesting model to follow.
If the platform can make these mechanisms work smoothly, it could change how traders think about collateral.
The real innovation isn’t simply earning more.
It’s finding a better balance between capital efficiency, flexibility and risk.

$AAVE is one of 15 tokens in Citrini Research’s “Breaking The Wall” basket.
But the allocations reveal a broader thesis.
48% is concentrated in the top five positions, while derivatives-focused protocols alone account for 27%.
What interests me is that Solana gets just 8%, with the remaining 92% allocated to applications and infrastructure.
I read this as a bet that more of crypto’s value could accrue above the blockchain layer.
But protocol growth and tokenholder returns aren’t the same thing.
Revenue capture and dilution will ultimately determine whether that thesis works.
Are we entering an era where owning the applications becomes more valuable than owning the chains they run on?

What if your trading collateral could generate yield while you trade?
That’s the idea behind @grvt_io 2.0.
Instead of leaving capital idle, GRVT is exploring a model where the same funds can serve two purposes.
→ Earn up to 11% target APY through tokenized fixed-income strategies.
→ Use eligible Earn balances as margin for trading positions.
The yield isn’t guaranteed, and using yield-bearing assets as collateral introduces additional liquidity and liquidation risks.
But the bigger idea is interesting.
Capital efficiency isn’t just about how much leverage you can access. It’s about how effectively you use the capital you already have.
GRVT is trying to make every dollar work harder.
The real test will be whether that extra efficiency outweighs the added complexity.

Crypto prices tell one story. The underlying data tells another.
I went through the 42 page Q4 2026 Digital Asset Report from Glassnode and Fasanara Digital.
What stood out wasn’t Bitcoin’s price action, but how much the market has evolved beneath the surface.
Here are six findings worth paying attention to. 👇
1. Bitcoin absorbed more capital than the previous three cycles combined.
Bitcoin attracted $737B in new realized capital at its November 2025 peak, recovering to $693B after the August correction.
But capital remains concentrated.
Bitcoin dominates 57% of the crypto market, while Ethereum’s share has fallen to 11%.
Unlike previous cycles, capital hasn’t rotated meaningfully into smaller assets.
2. Institutional Bitcoin ownership is increasingly concentrated.
Exchanges, funds, corporate treasuries and other tracked institutional holders collectively control approximately 6.7M BTC.
Spot ETFs hold around 1.3M BTC, with BlackRock’s IBIT accounting for 62% of ETF holdings.
Meanwhile, Strategy holds approximately 848K BTC, nearly two-thirds of disclosed corporate Bitcoin holdings.
Institutional adoption is growing, but so is ownership concentration.
3. Bitcoin options have overtaken futures in open interest.
Five years ago, Bitcoin options open interest stood near $8B. Today, it’s around $40B.
The options-to-futures open interest ratio has climbed from 0.63 in 2021 to 1.07.
This suggests a structural shift toward hedging, volatility trading and more sophisticated risk management.
Bitcoin derivatives are becoming more than leveraged directional bets.
4. Stablecoin usage is growing faster than supply.
Total stablecoin supply stands near $301B, up just 7% year over year.
Yet daily transfer volume has reached approximately $200B, a 22% increase.
$USDC accounts for roughly 70% of tracked settlement volume despite representing only about a quarter of supply.
The interesting part isn’t how many stablecoins exist, but how actively they’re being used.
5. Traditional assets are rapidly entering crypto derivatives markets.
Perpetual trading volume linked to stocks, ETFs, indices and commodities surged from $23.5B to $778B in nine months.
That’s 33x growth.
Their share of perpetual volume across the studied exchanges increased from 0.5% to 23.5%.
Binance captured 55.2% of this market in August, while traditional assets represented 35.2% of Hyperliquid’s perpetual volume.
Crypto infrastructure is increasingly becoming infrastructure for traditional markets.
However, trading volume alone doesn’t guarantee deep liquidity.
6. Tokenized equities are gaining traction.
Glassnode tracked approximately 254K addresses holding xStocks tokens, five times more than a year earlier.
The combined onchain value of xStocks and bStocks reached approximately $1.37B by September.
Still small compared with traditional equity markets, but growing despite the broader crypto correction.
The bigger picture
What interests me most is that two transformations are happening simultaneously.
Bitcoin is becoming a more institutionally owned financial asset, while crypto infrastructure is expanding into stablecoin settlement, tokenized equities and traditional asset derivatives.
Prices have struggled, but financial activity continues to develop beneath the surface.
That doesn’t guarantee higher valuations.
It does suggest that the next phase of crypto may be defined less by token speculation and more by how much real financial activity moves onchain.
Figures reflect the report’s historical observation periods.


Source: Glassnode × Fasanara Digital | Q4 2026 Institutional Market Perspectives
research.glassnode.com/fasan…

Most traders focus on making their next profitable trade.
But what about the capital sitting between those trades?
That’s where @grvt_io gets interesting.
With Grvt 2.0, eligible assets can potentially earn up to 11% APY through tokenized fixed-income strategies.
And with Yield as Margin, eligible balances can continue earning while supporting trading positions.
Of course, yields aren’t guaranteed, and additional risks come with this model.
But I like the direction.
Trading shouldn’t just be about how much capital you have.
It should also be about how efficiently you use it.
That’s the kind of innovation I want to see more of in DeFi.

EVERYTHING IS RED. WHAT’S REALLY HAPPENING?
Bitcoin: -4.1%
Ethereum: -5.4%
S&P 500: -1.2%
Gold: -2.3%
Silver: -3.5%
Crypto is crashing, stocks are falling, and even traditional safe havens are getting sold.
When almost every asset drops together, there’s usually something bigger happening beneath the surface.
Here’s what could be driving this selloff. 👇
1. Fed uncertainty is shaking the market
Investors are increasingly concerned that interest rates could remain higher for longer.
Higher borrowing costs reduce liquidity, make leverage more expensive, and increase the appeal of cash and short-term bonds.
That’s particularly painful for speculative assets like crypto.
2. Rising oil prices are adding inflation pressure
Higher energy costs can push inflation expectations upward.
That creates a difficult situation for central banks.
→ Inflation remains a concern
→ Rate cuts become harder to justify
→ Financial conditions stay restrictive
And markets hate uncertainty about monetary policy.
3. Investors are reducing risk everywhere
This is arguably the most interesting part.
Bitcoin is falling. Stocks are falling. Gold is falling.
These assets don’t normally move together all the time.
But during periods of market stress, investors sometimes sell whatever they can to raise cash.
It’s not necessarily about which asset has the strongest fundamentals.
It’s about liquidity.
4. Crypto leverage is amplifying the decline
Crypto has another problem: excessive leverage.
When prices fall, leveraged long positions can get liquidated automatically.
Those forced sales push prices lower, potentially triggering even more liquidations.
The result?
A relatively ordinary market decline can turn into a much sharper correction.
➜ 5. The US dollar could be another important factor
A stronger dollar and rising Treasury yields can create additional pressure on assets priced in USD.
Gold and crypto are particularly sensitive to changes in liquidity expectations and real interest rates.
That’s why watching the dollar and bond market matters just as much as watching Bitcoin.
◢ SO WHAT HAPPENS NEXT?
I believe three things will determine the next major market move.
→ Whether inflation expectations begin cooling
→ Whether the Fed signals a more supportive policy outlook
→ Whether genuine buying demand returns after leveraged positions are cleared
Here’s my perspective.
A market where everything is being sold isn’t necessarily a market where everything has suddenly lost its value.
Sometimes it’s simply a market desperately searching for liquidity.
But that doesn’t automatically mean the bottom is in.
✧ The biggest opportunities often emerge when fear is everywhere, but patience matters more than trying to catch the exact bottom.
I’m watching liquidity, not just price.
Because the next sustainable rally won’t be built on liquidations ending.
It will need real buyers.
Are we witnessing a temporary liquidity shock or the beginning of a much deeper correction?


What if your trading collateral could earn yield while backing your positions?
That’s what @grvt_io is building with Grvt 2.0.
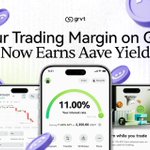
Eligible assets could earn up to 11% APY while eligible Earn balances serve as trading margin.
The yield isn’t guaranteed, and additional risks apply.
But the idea is powerful.
Why let your capital sit idle when it could work twice as hard?

Imagine getting paid millions to promote a platform, then quietly removing it from your bio.
That’s exactly what appears to have happened here.
Meanwhile, Pumpfun’s revenue and active users are declining.
The real question isn’t why @kimchi1x removed @Pumpfun.
It’s what he knows that the market doesn’t.

Just 2 days later, @kimchi1x removed @Pumpfun from his bio.
Interestingly, over those 2 days, Pumpfun's revenue dropped 16% from $1.61M to $1.35M, while active addresses fell 11% from 178,539 to 159,492.
Meanwhile, @kimchi1x may have received 1.35B $PUMP ($6.25M) in marketing fees.
defillama.com/protocol/pump.…


Gold is dumping, but I’m still bullish.
> Gold and $BTC share a macro connection, often benefiting from inflation and declining confidence in fiat currencies.
The market is pricing in another Fed rate hike before the end of the year, putting pressure on gold.
Meanwhile, rising oil prices are fueling global inflation, reinforcing expectations of tighter monetary policy.
But here’s what matters:
China has been accumulating gold for 23 consecutive months. Central banks are buying while the market is selling.
Higher rates may keep gold under pressure for now, but they won’t last forever.
My view? This is a temporary macro headwind, not the end of gold’s bull market.
I’m expecting significantly higher gold prices in the coming years.
Short term pressure. Long term accumulation.


Why should trading collateral stop earning the moment you decide to use it?
That’s the part of Grvt 2.0 I keep returning to.
Following its first 1.1M $GRVT buyback and burn, @grvt_io is preparing a broader product rollout.
Grvt Earn targets up to 11% yield through tokenized fixed-income strategies, although returns aren’t guaranteed.
But Yield as Margin is where the model gets interesting.
Eligible Earn balances could continue generating yield while supporting trading positions.
That’s potentially a meaningful change in how traders allocate capital.
Of course, the real test will be collateral haircuts, liquidation mechanics and redemption liquidity.
Can yield-bearing margin become a practical alternative to idle collateral?

$41.6B in open interest across $BTC, $ETH and $SOL.
People easily stop at size, but the interesting part for me is what happens if price stops climbing.
Rising OI alongside a recovery suggests traders are adding exposure, but it doesn’t tell us whether longs or shorts are driving it.
And with ETH accounting for $15.5B, leverage is clearly not concentrated in Bitcoin alone.
I’m watching funding rates and spot volume next.
If price keeps rising with healthy spot demand, that’s constructive. If OI expands while spot buying fades, the recovery becomes increasingly vulnerable to a liquidation-driven reversal.
Are we finally seeing genuine demand return?


Ethereum is becoming a victim of its own success.
Record ETH staked. Declining yields. Fewer validators.
Nearly 36% of the entire supply is now committed to staking, even as the financial incentives weaken.
The market sees this as bullish supply compression.
But there’s a bigger question nobody seems to be asking:
What happens when locking up ETH stops being worth the return?


Stablecoin supply is barely growing, but the money is moving faster than ever.
$891B in adjusted transfers during Q3 2026, more than 4x early 2023 levels.
And 73% of screened volume happens outside US banking hours.
Meanwhile, 7 of the 10 largest US banks have already tested stablecoins or tokenized deposits.
Yet total stablecoin market cap remains almost unchanged YoY at ~$301B.
The key read here? Stablecoins are increasingly about moving existing dollars more efficiently Also Beyond the on chain layer.
At what point does 24/7 settlement become something businesses expect rather than an advantage crypto offers?
