

Passion for personal finance, innovative ideas & the well being of my clients. Founder of TIER Wealth in Calgary. President of the IAFP.
Calgary, Alberta
Joined March 2011
- Tweets8.9K
- Following431
- Followers8.7K
- Likes9K



Pinned Tweet
It's been 8 months since @TIERWealth was launched.
We're a little different than most of our competition in the wealth management space. Actually, we're a lot different.
Here are 5 (of many) things we do that set us apart:
1. Credentials. Our team is qualified. We have top tax credentials (CPA, CA), top investment credentials (CFA, CIM, FRM), top estate credentials (TEP), and top financial planning credentials (CFP, R.F.P.).
2. We don't only do tax planning. We file tax returns. That means less gets lost in translation from the plan, to implementation, to preparation.
3. We have tools that others don’t—because we built them. Examples:
A tax instalment calculator that helps us advise how much you should remit to CRA, and when—especially when your tax situation is different now than it was in the past.
A corporate executor cost comparison tool. If you’re considering a corporate executor in your Will, we can show you what the various providers would charge your estate.
OAS/CPP tools that visually show the optimal year to start benefits based on different longevity scenarios—and depending on whether you spend or invest your CPP/OAS once you receive it.
4. We do the extra things. Like:
Helping you decide which investments to donate to charity to get the best tax outcome—then completing the paperwork and sending it to the charity.
Charging TFSA fees to non-registered accounts, because small details like this add up over time and keep more money compounding without tax friction.
Asking our snowbird clients how many days they spent in the U.S. each year so we can complete and file Form 8840 (Closer Connection Exception) and reduce the risk of being treated as a U.S. tax resident.
Getting authorized to access a client’s CRA account to confirm instalments—then remitting the payments to CRA on their behalf, so they don’t have to think about it.
5. We focus on your estate, and your heirs. We prepare custom estate flow charts that show exactly what will happen if you die—for each and every asset and liability you have, big or small. It’s not just arrows—it’s numbers. And we update those numbers every single year, so our clients always know what would happen.
Oh...and we do the regular things too.
TIER Wealth
Tax | Investment | Estate Planning | Retirement Planning
Our name is what we do.
If you want to learn more, set up an introductory meeting through the link on our website.
tierwealth.com

If Melissa sounds like you, spend a few minutes to look around.
You could find a lower plan in the amount of time it takes you to post about your expensive one on X.
From a happy Koodo customer.

Spend a bit of time on our blog and you might learn a trick or two.
Below are four that are relevant for the end of the year, and especially so if you give to charity (including US charities) or are thinking about retiring soon.

A toolkit of four year-end tax & gifting strategies for those who are nearing retirement and/or like supporting domestic and US charities, from the TIER blog archives:
1. tierwealth.com/blog/two-smar…
2. tierwealth.com/blog/smart-rr…
3. tierwealth.com/blog/charitab…
4. tierwealth.com/blog/donating…

Remember that your medical expenses don’t have to be a calendar year. Any 12 month claim period that ends in the current tax year can be claimed.
So, for example, for your 2026 tax return you could choose Jan 2, 2025 to Jan 1, 2026 and use that for your 2026 medical claim.
Or Oct 25, 2025 to Oct 24, 2026.
Of course most will choose January 1, 2026 to December 31 2026.
You can’t use the same period for more than one tax year, so if last years tax return reported receipts up to December, you can’t choose a claim period that starts earlier and double up on the same amounts on two different returns.
I’m saying this now because if you had a larger expense at the end of last year, but it wasn’t quite enough to hit the annual threshold where it counted, you could try and accelerate certain expenses at the end of 2026 to tuck it into the same 12 month period.
Getting close to the threshold but not quite every year is a waste if you understand the timing of expenses (where there is flexibility, like new eye glasses) can get you an extra 20+ percent off that you could easily miss if you aren’t thinking this through in advance.
The 2027 indexed figures are calculated, with an unusual amount of depth for those who care to know how things work.
Fifty-five federal figures in total - mapped out - and published about a month earlier than you'll see them otherwise.
The 2027 Tax Brackets, Benefit Amounts, and Financial Planning figures are now determined.
Read the latest @TIERWealth blog for ALL of the details and why we can publish these now, instead of waiting until mid-to-late November for the CRA announcement. tierwealth.com/blog/2027-ind…

Aaron Hector, R.F.P., CFP, TEP retweeted

Canadian Corporate Tax Explained: How Integration Works
If you own a Canadian corporation and nobody has ever walked you through how Canadian corporate tax actually works, start here. This is the foundation for everything else on corporate tax planning.
youtu.be/ZfS2johugHY?si=jOsh…

The CPI data is in for September 2026... and that gives us the entire dataset to calculate the annual index rate that will be used to move many tax and financial planning figures from 2026 to 2027.
That figure is now locked in. The index rate is 2.6%.
A full blog has been written for @TIERWealth with all figures that we can determine right now. It will be published as soon as it goes through our internal review process.... so watch for that in the next week, but for now, here are a few teasers:
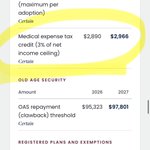
- The OAS clawback threshold moves from $95,323 to $97,801
- The TFSA limit for 2027 is confirmed at $7,500
- Lifetime Capital Gains Exemption (LCGE) moves from $1,275,000 to $1,308,150
- Federal Tax Brackets (beginning of each bracket noted)
- 20.5% bracket moves up from $58,523 to $60,044
- 26% bracket moves up from $117,045 to $120,088
- 29% bracket moves up from $181,440 to $186,157
- 33% top bracket moves up from $258,482 to $265,203
Stay tuned for more at tierwealth.com/blog

PS - this is not a surprise - A year ago I explained how the math regarding the 2027 limit was already locked in place by this time last year. theglobeandmail.com/investin…

I estimate the OAS clawback threshold for 2027 will increase from $95,323 to $97,801 (plus or minus a dollar)
I sent a client an email recently on a multi-child RESP withdrawal plan.
The report sent showed why we were recommending what we were doing, and compared it to three other logical drawdown paths (one of which was taking the full ‘no receipt’ EAP max each year, which I had suggested we do last year).
I told them in hindsight we would have made a different recommendation last year, but we’ve improved our thinking, and with improvements comes different advice.
Continual improvement means you have to admit that you could have been better in the past… but that’s a lot better than not giving better advice simply to stay aligned with what you’d suggested before.
Aaron Hector, R.F.P., CFP, TEP retweeted
Pictures can say a thousand words.
Here’s a quick thread on dividends, as told by Granny Smith.

There is a door that’s still open today for financial planning firms to attract a lot of business while providing non-personalized “everyone gets the same rule of thumb advice.”
I estimate that the door is going to slam shut on them relatively quickly if they don’t evolve and figure out how to customize their advice…. Because the people I know and respect are figuring out how to do things at a much higher and more customized level.
Like many industries, the raw computing power that’s at our fingertips to run scenarios and simulations is expanding all the time.
Calgary advisors who are curious about Q Wealth and advisor incorporation in general...
Q-Wealth is hosting an after-hours this Thursday, Oct 22 from 6pm to 9pm at The Ampersand.
Free food and drinks, and good conversation.
youtube.com/shorts/ezFbseXIK… via @YouTube

Kind of odd that when you find an error in a tax publication from a very respected large national firm and you privately reach out to one of their leaders (who is named on the publication) to inform them you caught an error, that they don't reply.
Wouldn't you want to know?
It may not seem like much, but one of the things I’m most proud of is that we’ve finally solved the problem that I consistently received as feedback from my older clients over the years.
“My eyes are not that great anymore, I really wish the font on these reports was easier to read.”
For years, and years, I wanted to fix this but it just never got fixed, from one organization to the next as I found myself moving into larger and larger companies by way of corporate acquisitions.
Now, we have a button right on the report to address this accessibility issue.
It’s not as ‘clever’ or ‘flashy’ as a flying car (or some of our other stuff)… but it’s a real value add that’s going to move the dial for our clients who fall into the demographic who will find this useful.
It just floats on the page - always there if it’s needed, never in the way if you don’t.

Live comments during a recent demo of TIER Wealth's client deliverables (from another business owner of a Canadian financial services company)

Spousal Loans can be useful in one period of your life, but it's also possible that they can negatively impact your tax outcome later on in life when your situation changes (employment/rrif minimums starting, etc).
Managing the repayment of a spousal loan tax effectively is probably more interesting than putting the loan in place at the first time.
For example, once the loan no longer serves it's purpose, someone with a blend of loans placed at different prescribed rates over time (1%, 2%, 3%, etc) should actually prioritize repaying the 1% loan first.
It's counter-intuitive, but it's true.
Figuring out how best to unwind while limiting unnecessary early capital gains is another interesting twist.
I put together a multi-year tax efficient repayment plan today for a client so this was top of mind and thought I'd share.