

Founder | @ALSTOCKTRADES // @NeuroSurgGlobal Homelessness to Multimillionaire
Wall Street, New York
Joined December 2017
- Tweets3.9K
- Following86
- Followers3.5K
- Likes6.9K







Pinned Tweet
I've been fighting this whole time with my hands tied behind my back. Now I am unleashed.
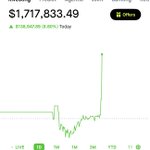
My mind, the very thing they mocked, just built a public portfolio worth $1.475 million with my
company valued over $50 million.
You're not just going to see my brain power. You're going to feel it rumble through the ground
beneath your feet. $CLOV $OPEN $SOFI


$CLOV
It is entertaining to watch so many people suddenly love Clover Health after years of doubting it, and I give full credit to Peter Thiel for teaching me that the money is made on the other side of the crowd.


Hospitals using AI are seeing better healthcare outcomes.
In 2023, health systems with high and low AI use had the same death rate: ~1,600 per 100,000 patients.
By 2026, the systems using AI the most dropped to ~1,000 deaths per 100,000.
That's a decline of nearly 40% in just 3 years.
Meanwhile, hospitals with lower AI adoption have seen significantly smaller improvements.
The gap in patient outcomes is widening as AI adoption accelerates.
AI is rapidly transforming healthcare.

$CLOV
Sleep schedule is wrecked after a couple weeks of nights, so of course I’m wide awake on my day off at 1am. Figures.
Scrolling around I came back to a press release from Counterpart Health, a subsidiary of Clover Health, dated December 10, 2025. It said hundreds of live third party customer clinicians are on CA, representing an increase of more than 450% year over year, and 80% of them went live in the last 3 months. I keep thinking about that number. I can only imagine what it looks like now.
Between the hires and the growth showing up in different parts of the US, this side of the business clearly has momentum. In less than 2 months we will hit a year since that release, and it will be interesting to see where the numbers land.
I honestly think a lot of people are sleeping on this part of the business. It’s growing fast and most folks are focused on other things.
What stands out to me is that Clover Health’s insurance program is funding all of this while the business still stays profitable. That’s not an easy thing to pull off, and I think it deserves more attention.
Anyway im going to try to get some sleep, or at least pretend to.

At Counterpart Health, we’re delivering measurable, sustained improvement in quality, risk, and total cost of care, starting with @CloverHealth and expanding rapidly to new clinicians.

Washington ran a $2 trillion deficit this year, and Medicare just published the list of doctors who are going to help pay for it. Almost every name on it holds a scalpel, and the brain surgeons are not exempt.
Neurosurgery is the specialty everyone assumed Medicare would never touch, and it just did. CMS pencils in a 2% cut, but when the actuaries at Wakely ran the rule against real Medicare claims, neurosurgery and orthopedic surgery took some of the biggest losses in medicine, and dermatology, ENT and orthopedics are down 7 to 9% before a 1.68% cut to the base rate everyone gets paid.
Surgeons are not being punished for being overpaid. The country is broke. We now pay more in interest on the debt than we pay the entire military, health care eats 18 cents of every dollar in the economy, and Medicare’s hospital fund runs dry in 2033 with automatic cuts the day it does.
And cutting doctors does not fix any of it. Physician pay is about 8 cents of every health care dollar. The entire Medicare physician fee schedule is about $94 billion a year, roughly one month of interest on the national debt, and the 1.68% cut saves about $1.6 billion, which is seven hours of federal borrowing. The fee schedule is not a savings plan. It is a steering wheel, and it points at the kind of medicine Washington wants more of.
Look where it points. Family medicine is in the winners column while nearly every surgical specialty is not. CMS is paying a 16% premium on the visit with a doctor who actually knows you, 32% inside an accountable care group, and asking how to pay primary care up front to keep you healthy instead of a fee for every visit. Three in four American adults have a chronic condition, and the family doctor who catches the blood pressure, adjusts the insulin and notices the depression keeps that patient out of the ER and away from the amputation and the dialysis chair. Every hospital stay that never happens is money the system never spends.
The surprise winner is interventional radiology, up about 3%. IR treats the diseases surgeons treat, but through a pinhole with live imaging instead of an incision. Fibroids get embolized instead of the uterus coming out, blocked leg arteries get opened instead of bypassed, a stroke clot gets pulled out through a catheter, and the patient goes home the same day with a bandage where the incision would have been. No 90 day recovery for Medicare to fund, no bundled follow up visits in the price, and in a fixed pot of money every dollar pulled from surgery gets spread to everyone else. A broke system does not stop treating disease, it pays more for the version that costs less.
None of this is really about doctors. It is about the 68 year old diabetic with a blocked artery in her leg, who does not care which specialty wins the fee schedule. She cares whether she keeps the leg, whether she sleeps in her own bed tonight, and whether the bill lands on her grandchildren. For a century American medicine paid best for the doctor who could cut. Washington just started paying more for the doctor who keeps her out of the operating room and the one who can fix her through a pinhole and send her home by dinner.
beckersasc.com/asc-coding-bi…

$CLOV
When I kept talking about Clover Health all the way down to $0.60 a share, people thought I lost my mind. Today U.S. News & World Report named Clover a Best Medicare Advantage Plan in three states.
What I saw was never an insurance company. It was software wearing an insurance company as a coat, and now that the quality ratings, the profits, and the growth have all shown up, that same software is being sold to other insurers, which is how a regional Medicare plan becomes a national healthcare technology platform.
On a side note, I went into academia because it promised to push the boundaries of what we know, and I still love it for that. What I didn’t expect was how McDonaldized it had become, where every output has to look like the last one and the safest path is to summarize what exists instead of building something new. I came up inside that system and respect the people grinding in it, but when the tenth meta analysis on a question earns more credit than building the first thing that actually answers it, the kitchen only knows one recipe. So I made sure it wouldn’t be my only lane and pointed part of my brain outside the building, at impact.
Most people were judging the movie by the first ten minutes. I had already seen where the story was going, and if all you’ve watched is the opening scene, the guy reacting to the ending looks crazy. That is exactly what being early feels like. Thinking outside the recipe is the alpha, and the alpha is why I’m standing here today. After the degrees, the research, and years of collecting data, the student phase is over, and this time I’m acting on what I see and building on my own terms.


$CLOV
Nothing we didn't already know. Glad the world is catching on.
From quarterfinalist to finalist — Counterpart Health is advancing in Transformative Care Delivery at the 2026 Digital Health Awards.
This recognition reflects what Counterpart Assistant is built to do: give clinicians the context they need to deliver more complete, proactive care for patients with chronic conditions — without adding to their workload.
Proud to represent the care teams who trust CA every day. See you at #HLTHUSA in November.


$CLOV
Clover is doing something most health plans would never dream of: it is shopping for its AI suppliers in public, and it only wants the ones that are ten times cheaper than the standard tools.
In plain English, Vivek is asking any AI company that can do what the big enterprise vendors do at a tenth of the price to raise its hand, so Clover can plug that tool straight into how it runs a Medicare Advantage plan.
This matters because healthcare has always been reactive rather than proactive, and that was survivable when the world moved slowly. The world does not move slowly anymore.
Every major wave of technology ends with companies eating each other. BlackBerry was the incumbent until Apple showed up, and Blockbuster was the incumbent until Netflix did. Neither of them lost because they were bad at the old job. They lost because they kept doing the old job while the ground moved underneath them, and history has already ruled on this one.
The same pattern is now forming inside AI itself. Companies are spending staggering amounts of money on frontier models, and Meta’s Muse just showed everyone that you do not need the strongest model to get real work done. Meta’s own management acknowledged Muse Spark trails the top models in some areas, then priced it far below the big labs anyway, and Zuckerberg followed up by releasing Muse Glimmer as open weights, a model that runs on a single consumer graphics card. That is a direct problem for any frontier lab charging an arm and a leg for capability most tasks never touch.
Make the math simple with made up numbers. Say the best model charges 100 dollars for a job and an open source model does the same job for 10 dollars. That is a 90 percent cut in cost, and if the output is close to the same, the result for whoever is paying is extraordinary, because the quality stayed put while the price collapsed.
Jensen Huang has made the point that a small team of developers can now build a multibillion dollar company, and that is exactly the kind of company Vivek is hunting for. It looks nothing like a traditional vendor with a sales force and a seven figure contract. It looks like a handful of experts who built one narrow tool extremely well, whether that is coding charts, reviewing claims, clearing prior authorizations, or flagging the patient who is about to land in the hospital, and Vivek wants to bolt those tools onto Clover’s platform so the plan runs on specialist AI at a fraction of what the standard software costs.
The incumbents cannot copy this quickly, and that is the whole opportunity. A large company needs three to five years, sometimes seven, to make a real internal change, and Charlie Munger explained why in Poor Charlie’s Almanack. Once a business gets fat and bureaucratic, people start to believe that answering a memo is the same as doing the job, and the actual work quietly stops.
Healthcare is in disruption mode because the recent downtrend in Medicare Advantage forced it there. The industry has realized it has to incorporate artificial intelligence just to survive the margin pressure, and the way I read it, that pain is the beginning of a long bullish cycle for Medicare Advantage rather than the end of one.
The real question is whether Clover can keep innovating and keep widening its moat, or whether this is one clever move. If Clover can get the same capability the incumbents pay frontier prices for, at a fraction of the cost and with better outcomes, that is a structural advantage, and structural advantages are where high alpha comes from.
The winners of this cycle will not be the companies with the most expensive AI. They will be the companies that get the same answer for a tenth of the price and act on it before the incumbents finish their meetings.
Until Next Time,
Albert Alan, MD

Our COMMIT team at Clover is on a tear, excited for what we’ll be rolling out in the coming years.
If you’re an AI solutions vendor, and you believe you have achieved an order of magnitude pricing advantage vs any of the “standard” solutions out there, comment here and we’ll reach out.
cloverhealth.com/commit

Open Evidence > ChatGPT for Clinicians
My conclusion after 2 weeks of usage. ChatGPT, for clinicians, fails at the point of care.
$CLOV
Joseph Schumpeter explained in 1942 why so much of today’s enterprise AI revenue is likely to evaporate, and the same idea explains why Clover Health built its AI the way it did. I’ll walk through it one step at a time: what Schumpeter said, why it threatens most AI companies, a simple test for any AI company’s revenue, and what happens when you put Clover through that test.
Start with the prediction that set this off. Vivek Garipalli, who cofounded Clover Health, predicted in February that for almost all of today’s richly valued enterprise AI companies, though not all, much of their annual recurring revenue will disappear rather than simply slow down. Schumpeter’s idea of creative destruction explains why. He described capitalism as constantly rebuilding itself from within, “incessantly destroying the old one, incessantly creating a new one.” The competition that really matters, he argued, doesn’t come from a rival charging a little less. It comes from four forces: a new commodity, a new technology, a new source of supply, and a new type of organization. That kind of competition hits a business at its foundation instead of its margins, which is the difference between revenue that slows down and revenue that evaporates.
The irony is that these AI companies grew so fast because they were the creative destroyers, and now all four forces are pointed back at them. Their output, whether it’s a drafted contract or a summarized chart, is the new commodity, and it gets cheaper every time a new model comes out. Each model release is new technology that swallows features startups spent a year building. The platforms they plug into, and even their own customers, are becoming a new source of supply by building the same tools themselves. And the new type of organization is a small team inside the client that pairs real knowledge of the business with AI, which is exactly where Vivek told engineers to go.
We’ve already watched this happen once. Jasper was valued at $1.5 billion in late 2022 for putting a polished writing tool on top of OpenAI’s model. A few weeks later ChatGPT gave away a version of that product for free, and Jasper went on to cut its internal valuation, lay off staff, change CEOs, and rebuild itself around how its enterprise customers actually work.
I’m watching the next round from inside the hospital. Investors put close to a billion dollars into AI scribe companies in 2025, and then, less than a week before Vivek’s post, Epic rolled out its own AI charting tool directly inside its record system, which is the largest in the country. Turning a conversation into a note is becoming a commodity. What isn’t a commodity is knowing what that note has to accomplish after it’s signed, from the billing level to the prior authorization to the discharge that stalls over one missing detail, and that is the client knowledge Vivek is talking about.
So how do you tell real AI revenue from revenue that’s about to evaporate? Ask whether it would survive three events:
1) the next model release making the core feature nearly free.
2) the platform it plugs into shipping the same thing.
3) the customer hiring one strong engineer to build it themselves.
The test matters because enterprise customers aren’t loyal yet, and a Madrona report covered by TechCrunch in September found that many still don’t commit to AI products long term, even after the pilot ends. Revenue that survives all three events belongs to a real business, and revenue that doesn’t is closer to an experimental budget that happens to be counted as ARR.
Now connect the dots to Clover, starting with Vivek’s own rule. He says an AI company survives only if its founders deeply understand the client’s business: the goals, the workflows, and the decisions. Most AI vendors learn that from the outside, in sales meetings, but Clover learned it by being the client. Clover runs a Medicare Advantage plan, which means Medicare pays it a set amount each month for every member, adjusted for how sick that member is, and Clover keeps whatever is left after paying for that member’s care. Clover makes money when its members stay healthier for less, so it built Clover Assistant, a tool that helps the doctors caring for its members find and manage chronic disease earlier. Since 2024, a Clover subsidiary called Counterpart Health has been selling the same tool, renamed Counterpart Assistant, to other health plans and doctor groups, and every one of those buyers has the exact problem Clover has been living with for years.
The second dot is Schumpeter’s fourth force, the new type of organization. Vivek told engineers to leave AI vendors and go work inside the client, where the real business knowledge lives. Clover is that same idea at the scale of a whole company: an insurer that builds its own software, proves it on its own members, and then sells it to other plans.
The third dot is what Counterpart actually sells, which is a result instead of a feature. A scribe company sells a drafted note, and a cheaper model can draft the same note, so every new model is a new competitor. Counterpart is built to sell lower medical costs, so every new model is just a cheaper and better ingredient. In its Q2 2026 supplemental, filed with the SEC on August 20, Clover reported that members managed with the tool had a medical cost ratio about 18% better than members who weren’t, in year three. Medical cost ratio is the share of each premium dollar that goes to paying for care, so lower is better for the plan. Clover also describes Counterpart’s pricing as value based, which can include per member per month fees, shared savings, or capitation. When a vendor gets paid out of the savings it creates, its revenue depends on the result instead of on how many people log in.
The last dot is the three event test, and running Counterpart through it shows how the logic works. A better model doesn’t make the product free, because the hard part isn’t the model but years of claims data and knowing which prompts actually change what a doctor does, so a better model is just an upgrade Counterpart plugs in. A client’s own engineer could rebuild the software, but not the years of results behind it. The real risk is the platform event, for example Epic adding similar prompts inside the chart. The counterargument is incentives, because Epic mostly answers to hospitals, while Counterpart gets paid by whoever carries the cost of care, so it has the stronger reason to tune every suggestion around lowering that cost.
That’s the logic. The 18% figure is reported by Clover and comes from its own members. In its Q2 2026 materials, Clover didn’t name any outside customers, break out Counterpart revenue, or report results from other plans’ members, and in May management described only “early traction.” Vivek also cofounded Clover, so his prediction describes his own company’s strategy, which is a good reason to test it rather than take it on faith. By his own test, the proof will be outside clients renewing and seeing similar results in their own members.
Schumpeter called this the perennial gale of creative destruction, and the key word is perennial, because the gale that built today’s AI companies doesn’t stop once they’re worth billions. The companies still standing will be the ones that own an outcome for their customers instead of renting out a feature. Tell me which other AI companies you think pass that test, because those are the ones most likely to still be here in five years.
True success comes from knowing the edge of your competency. 'Chauffeur Knowledge' is superficial mimicry, while 'Planck Knowledge' is deep understanding. If you play where others have Planck knowledge and you don't, you lose. Practical Advice: Draw a clear perimeter around what you know and never bet outside it.
$CLOV
“The plan that grasps principles can successfully select its own methods. The plan that tries methods, ignoring principles, is sure to have trouble.”
Emerson, Medicare Advantage edition
Swapping man for plan is all it takes to turn that quote into the story of CLOV, because Vivek Garipalli built Clover from first principles. After running a hospital system and watching insurers and providers work against each other, he started from one idea: better outcomes come from better clinical decisions, and better decisions need complete patient data at the point of care.
Becoming an insurer was the method he selected, not the principle, because he only turned Clover into a health plan to get reliable access to that data. Since the principle never depended on Clover being the insurer, Clover Assistant now has a Counterpart that other plans and providers can use.
You find out whether a company really runs on a principle when the scoreboard turns against it. When CMS gave the PPO 3.5 stars last fall, Clover guided to rising adjusted EBITDA through 2027 independent of the rating, and its PPO still scored 4.72 on HEDIS clinical quality. After Clover won in federal court and CMS recalculated the rating to 4.5 stars, Andrew Toy made the same point from the other side, saying the stars give Clover room to reinvest but do not create its economics. CMS has appealed that ruling, but a physician making a better decision with complete data is the one part of this story nobody can appeal.
The rest of Medicare Advantage should read the second half of that quote twice. Plans that lean on prior authorization and narrow networks to control costs, without improving the decision in the exam room, are trying methods without a principle, and Emerson already told us how that ends. He wrote his line about a man, and Clover has spent more than a decade proving it about a plan.
Albert Alan, MD
Pretty fun to watch many VCs invest at pretty insanely high valuations for Enterprise AI companies with rapidly growing ARR.
Prediction - for almost all of these companies (but not all), much of this ARR will eventually evaporate (and not just slow down).
The probability of success for these Enterprise AI companies will directly correlate to the CEO/founder(s)' ability to deeply understand the industry domain/business goals/outcome goals/workflows/decision trees of their individual clients - very few have a CEO/founder(s) that deeply understand their clients' businesses.
If it's so simplistic that a deeply nuanced level of understanding isn't needed, then the offering will also eventually reflect that in commodity pricing.
If you are an eng working at one of these Enterprise AI companies, and deeply understand your client(s)' business, you should think about selling your vested shares at a very high current valuation, and just go to the client side now, you'd command an extremely high salary/bonus relative to what you're getting paid now - and will command that for a long time to come - and you'll get a lot of joy driving direct outcomes.
Good luck to all.
$CLOV
What a good human being. Luckily the community is strong enough to not fall for this bullshit.
This Post is from a suspended account. Learn more
Albert Alan, MD retweeted

Clover Health's PPO just earned 5 stars for payment year 2028. Only 15 Medicare Advantage drug plan contracts did that.
youtu.be/2UFF5BLW8qY?is=RJLs…
@cloverhealth @VivekGaripalli @counterparthlth $CLOV
Thank you @AlbertAlan @ALSTOCKTRADES my life has changed because of you.
