

ShitCo connoisseur | focus on biotech | long form stuff might end up on the stack | Why so serious it´s only money | NFA
Joined February 2021
- Tweets2.3K
- Following288
- Followers3.3K
- Likes1.5K





For sure and that´s why I usually pitch baskets. I will and never have put any of your inevitable misses against you. It´s biotech, part of the game (of probabilities) and one should size accordingly.
Anyway, best of luck with North. Hope you succeed, regardless of my position.
Man, immediately getting a slap on the head if I get pumpy once. Didn´t want to put you in an awkward position
True. In the end, they need a strong PIPE (implying decent asset selection / investor interest) which will dominate the outcome and public perception anway.
Unique thing about TIL is that it is the shell with the largest discount to book if I´m not completely off, so the margin of safety is larger than on other names already implying 70%+ PoS for a decent merger. Shitty asset / transaction always a risk in these names anyway.
But we´ve seen the most horrible shells getting strong deals (thinking NXTC / CYCN / AEMD kind of stuff) and clean, large shells doing rather boring stuff (FULC RLYB maybe) and I haven´t found a reliable way to predict quality. But a financial margin of safety sure doesn´t hurt
7) Monitoring / having a 10bps starter in some others but they are either tiny or a huge piece of shit (mostly both lol), maybe interesting at a later date.
6) $ARTV from yesterday. I guesstimate they will have 4.6$/share in net cash mid year 2027 but I might be very wrong on the cost of monitoring existing patients (to prevent further deaths). Still, it is a large cash shell so impact will not be that huge.
The very large caps though often don´t have that strong of a reaction (see FULC), so maybe you´re better off waiting for better prices or even buying after an announcement? Hope they will pay a large dividend as well, in which case the risk to buying this here sub 4.3$ is probably negligible.
Obv shell value has not that much of an impact on a ~235 mln$ market cap. Tend to think I´m a bit early too this, but I like to be involved early to get to know the stock / tape and we have seen some very quick transactions recently (sub 60 days from strategic alternatives announcement until DA)
5) $TXMD still in legal limbo, but even an adverse outcome against Mayne is priced in imo and a shell value of 15-20 makes this obviously even better if they RM.
Wrong on this timeline wise so far, but I think the case still holds.
teapawt.net/AnotherBio/status/2087…

2/x $TXMD still long still think even an adverse legal outcome won´t wipe this out / impair it too much
teapawt.net/AnotherBio/status/2061…
4) $SNGX is almost certainly in advanced discussions (Aug3: "While we are in some later-stage discussions, as of the date of this letter, we have not entered into any definitive agreements"). Will bring 5-15 cents of net cash into a merger, but if you include the shell value...
Let´s just say the market cap is 8 mln$ and you do the math!
So you´re very screwed if they don´t do a RM but why wouldn´t they? Deal could also be bad if mgmt clings to its jobs (XBIO was a recent bust if you need a negative example). Very risky and illiquid but upside is.. do the math!
3) $ARTV from yesterday. I guesstimate they will have 4.6$/share in net cash mid year 2027 but I might be very wrong on the cost of monitoring existing patients (to prevent further deaths). Still, it is a large cash shell so impact will not be that huge.
The very large caps though often don´t have that strong of a reaction (see FULC), so maybe you´re better off waiting for better prices or even buying after an announcement? Hope they will pay a large dividend as well, in which case the risk to buying this here sub 4.3$ is probably negligible.
Obv shell value has not that much of an impact on a ~235 mln$ market cap.
2) $KPRX had a transaction with ADAR1 and Perceptive with warrants tied to a future M&A transaction. Low float. Will fly on a good deal. I love ADAR1 and Perceptive. Management probably sucks. Has a bit of hair because of management. Expect like 2.3$ net cash/share at the end of 2026. I included the Series A warrants in that calculation.
Probably horrible if management doesn´t pull off a RM / in-licensing, likely very great if they do.
1) $TIL Read this. For real. Almost impossible to lose money imo!
Starting with what I think is a total banger. $TIL owns the Tarzana facility, leased to AstraZeneca in a Triple-Net-Lease. Mortgage is set to renew in January.
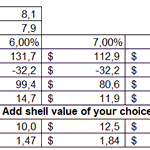
Book value is 112 mln$. Net rent 2027 is ~7.9 mln$ (goes up through the years), slapping a 6-8% cap rate on that gives you 99-131 mln$ property value. There is 85.6 mln$ in debt against the sub owning the property (with recourse to $TIL tbh). $AZN bond till 2037 yields 5.6%, think that supports my cap rate range.
They also have 70 mln in cash as of June30.
Some very important history: In May, TIL decided to NOT sell the facility. Was quite a shock and the stock subsequently got hammered. Now what is more or less unknown to the market is, that $TIL put the facility back on the market on Oct13! Credit to my good friend @Lord_of_Biotech
platform.reverecre.com/proje…
My theory: Company was unhappy with bids, stopped the transaction. Then saw the great RMs happening + strong shell premiums, decided to just sell it. Before january debt maturity is a great time in point anyway.
Go and stress test the valuation: If they sell this at a 10% cap rate (lol) for 79 mln$, the proceeds + net cash as of end of March 2027(!) will be 7$/share! 15/20 mln in shell value in a RM is another 2.2-2.95$/share against a stock price of 6.2$
Transaction at 8% cap rate = 100 mln$ with same net cash 03/31/2027 + shell value = 12.2$-12.9$
How can you lose here? Probably if just nothing happens for two more years for whatever reason. But why? Liquidity is shitty in general as insiders own a lot, but there are some sellers in there right now (or have been, what do I know). So if they stop the sale again, timeline of this goes out a lot and maybe it drops down to 5, but a NNN-lease to AZN for a brand new prime facility isn´t going anywhere?
Substract some transactional costs maybe, but it´s so cheap doesn´t matter down here imo.

Second thread, companies that are going to RM in the forseaable future (mostly 0-6 months but not exclusively). Warning: SpecialShits, some with shitty liquidity.
What´s important to note is that the value allocated to the shell recently rose to ~15-20 mln (see BOLT HOWL) from 7.5-12.5 earlier in the year. Means upside on small market caps can be huge, also means it is risky if you underwrite it before it happens. Draw your own conclusions.
Some of these companies are risky, but I´m 90% sure there are some 50-100% gainers in here. Given the above dynamics, some of these are quite small / illiquid, but OTOH if you get a 20mln shell premium on a 10-20mln market cap already trading sub net cash... Well if I have to explain that, this is not your thread ;-)
This is about getting into AEMD, TCRT, NXTC, BOLT, BOLD etc. before the RM happens.
As the $XBI continues its regular modus operandi of $MRNA and $TWST going up 7% a day, I wanted to share a bit of what I like currently and why. It´s a lot, so I will split it a bit. I think. I´m just making this up as I go.
Went from like 20% net long to 80 (kind of happened somehow, will try to lower a bit near term towards 60ish).
Starting with Reverse Mergers (RMs) with a signed DA. Will follow up with companies that I think will announce a DA soon.
In general I think the quality in RM-land is still very decent and we see few trash RMs (which used to be the norm until maybe 2-3 years ago).
Random order. You will be SHOCKED though to see what #7 does! (no you won´t, stupid clickbaits...)
11) Watching $TCRT but a lot of RMs trading below PIPE currently, don´t see the need to pay a premium here. PIPE 1.43$/share
10) $TCGX same approach, a "why the fuck not"-long around NAV
teapawt.net/AnotherBio/status/2113…
$TCGX bought a ton around 10$. AI says trust is ~10.07 so you make T-Bill +50 bps in a couple months and have a free call option on the deal receiving actual interest before closing.
I´m 90% sure we just saw someone from the IPO participate in the PIPE, sell their shares and taking some free money off the table.
Literally 0 reason to not be long this (sub trust) imo
9) $AMAN super safe SPAC with NAV today at ~ 10.17$/share. Merging with Corxel, RTW incubated chinese oral small molecule GLP1 thingy. Super cheap compared to peers, Phase 3 ongoing.
Don´t think this is a super differentiated asset, but wow is it cheap. Buy around SPAC NAV, get free upside.
8) $BOLD super cheap $BEAM copycat. Might have legal issues, but there is a large dividend (probably 2$ish). 2.45$ is probably a 20-50% discount (depening on size of special div) to the concurrent PIPE which happens at what I think is a cheap valuation to begin with. Data so far are looking strong to an idiot like me. AATD gene editing thingy.
A lot going on but I like it, price compensates for risk imo.
7) $INM I´m long but ran too far for now, was a buyer below 1.4$, saving my breath for now
6) $HOWL late stage, somewhat interesting CVR. The stock held up very strongly through recent biotech drawdown. Historical data are somewhat wonky, but tea leaves are strong. If you can snatch it up below 1$, I think the r/r is favorable.
5) $AEMD tricky one. Very hard to say how much net cash they bring so hard to say where the PIPE happens, can be anywhere from 4-6$ (excess cash will be paid via CVR but I included that here).
They are actually screwing shareholders a bit I think because they are including ITM Warrants in the sharecount but are not including the associated cash in the net cash calculation. Hope someone revolts and that changes, would be a huge bump.
Other than that, you know I´m a huge ADAR1 fanboy. His contribution to my wealth is almost ridiculous. It´s the first company he brings public out of the fund (I think?) so I tend to think he wants that to succeed very badly and chose the one where he thinks PoS is very high. "Earth shattering" were his words.
Hard to overstate how pumped I am. HUGE TAM, MoA makes sense from what I can tell (reminder that I probably don´t even know what a protein is), multiple times oversubscribed from what I heard.
There is a CVR involved, but don´t care too much other than possible cash from warrant exercises if that happens.
4) $RLYB the special div estimate came in a tiny smidge below my estimate (I was right on $ / lazy on ITM option treatment)
Other than that, I think the downside at/around 16 is very negligible with decent upside.
teapawt.net/AnotherBio/status/2087…
23/x Bonus for folks reading to the end highest conviction idea is currently R L Y B , I´m in below 16 but i still think it works from mid 16s, risk is very low as you´ll get majority of today´s price in dividends and then have an interesting stub. Stuff like yarw and nxtc trades like 3-5 times stub value
3) $LSTA Merging with Marea (acromegaly thingy). There is one interesting and big clue: Marea also tried to merge with FULC (this is very clear from prospectus, ask a LLM) where Marea itself wanted to return ALL Fulc cash. Meaning the investors in Marea want as much as possible for themselves. I´ve found over the years that divying out the cash of the shell is a very positive indicator for performance (makes total sense if you think through that).
Since LSTA doesn´t bring any net cash, folks don´t see that strong signal for the stock on paper - but it is there! Compared to the FULC proposal, Marea increased the PIPE from 200 to 225 with a lower valuation (350 mln$ vs 375) but it´s hard to say where they would´ve landed at a final valuation.
The 225mln$ PIPE happens at ~1.49$ / share (calculated for LSTA) -> large discount at 1-1.10$
