

🇻🇦| Applied Mathematics | MFT | Aspiring QR
Joined October 2025
- Tweets232
- Following200
- Followers921
- Likes4.3K






Putting together a small group of independent street kwants focused on systematic trading (Low-Freq/MFT).
Mainly looking for people who have been researching quant trading for a while and are already running live systems/portfolios.
The idea is to exchange research, discuss alpha/features ideas, infra, execution, and generally help each other learn and improve.
If you think you'd be a good fit, feel free to DM for an invite.
Was playing around with IC gates and negation of features when IC turns negative and it clicked why it makes more sense to model features as expected returns.
Digging now into some factor modeling to know what the features i've built hitherto are really doing, found this article quite useful to start with
papers.ssrn.com/sol3/papers.…


@pedma7 is my great friend and we learned trading over roughly the same period. Lots of collaboration over many trades
Fucking around, finding out, asking smart frens, doing the work
It is still surprising to me that people at the very highest levels of finance will help me learn more and improve my systems
Trying to copy @therobotjames ...
Some useful intuition built while digging deeper into feature research

Making a lot of refinements to feature research.
Tails indeed noisy as fuck.
Thanks @friendscallmeap

Simple returns or vol-adjusted returns? @ScottPh77711570
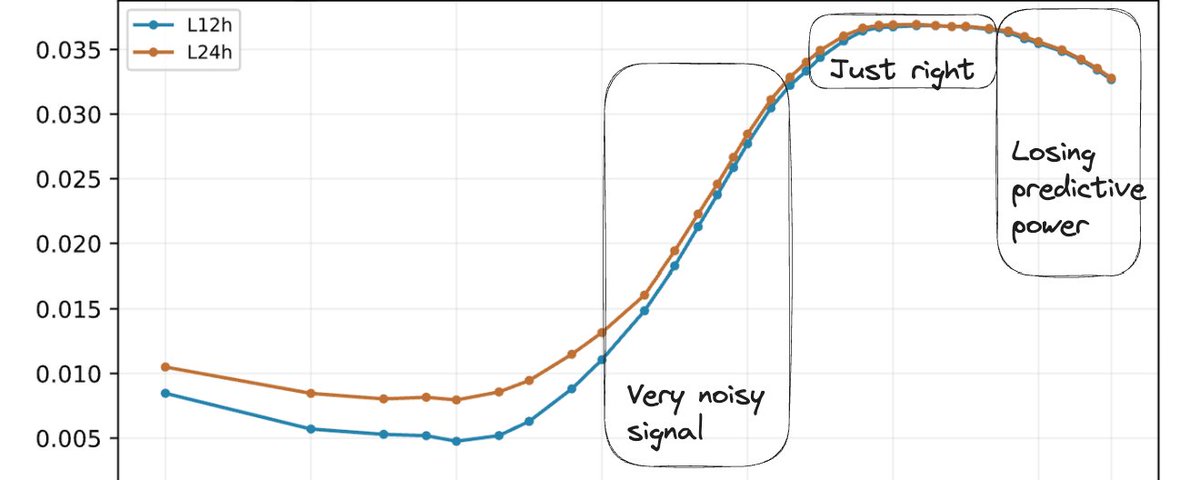
how do you approach the lookback and the forward horizon if we model intraday?
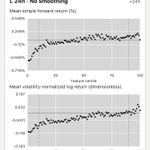
here for example is a feature with a 24 hour lookback plotted against 24 hour forward returns


Are you telling me @OpenAI needs more compute?
This is with 20x pro plan on 5.6 Sol Max btw
