

Bloomberg terminal? Brother, I got a cracked iPhone, a nicotine addiction, and the gift of prophecy.
Behind The Counter
Joined October 2026
- Tweets153
- Following36
- Followers72
- Likes244

$MO Up 4.45% today, Altria delivered another solid quarter, reinforcing my bullish outlook on the company as a defensive, income generating investment.
Q3 2026 Highlights:
Revenue: $6.13B (+1.0% YoY)
Revenue excluding excise taxes: $5.44B (+3.6% YoY), beating expectations of ~$5.31B
Adjusted EPS: $1.52 vs. $1.51 expected (+4.8% YoY)
FY2026 EPS guidance raised to $5.66–$5.74
Additional $1B authorized for share repurchases
Quarterly dividend increased 4.7% in August
What particularly interests me is Altria's pricing power. Despite declining cigarette volumes, the company continues to defend profitability through pricing, brand strength, and disciplined capital allocation.
The expansion of its on! PLUS nicotine portfolio also provides a potential longer term growth opportunity as consumer preferences shift toward smoke free alternatives.
With substantial cash generation, consistent dividend growth, and relatively defensive demand characteristics, I continue to view $MO favorably, particularly in an environment of persistent inflation and macroeconomic uncertainty.
The long term investment thesis remains intact.
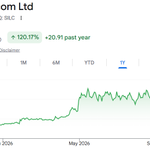
Despite beating both revenue and EPS expectations, SILC is down following earnings. I continue to view the company favorably as a long term investment.
Q3 revenue increased 71% YoY to $26.7M, while non-GAAP EPS reached $0.04 versus expectations of a $0.04 loss. Management also raised FY2026 revenue guidance again to $96–98M.
Modest gross margin compression, and Q4 guidance implying relatively limited sequential growth. That said I view these earnings as a good result, valuation may have ran ahead of its self a bit.
The numbers show that the long term thesis remains intact: accelerating revenue, expanding customer relationships, and new design wins provide a credible pathway toward sustained profitability and operating leverage. Remember this is the first time they have posted positive EPS.
Volatility is not the same as fundamental deterioration. I'm maintaining my long term bullish outlook, I view today as a buying opportunity.
$SILC
FormFactor delivered another impressive quarter, beating both revenue and EPS expectations.
Revenue reached $280.5M (+38.4% YoY), while adjusted EPS of $1.04 beat consensus by nearly 21%. Non-GAAP gross margins expanded to 56.5%, reflecting improving product mix and operating leverage.
Most notably, Systems revenue grew over 20% QoQ, supported by accelerating CPO demand, while Foundry & Logic revenue increased 10% sequentially.
Q4 revenue guidance of $275–295M reinforces continued demand strength, although capacity constraints warrant monitoring.
I expect the stock to accelerate in the upcoming days.
$FORM
This was a major design win for $SILC, and a great example of why they make for an amazing investment. They have growing exposure to AI infra, but for those of you who have noticed the booming business of $CRWD, $PANW, $NET they have exposure there as well. Tomorrow is a big day, earnings.
I am watching for revenue above $26M, a return to non-GAAP profitability, and an upward revision to FY2026 guidance. More importantly, the conversion of AI inference design wins into volume production orders could signal a meaningful revenue inflection heading into 2027.
With operating leverage improving and AI related deployments scaling, even modest upside surprises could materially alter forward earnings expectations, but we need to see deployment of these designs, not just talk.
I maintain maintaining our long term conviction while watching closely for a potential post earnings repricing. I hold this as a long, not a trade.

$SILC just booked its eighth Design Win of 2026 at September 2.
Eight was the full year total for 2025.
The specifics:
- New customer, tier-1 cloud based cyber security
- 5G integrated Edge Networking device
- Over $5M per year at full ramp, this device alone
- Initial order already placed, ramp beginning before year end
That last line is the one that matters. Most Design Wins in this
business convert over years, which is why the counter is a pipeline
metric and not a revenue metric. This one ramps inside the guidance
period.
A second device is in evaluation with the same customer, a GPU integrated Edge unit for AI inference. Unpriced, uncommitted, and not in any model.
"more optimistic than ever about our continued growth in 2027 and beyond"
- Liron Eizenman, CEO, September 2 2026
Management optimism is worth exactly what the track record says it is.
July 2025, this CEO promised double digit growth for 2026. FY26 now
guides to $93-95M against $61.9M, over 50%. Q4 2025 guided $15-16M and
printed $16.9M. Q2 2026 guided $20-21M and printed $23.8M.
Every number he has set, he has cleared.
A ninth win would take the year past the top of the target range with
a quarter still to run. But win count measures sales execution, not economics. What settles this is the Q3 print against the $25-26M guide
and whether the H2 non-GAAP crossover actually lands.

$FORM Short Term Bullish Earnings Trade Alert
I am extremely bullish ahead of FormFactor's earnings today, expecting a large beat.
FORM has beaten EPS expectations in four consecutive quarters. Over the past year, revenue expanded 30%+, non-GAAP gross margins improved 1,500bps, and EPS tripled, demonstrating substantial operating leverage.
HBM related DRAM probe card demand remains robust, while the Triton CPO testing platform is gaining traction as optical interconnect integration increases testing complexity. This strengthens FORM's exposure to advanced packaging and high performance compute.
With consensus near $0.86 EPS and $270M revenue, we believe the market may be underestimating incremental margin expansion and forward guidance.
Short term bullish on $FORM, particularly if Systems growth and HBM demand support another upward earnings revision. Elevated expectations and earnings volatility remain key risks.
They have had positive market reactions the following day after each of the last four earnings releases, this is exciting.
$VIAV, VIAVI Solutions, New Long Idea
I am initiating a bullish view on VIAVI Solutions following a substantial correction in its share price.
VIAV has declined approximately 47.2% from its April 30 peak of $60.43 to $31.88 as of October 26. I believe this correction has created an attractive opportunity to establish a long term position in a company with increasingly important exposure to hyperscale AI infrastructure, optical networking, and semiconductor interconnect technologies.
Investment Thesis
VIAVI specializes in network testing, optical measurement, and validation technologies. Its products help semiconductor manufacturers, optical component suppliers, and network equipment providers ensure that increasingly sophisticated communications infrastructure operates reliably.
As hyperscalers transition from 400G and 800G networking toward 1.6T and eventually 3.2T architectures, maintaining signal integrity becomes substantially more challenging.
Higher transmission speeds introduce additional complications involving bit error rates, jitter, crosstalk, optical attenuation, and thermal stability.
These challenges are especially consequential in AI data centers, where network inefficiencies can reduce GPU utilization and undermine the economics of extraordinarily expensive computing infrastructure.
VIAVI provides the testing and measurement infrastructure needed to identify and resolve these problems.
Technological Positioning
One of VIAVI's most compelling characteristics is its exposure to multiple competing networking architectures.
Its ONE 1600 platform supports next-generation 1.6T Ethernet validation, while its TestCenter D2 solutions provide high speed network testing capabilities, including Ultra Ethernet Transport validation.
Meanwhile, the company's MAP 300 platform addresses increasingly sophisticated optical manufacturing requirements associated with silicon photonics and co-packaged optics (CPO).
I consider this technological diversification particularly attractive.
Whether hyperscalers ultimately favor conventional pluggable transceivers, co-packaged optics, or hybrid configurations, increasingly demanding validation requirements should support demand for sophisticated testing equipment.
VIAVI does not need to manufacture the winning optical transceiver or networking ASIC to benefit from the industry's expansion.
Financial Performance
The company's recent operating performance supports the underlying investment thesis.
Fiscal Q4 2026:
• Revenue: $443.1M (+52.5% YoY)
• GAAP operating margin: 13.8%
• Adjusted operating margin: 24.0%
• Adjusted EPS: $0.34 (+161.5% YoY)
For fiscal 2026, revenue increased 40.0% to approximately $1.52B.
Its Network and Service Enablement segment generated approximately $1.18B in annual revenue, representing 52.3% growth.
Importantly, acquisitions contributed to this expansion, meaning reported growth should not be interpreted as entirely organic.
Nevertheless, the combination of revenue expansion and improving profitability suggests considerable operating leverage.
Management has guided fiscal Q1 2027 revenue to 450M–460M, alongside adjusted EPS of 0.40–0.42.
Valuation and Long-Term Outlook
Following its approximately 47% correction, VIAVI offers a meaningfully different valuation proposition than it did at its April highs.
The business is not inexpensive relative to trailing GAAP profitability, and continued execution will be necessary to justify its valuation.
However, I believe the combination of structural demand growth, technological diversification, and improving operating margins creates an attractive longer-term opportunity.
There are legitimate risks, including hyperscaler capital expenditure reductions, delayed adoption of next-generation optical networking, competitive pricing pressure, and acquisition integration challenges.
The upcoming November 4 earnings release will be an important test of whether the company's operational momentum remains intact.
Conclusion
My bullish outlook is based on the expectation that testing and validation requirements will become increasingly demanding as AI infrastructure continues scaling.
While substantial investor attention remains concentrated on GPUs, optical transceivers, and networking silicon, the equipment required to validate these technologies represents another important component of the AI infrastructure ecosystem.
I believe VIAVI is exceptionally well positioned to benefit from this development.
At current valuations, I view the recent correction as an attractive accumulation opportunity, particularly for investors operating with a 12–24 month investment horizon.
Disclosure: I have held a position in $VIAV since before the launch of Smoke Shop Finance. This is an existing investment, not a newly initiated position.


$SILC, An Overlooked AI Infrastructure Earnings Inflection?
We've been examining Silicom ($SILC), a ~$220M microcap providing specialized networking hardware, SmartNICs, FPGA adapters, cybersecurity infrastructure, and emerging AI inference solutions.
What initially caught our attention wasn't the business. It was the extremely unusual relative price performance.
Since May 20:
$SILC: −7.9%
$CRDO: −19.5%
$AEHR: −32.8%
$IREN: −52.7%
$AAOI: −59.2%
$POET: −63.1%
$NVTS: −63.5%
Despite October's substantial AI infrastructure correction, SILC has retained considerably more of its value than many peers. This is especially interesting given its extremely small market capitalization and limited liquidity.
The fundamentals may explain part of this divergence.
Quarterly revenue has progressed from $15.6M to $16.9M, $19.1M and $23.8M. Q2 revenue increased 59% YoY, while GAAP net losses narrowed to $2.1M.
Management now projects $93–95M in FY2026 revenue, has secured multiple material design wins, and expects to return to quarterly non-GAAP profitability during the second half.
The valuation is also unusual: approximately 1.8x forward EV/revenue, with roughly $55M in cash and marketable securities and no conventional financial debt.
The ownership structure is arguably just as interesting.
Portolan Capital disclosed a 5.06% ownership position in September. Meanwhile, reported short interest stood at approximately 3% of float, puny for a speculative microcap.
The next catalyst is October 29 earnings.
We're watching revenue acceleration, GAAP operating leverage, inventory conversion, cash flow, and whether emerging AI inference design wins translate into meaningful 2027 production revenue.
Risks remain substantial. SILC is small, highly speculative, illiquid, currently GAAP loss making, and carrying unusually elevated inventory. Its AI opportunity is still early stage.
Nevertheless, the combination of relative price resilience, institutional interest, modest valuation, and accelerating fundamentals is difficult to ignore.
We believe $SILC warrants serious consideration as a speculative earnings recovery opportunity, not simply another AI infrastructure momentum trade.
TLDR This is risky, but the price action is so incredibly weird, a company this small in ai infra should be beaten into the floor, but instead its been virtually flat since may.
Disclosure: I have held a position in $SILC since before the launch of Smoke Shop Finance. This is an existing investment, not a newly initiated position.

SMOKE SHOP FINANCE
$MO Altria Group | LONG TERM BUY, likely set to outperform into 2027
With increasing uncertainty surrounding technology valuations, persistent inflationary pressures, and elevated Treasury yields, I believe Altria Group offers an attractive opportunity for investors seeking defensive exposure, consistent income, and moderate earnings growth.
Dividend Yield & Shareholder Returns
At $74.09 per share, Altria offers an annualized dividend yield of approximately 6.0%, supported by a quarterly distribution of $1.11 per share.
The company has increased its dividend 61 times over the past 57 years, demonstrating a longstanding commitment to shareholder returns.
Unlike many high growth equities that are currently popular on X, a substantial portion of Altria's investment proposition comes from recurring cash distributions rather than expectations of future multiple expansion.
Earnings Growth & Valuation
Despite declining cigarette consumption, Altria continues to generate earnings growth through pricing power, operational efficiency, and share repurchases.
Adjusted EPS increased 4.4% in 2025. Management currently projects 2026 adjusted EPS of 5.61–5.72, representing growth of 3.5%–5.5%.
At approximately 13.1x forward adjusted earnings, the valuation remains attractive for a mature business generating substantial cash flow and returning capital consistently.
Defensive Characteristics
Tobacco consumption has historically demonstrated relatively low sensitivity to economic cycles, with established consumer habits supporting recurring demand.
During the inflationary bear market of 2022, Altria generated approximately 4.4% in total shareholder returns, including reinvested dividends, compared with an 18.1% decline in the S&P 500.
This illustrates the defensive characteristics of its business model during periods of market stress.
Investment Outlook
Regulatory exposure, declining cigarette volumes, and competition from alternative nicotine products remain material risks.
Nevertheless, Altria's pricing power, recurring cash generation, and substantial dividend provide a compelling foundation for long term total returns.
I view $MO as an attractive defensive holding, particularly for investors seeking portfolio income and reduced dependence on technology sector valuations.
Rating: LONG TERM BUY
— Smoke Shop Finance 🚬
Wall Street has officially run out of people I respect.
I will now be conducting equity research from a smoke shop in Los Angeles.
Our Bloomberg terminal is a stolen calculator.
Our investment committee is me.
Our compliance department is currently serving 6 to 8 years.
$MO dividends got me feelin' bullish.
Welcome to Smoke Shop Finance. 🚬