

Deep thinker who views the market as a mirror of human nature. Just sharing reflections, not a CONTENT CREATOR :)
Joined August 2009
- Tweets2.4K
- Following849
- Followers811
- Likes3.2K




$Corning just reported explosive Q3 2026 earnings that blew past market expectations, powered by a staggering 44% surge in its Optical Communications division, with pure-play Generative AI product sales doubling (+100%) year-over-year.
Proxy Examples: Sterlite Technologies (STL), Polycab India, Apar Industries
#StocksToWatch
Reliance Industries shares (currently around ₹1,200) are heavily expected to see structural re-rating as value unlocks from Jio's independent listing (If)😀
Out of the ₹30,213 crore raised, Jio is putting ₹27,500 crore straight toward clearing its telecom debt. This radically cleans up their balance sheet instantly.
Keep this in mind 😀

Jio Platforms IPO is locking in for a historic debut tomorrow! 🚀
With the upper band set at ₹1,119 and GMP hovering around +₹245, the street is looking at a highly realistic opening between ₹1,350–₹1,380.
If pre-open institutional demand spikes, a ₹1,400+ listing is well within reach (~25% premium). Instantly places Jio as India's second-most valuable listed entity.
Absolute blockbuster value unlocking for RIL. 🔥
#JioPlatforms #IPO #StockMarketIndia #RIL
Q2 FY27: My PEAD Watchlist 🔍
Looking beyond headline beats to earnings acceleration, operating leverage and the next leg of growth.
🔹 MOREPEN LABS — Revenue +81%, PAT +117%. CDMO contribution rising; cash conversion is the next test.
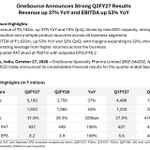
🔹 ONESOURCE SPECIALTY PHARMA — Revenue +37%, EBITDA +53%, adjusted PAT +109%. Capacity ramp-up could sustain growth.
🔹 ACUTAAS CHEMICALS — Revenue +43%, EBITDA +85%, PAT +73%. FY27 guidance raised; ₹2,000 Cr CDMO ambition by FY30 adds a longer runway.
🔹 IGI — Revenue +31%, PAT +43%. High margins and earnings growth, but valuation matters after the rally.
🔹 SONA BLW — Revenue +35%, EV revenue +129%. Multiple growth engines are firing, while margin pressure and premium valuation need monitoring.
The common thread? Earnings acceleration is real. The challenge is buying before the market fully prices it in.
My next step: reverse valuation, define starter and add zones, and identify what would invalidate each thesis.
No chasing green candles. No dismissing great businesses just because the first move happened without us.
#PEAD #IndianStocks #EarningsGrowth #Investing
Comparing your portfolio to screenshots on X
is a great way to FOMO into a cyclical top, ruin your sleep, and lose money based on someone else's risk tolerance.
Run your own race. Or don't, and enjoy the expensive lesson.

SONA BLW: Growth is accelerating. The next question is valuation.
Our Q2 FY27 study:
🔹 Revenue: ₹1,546 Cr (+35% YoY)
🔹 EBITDA: ₹356 Cr (+23% YoY)
🔹 PAT: ₹223 Cr (+29% YoY)
🔹 EV revenue: +129% YoY
🔹 Order book: ₹25,100 Cr, up from ₹24,000 Cr in Q1
🔹 EBITDA margin: ~23%, under pressure from input costs and product mix.
Three growth engines are gaining traction:
• Differential assemblies recovering
• Traction motors scaling across 2W/3W EVs
• Suspension motors ramping up in China
New programmes and potential Physical AI applications add to the longer-term opportunity.
The trade-off: JPMorgan estimates ~23% FY26–29 EPS CAGR, but the stock trades around 47× FY28 earnings.
Our valuation framework:
₹700 — potential starter zone
₹600 — potential add-on zone
These levels depend on the growth thesis and earnings outlook remaining intact.
A strong business doesn't automatically mean an attractive entry.
The opportunity is to buy growth at a price that leaves room for returns.
#SonaBLW #AutoComponents #EV #IndianStocks
$TANLA PLATFORMS: Good growth.
But is AI monetising yet?
Q2 FY27 results are in.
📈 Revenue: ₹1,352 Cr (+25% YoY, +10% QoQ)
📈 Operating profit: ₹214 Cr (+21% YoY)
📈 PAT: ₹146 Cr (+17% YoY)
⚠️ Operating margin: 15.86%, down 60 bps YoY
⚠️ PAT grew just 3% QoQ.
The business is growing, but profits aren't keeping pace with revenue. Margin compression deserves attention.
My original thesis remains: Tanla could benefit as enterprise communications evolve towards conversational and agentic AI. But AI opportunity is not the same as AI monetisation.
What I want to see next:
1️⃣ Digital Platforms growth
2️⃣ Evidence of AI-led revenue contribution
3️⃣ Margin stabilisation
4️⃣ Strong cash conversion
At ~14.5x P/E, valuation deserves a closer look—but cheap multiples alone don't make a buy.
Verdict: Results are constructive, not a blowout. Thesis alive; monetisation still needs proof.
Studying the setup. Not buying the AI label. Tracking the earnings.
$TANLA #IndianStocks #AI #AgenticAI #PEAD
#tanla Platforms: Agentic AI — opportunity or just a narrative?
Tanla isn't a direct AI-compute play. Its opportunity lies one layer higher: enterprise communications, conversational AI, messaging APIs and digital trust.
As AI agents multiply, they may need secure, reliable channels to communicate, authenticate and serve customers.
The thesis is plausible. Monetisation is the test.
Q1 FY27 showed:
• Revenue +17.8% YoY
• EBITDA +22.7%
• PAT +20.1%
• FCF ₹126 Cr
But here's the catch: Digital Platforms grew only 12.2% YoY. We still need evidence that AI-led products are becoming a meaningful growth engine.
With Q2 results due tomorrow, I'm watching:
1️⃣ Digital Platforms growth
2️⃣ AI product monetisation
3️⃣ Margins and cash conversion
4️⃣ Management's growth outlook
My takeaway: Don't buy the AI label. Track the earnings.
Studying the setup—not a buy recommendation. $TANLA #IndianStocks #AI #AgenticAI #PEAD
Early Q2FY27 numbers are an absolute blockbuster! 🔥
Out of ~300 results:
• Median Revenue: +21%
• Median PAT: +30.5%
When earnings growth outpaces top-line by nearly 1,000 bps, operating leverage is firing on all cylinders. Corporate India is converting efficiency straight to the bottom line. 🚀
#EarningsSeason #Nifty #StockMarket

📡 ASTRA MICROWAVE vs 🔌 APOLLO MICRO SYSTEMS
Two different ways to participate in India’s ₹2.12 lakh crore defence procurement opportunity. 🧵
1/4 | The technology edge 🧠
📡 Astra Microwave ($ASTRAMICRO): Specialised RF, microwave, radar and space electronics—technology-intensive systems where design expertise and qualification matter.
🔌 Apollo Micro Systems (solana:CLd4sKq53pWpjqwaUG3EBnqFMf8242GnZqvPyyqepump): Defence electronics, embedded systems and weapon-system integration, with ambitions to move further up the defence value chain.
Different capabilities. Different execution risks.
2/4 | The earnings reality 📊
Apollo’s Q2 FY27 consolidated revenue rose 72.3% YoY to ₹388.15 Cr, while PAT increased 53.7% to ₹46.15 Cr.
Astra’s Q2 needs a closer look at year-on-year growth, margins and order execution—not just its technology credentials.
For both companies, large order books matter only when orders convert into revenue, profits and cash.
3/4 | Valuation is where the debate gets interesting 💰
Both operate in a project-driven industry, where execution timing and working capital can make quarterly results lumpy.
The questions investors should ask:
• What growth is already priced in?
• Are receivables and inventory under control?
• Can earnings grow fast enough to justify the valuation?
• Is the order pipeline translating into cash generation?
A great technology business can still be a poor investment at the wrong price.
4/4 | Two different investment cases 🎯
📡 Astra: Examine its specialised technology, order conversion and margin trajectory.
🔌 Apollo: Examine its recent earnings momentum, execution capacity and the valuation required to sustain that growth.
Neither is automatically the safer choice. Neither is automatically the better buy.
The real comparison isn't just Astra vs Apollo. It's future earnings growth vs the price we pay today.
Which deserves deeper research—and what evidence would convince you?
#AstraMicrowave #ApolloMicroSystems #DefenceStocks #IndianStockMarket
WEAK

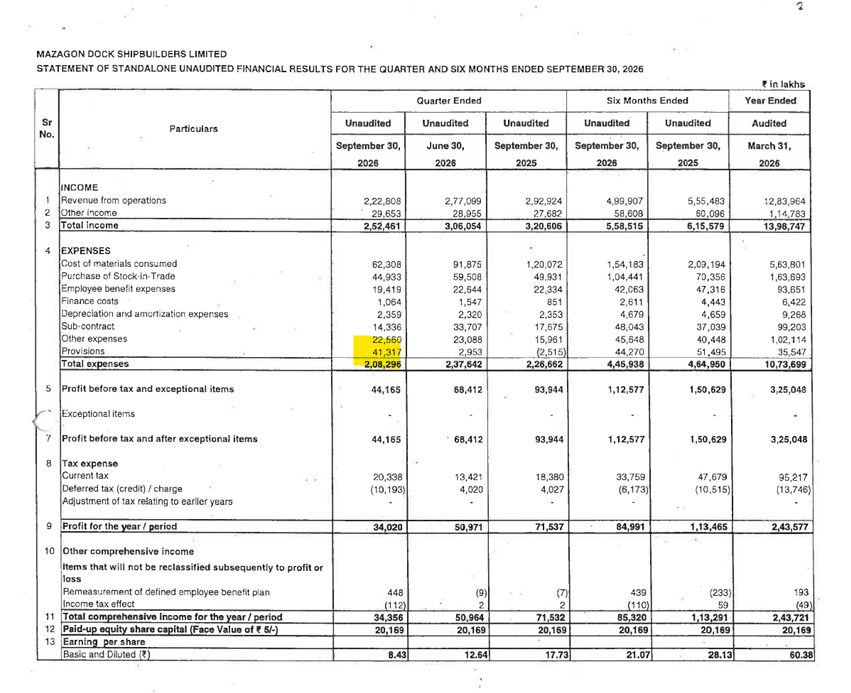
#2QWithCNBCTV18 | #MazagonDockShip reports its Q2 results;
⏩Revenue Down 16.5% At ₹2,446 Cr Vs ₹2,929 Cr (YoY)
⏩Net Profit Down 54.1% At ₹344 Cr Vs ₹749 Cr (YoY)
⏩EBITDA Down 71.3% At ₹199 Cr Vs ₹694 Cr (YoY)
⏩EBITDA Margin Down 1,560 Bps At 8.1% Vs 23.7% (YoY)

It proves why backing flexible electronic sub-system proxies ..like #DataPatterns or Astra is far safer than catching heavy platform integration knives when execution schedules get delayed.
Mazagon Dock Shipbuilders Limited #mazdock has reported a highly compressed, operationally weak set of Q2 FY27 results
#Q2FY2027 #StocksToWatch
🚨 MOREPEN LABS: The results beat the target.🔥
Now the real story begins. 🚀
Before the results, I was looking for ₹600–700 Cr in revenue. Morepen delivered ₹746.50 Cr! 👀
📊 Q2 FY27 highlights:
💰 Revenue: ₹746.50 Cr | +81.1% YoY
🔥 PAT: ₹88.89 Cr | +117.5% YoY
⚡ EBITDA: ₹121.94 Cr
📈 EBITDA margin: 16.33% vs 7.5% a year ago
💥 EPS: ₹1.62
The standout isn't revenue growth alone. The sharp expansion in EBITDA margin suggests operating leverage is kicking in.
My CDMO/API thesis is gaining support—but the next test is whether this performance can be repeated.
🔍 I'm watching three things next:
• CDMO revenue ramp-up and order execution
• Sustainability of EBITDA margins
• Operating cash flow and working-capital discipline
One strong quarter gets attention.
Consistent earnings and cash generation build a lasting re-rating case.
Is Morepen entering a new phase of growth?
The next few quarters will tell us. 👀
#MorepenLabs #CDMO #PharmaStocks #EarningsGrowth #IndianStockMarket
#MorepenLab Q2 FY27 — What I'm expecting 🔍
Expecting revenue to comfortably cross ₹600 Cr, with upside towards ₹700 Cr if the projected ₹225 Cr CDMO supplies translate into recognised revenue and the base business holds up.
If the 15% EBITDA margin sustains, ₹600 Cr revenue implies ~₹90 Cr EBITDA.
That would strengthen the structural profitability improvement and re-rating thesis.
But dispatches, revenue recognition, margins and cash conversion matter. One quarter alone cannot prove a structural change.
Results first. Conclusions after.
#MorepenLabs #CDMO
Blew up my baseline targets 😀
Q2 FY27 print from Sky Gold & Diamonds! 🚀 Profitability is massively outrunning revenue growth.
The Reported Reality:
💰 Revenue: ₹2,391 Cr (+61% YoY | +19% QoQ)
🔥 Net Profit (PAT): ₹128.5 Cr (+91% YoY | +22.5% QoQ)
📈 EPS: ₹8.26 vs ₹4.37 YoY
📐 EBITDA Margins: Expanded to 7.9% (up from 6.6% YoY)
The Big Positives:
Operational shift into high-margin studded/diamond jewelry and exports is effectively buffering raw gold price volatility.
FY27 revenue guidance of ₹8,100 Cr remains firmly on track, with H1 already cruising past the ₹4,400 Cr mark ahead of the Q3 festive tailwinds.
What to verify in the full statement:
Working Capital: Are receivable days compressing down toward the 50-day target to ensure high free cash flow conversion?
Fund-Raise Scale: The exact equity dilution terms for the upcoming capital raise to fund their manufacturing expansion.
Cyber-fraud: Final updates on the ₹10.7 Cr coercion incident at the Starmangalsutra subsidiary.
Verdict: A phenomenal structural earnings beat. At a 43x trailing run-rate P/E, it commands a premium, but a PEG ratio well under 0.5x makes it one of the absolute strongest fundamental profiles in the consumption space. 📈💎
#StockMarketIndia #SkyGold #GoldPrice #Investing
🔍 Sky Gold & Diamonds: Q2 FY27 — What I’m Watching
Tomorrow’s results are more than a revenue-growth story.
📊 Revenue: Can growth sustain?
📈 EBITDA margin: Can it hold near 7.8%?
💰 PAT: Can it exceed Q1’s ₹104.9 Cr?
🏦 Cash flow: Is growth translating into cash?
📉 Debt: Are we seeing meaningful reduction?
🎯 FY27 guidance: ₹8,100 Cr — maintained or upgraded?
Also watching the proposed fund-raise, potential dilution and the cyber-fraud disclosure.
The real test: profitable growth, cash generation and balance-sheet improvement.
Note: Study purpose
#SkyGold #Q2Results #IndianStocks #Earnings
A 4% green day after a 30% crash is a "Dead Cat Bounce" or a technical oversold relief rally????
Everyone talking about PF moving up including me😀
A "Strong Reversal" is a structural change in trend—where the stock breaks past heavy resistance levels, makes consecutive higher highs, hits fresh 52-week highs, and completely leaves the benchmark index behind.
#StockMarket #nifty #sensex