

VP of Product & Engineering @xMoney_com | Building secure, scalable systems for a next-gen digital payment network
Cluj-Napoca
Joined June 2012
- Tweets500
- Following370
- Followers648
- Likes895



If you already speak with merchants, SaaS founders, agencies, or business owners who need a cleaner way to accept card payments, this is worth looking at.
xMoney’s partner program turns relevant introductions into recurring commission.
Simple idea: help businesses improve payment acceptance, and let your network become a revenue channel.

You already know business owners, and some of them need better ways to accept payments 💸
Now, that connection can pay you back.
Refer merchants to xMoney's card payment platform and earn recurring commission, month after month.
No joining fee; just a smarter way to put your network to work.
partners.xmoney.com


Most checkout pages force the brand to adapt to the payment provider.
That is backwards.
If the payment moment is part of the customer experience, it should feel native to the merchant: theme, typography, colors, field states, wallets, CTA, and flow.
This demo shows how configurable xMoney checkout can get.
Payment UI that adapts to your brand, not the other way around 🫡
Explore light, dark, and custom themes; typography and color variables; field states; selector-level rules; wallet appearance; custom CTAs; and two completely different branded checkout stories.
Start here: demo.xmoney.com/payment-form…

The best payment integrations don’t just work for developers, they get out of the way.
Native SDKs make implementation faster, but the bigger opportunity is giving product and design teams the room to shape the payment experience around their own customer journey.
Explore the improved demo: demo.xmoney.com
Our demo platform has a refreshed look and expanded functionality.
Run checkout flows, change the configuration, watch SDK events, and open the client and server code, all in our updated interactive showroom for xMoney Checkout SDK.
See for yourself 👇
xmoney.com/blog/checkout-sdk…

Beni Cosma retweeted

A quick reminder about something pretty big we shipped last week 👀
xMoney’s native payment SDKs are now live for iOS, Android and React Native.
And yes, this puts us among the first payment providers in Romania to offer a fully native mobile checkout, and among a small group doing it across Europe 🫡

Beni Cosma retweeted
Native checkout, built for every mobile stack 🙌
xMoney SDKs are LIVE for iOS, Android, and React Native:
→ Payment Sheet: drop-in checkout
→ Payment Element: payments in your own layout
→ Apple Pay & Google Pay
Cards, saved cards, and 3DS handled inside the SDK.
xmoney.com/blog/xmoney-payme…

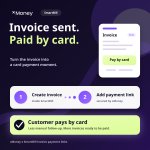
A lot of payment friction starts after the invoice is created.
The customer receives the invoice, leaves the flow, opens banking, enters details manually, and pays later.
This SmartBill integration closes that gap inside xMoney:
invoice creation, card payment link, and recurring billing in one workflow.
The invoice hasn't changed. But the way it's paid has.
xMoney now integrates with SmartBill, allowing businesses to generate invoices directly from the xMoney dashboard and attach a payment link so customers can pay instantly by card.
Recurring invoices?
Also built in ✅
One integration, same workflow.
And a much better payment experience.

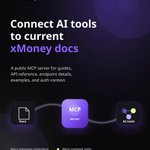
We added an easy guide for connecting xMoney docs to AI coding tools through MCP:
docs.xmoney.com/guides/gener…
Supported assistants can search xMoney guides, inspect API endpoints, check auth requirements, and pull examples while you build.

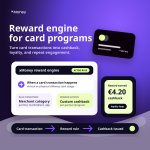
A card program should not stop at issuing the card.
The real commercial layer is the reward engine behind it.
With @xMoney_com, platforms can design cashback and reward logic around the behaviors they want to grow: usage, retention, loyalty, and repeat engagement.

Great to see this live.
Card issuing has many moving parts, from onboarding and KYC/KYB to funding, cards, transactions, and 3DS.
Clear documentation makes it easier for platforms to understand what they can build with xMoney.
New xMoney Card Issuing docs are live!
For partners building white-label card programs, issuing is not just creating a card.
The full flow matters and we mapped the integration path here: docs.xmoney.com/guides/card-…

Not every payment flow should charge immediately.
Some businesses need to authorize first, then capture later when the order is confirmed, fulfilled, or adjusted.
That is why payment infrastructure should support more than a basic checkout button.
Checkout starts the flow.
Payment logic has to fit the business.

A checkout integration should not force every merchant into the same payment form.
Some teams need a fast default setup.
Others need control over layout, fields, payment options, and how the form behaves inside their product.
The best payment infrastructure gives developers flexibility without making checkout harder to maintain.
That is the balance xMoney is building toward.

Most platforms think about cards as a finance feature.
I think they are more interesting as a product surface.
A branded card can connect:
- payouts
- expenses
- loyalty
- wallet use
- everyday spending
The point is not the logo on the card.
The point is where the platform relationship continues when money moves.

Funding investment accounts should not force platforms to choose between speed and compliance.
That is exactly why Verified Card Funding matters.
Users can top up by card instantly, while ownership is checked with the issuer before funds move.
Fast UX. Stronger controls. Already live.
For regulated platforms, funding an account has always meant a trade-off: fast or compliant.
Not anymore, because we’re launching a new feature!
xMoney's Verified Card Funding lets users top up investment accounts instantly by card, while confirming ownership directly with the card issuer, before any money moves.
No slow bank transfers. No compromise.
Already live in production, with Tradeville as the first platform using it 🔥

Marketplaces need more than a checkout button.
They need split payment flows that feel simple for the buyer and clear for every reseller behind the transaction.
Buyer checkout should be smooth. Payment status should be visible. Refunds should be traceable. Reseller settlement should be understandable. Reconciliation should not become manual detective work.
The hard part is not only accepting the payment.
It is making the whole flow work from checkout to settlement.

Recurring billing is not only about charging a card every month.
It is the operating layer around repeat revenue:
- subscription changes
- saved payment methods
- failed payment retries
- invoice history
- customer support
- reconciliation
If that layer is messy, revenue feels harder than it should.

For the technical side, xMoney docs cover recurring payments and saved-card flows here:
docs.xmoney.com/guides/payme…
docs.xmoney.com/guides/payme…
Important update from xMoney on EURXM, USDXM and RONXM.
The product and infrastructure are ready. The remaining step is regulatory: the national framework for EMT issuance in Romania needs to be formally operational before launch.
This is the slower path, but it is the correct one for regulated payment infrastructure. Stablecoins meant for real payments need trust before speed
Update on xMoney Stablecoins
In December, we announced EURXM, USDXM, and RONXM, three fully MiCA-aligned, 1:1 fiat-backed stablecoins, and shared a tentative operational target of June 2026 for launch, depending on final Central Bank regulation coming into effect.
Here’s a brief update on the status, timeline, and next steps.
First, the good news. The products are built. The whitepapers are published. The reserve and audit framework is in place, the infrastructure is ready, and our partners are lined up. From a technology and product standpoint, we are ready to launch.
Second, what we are waiting on is legal and regulatory in nature, and it sits within the jurisdiction of the Central Bank. To be more precise, under MiCA, an e-money token can only be issued once the national competent authority responsible for e-money tokens is formally designated and operational in the issuer's home country. Our stablecoins are issued under a Romanian electronic money license, which means the relevant authority is the National Bank of Romania, but the step that formally activates supervision of e-money token issuance still requires a specific piece of national legislation which is not fully finalized.
That legislation is currently in the works, and Romania is in a government-formation period, meaning a caretaker government operates with limited constitutional powers; hence, it cannot adopt the type of ordinance this step requires until a new government is in place. In other words, we are ready, the European framework is ready, and we are waiting on a national procedural step that today's interim government is not in a position to complete.
Since we operate under full regulated clearance, this means we will only be able to launch when the framework is properly in place and full authorization is ready. After all, this is what MiCA-compliant means.
We are staying close to the process; our infrastructure remains ready, and we are prepared to move with intention once the framework becomes operational.
Thank you for your patience and your trust.
Regulated, scalable, useful digital money for real payments. We're almost there, and doing it properly.

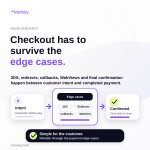
Checkout integrations are easy in the happy path.
The real test is 3DS, redirects, callbacks, mobile WebViews, payment state, and final server-side confirmation.
Good checkout should feel simple to the customer.
But the integration has to survive the edge cases.

xMoney's inline checkout docs include examples for 3DS result handling and mobile WebView flows:
docs.xmoney.com/guides/check… docs.xmoney.com/guides/check…