

Archetype-Research Under the radar: 1. Small-caps 2. Datacenter supply chains 3. Undercovered companies
Plugged In
Joined September 2021
- Tweets4K
- Following298
- Followers11.7K
- Likes2.2K





Pinned Tweet
archetype-research.com/p/kla…
It's quite interesting that Affirm is valued at ~$22Bn $AFRM
Klarna is valued at ~$5Bn $KLAR
Affirm has ~12Bn GMV in Fair Financing (equivalent) growing at 34% YoY
Klarna ~$4.7Bn GMV in Fair Financing growing at 80% YoY
A dumb-simple valuation approach would ask why Klarna is valued at ~$5Bn vs Klarna's $22Bn?
What if each FF (Fair Financing) GMV dollar were valued the same for Klarna? Then Klarna's current FF would achieve a market cap of ~$8.6Bn
With this dumb-simple example-At ~$5Bn market cap, Mr. Market is saying the BNPL business is worth nothing. The advertising worth nothing. The card subscriptions, worth nothing. Less than nothing actually.
So Mr. Market thinks that Fair Financing at Klarna U.S. will never achieve what they have already achieved elsewhere?
Or that Affirm has some special moat compared to Klarna?
I believe Mr. Market is too pessimistic on this Klarna.

1
16
1,708
Pretty interesting price action before earnings:
Klarna +1.4%
Affirm -3.6%

archetype-research.com/p/kla…
New pitch on the stack!

5
1,265
archetype-research.com/p/kla…
New pitch on the stack!
Approximately 27.4% of Worldex's outstanding shares are held by identifiable institutional investors, incorporating AVI's latest 5.31% disclosure.
Activists now make up ~20.95% vs the family's 35.1%.
Minority shareholders already sided with activists in Gumi.
With a couple more activists, they could start wrestling for control!
From what I gather this is a new position for them too, not simply an increase. They were not holding in March, they started holding in Sept 4.5%- now at 5.31% across their funds
Holy shit- Worldex. The cavalry have arrived.
This is major support for minority shareholders. 2027 AGM could be a game-changer.
November 13 filing reveals that Asset Value Investors (AVI), a London-based investment manager, has crossed the 5% ownership threshold in Worldex Industry & Trading (KOSDAQ: 101160).
1
5
1,497
Davy retweeted
Holy shit- Worldex. The cavalry have arrived.
This is major support for minority shareholders. 2027 AGM could be a game-changer.
November 13 filing reveals that Asset Value Investors (AVI), a London-based investment manager, has crossed the 5% ownership threshold in Worldex Industry & Trading (KOSDAQ: 101160).
Oh they're even on X @TrustAVI
Holy shit- Worldex. The cavalry have arrived.
This is major support for minority shareholders. 2027 AGM could be a game-changer.
November 13 filing reveals that Asset Value Investors (AVI), a London-based investment manager, has crossed the 5% ownership threshold in Worldex Industry & Trading (KOSDAQ: 101160).
1
5
1,344
Holy shit- Worldex. The cavalry have arrived.
This is major support for minority shareholders. 2027 AGM could be a game-changer.
November 13 filing reveals that Asset Value Investors (AVI), a London-based investment manager, has crossed the 5% ownership threshold in Worldex Industry & Trading (KOSDAQ: 101160).
Davy retweeted
You want to take advantage of the Korea plunge fellow businessmen?
This is the highest return to risk I see in Korea at the moment.
Its my biggest position.
Worldex trades at EV/EBIT of 3.1. It's closest peer Hana Materials (also cheap imo) trades at EV/EBIT 9.
That's a 3X discrepancy.
They are NOT really exposed to memory prices- they are exposed to memory CAPACITY expansion- which will expand regardless.
They make silicon products which are consumables used in the equipment to make memory.
I have never done so before- but I have just turned on the 1 week free trial for my stack so you guys can get up to date quickly on the company.
Governance has kept the valuation low- but activists won the recent majority vote- and got the company to buyback shares!
The stock is -20% from my pitch and I sleep so easily because I know this company backwards.
There has been activist win after win that have exceeded my bullish assumptions. T
Mr. Market piles this into the same bucket as the memory trade- its anything but that!
Enjoy!
open.substack.com/pub/archet…

Davy retweeted
Just turned on 1 week free trial for the first time ever
so friends can quickly explore what I believe to be the cheapest stock and highest R/R stock on the korean market.
not hiding it- its Worldex- but there's a lot of research you need to do (or just read my research I've done the heavy lifting)
pop a comment and ill get ur free trial to u
You want to take advantage of the Korea plunge fellow businessmen?
This is the highest return to risk I see in Korea at the moment.
Its my biggest position.
Worldex trades at EV/EBIT of 3.1. It's closest peer Hana Materials (also cheap imo) trades at EV/EBIT 9.
That's a 3X discrepancy.
They are NOT really exposed to memory prices- they are exposed to memory CAPACITY expansion- which will expand regardless.
They make silicon products which are consumables used in the equipment to make memory.
I have never done so before- but I have just turned on the 1 week free trial for my stack so you guys can get up to date quickly on the company.
Governance has kept the valuation low- but activists won the recent majority vote- and got the company to buyback shares!
The stock is -20% from my pitch and I sleep so easily because I know this company backwards.
There has been activist win after win that have exceeded my bullish assumptions. T
Mr. Market piles this into the same bucket as the memory trade- its anything but that!
Enjoy!
open.substack.com/pub/archet…

Just turned on 1 week free trial for the first time ever
so friends can quickly explore what I believe to be the cheapest stock and highest R/R stock on the korean market.
not hiding it- its Worldex- but there's a lot of research you need to do (or just read my research I've done the heavy lifting)
pop a comment and ill get ur free trial to u
You want to take advantage of the Korea plunge fellow businessmen?
This is the highest return to risk I see in Korea at the moment.
Its my biggest position.
Worldex trades at EV/EBIT of 3.1. It's closest peer Hana Materials (also cheap imo) trades at EV/EBIT 9.
That's a 3X discrepancy.
They are NOT really exposed to memory prices- they are exposed to memory CAPACITY expansion- which will expand regardless.
They make silicon products which are consumables used in the equipment to make memory.
I have never done so before- but I have just turned on the 1 week free trial for my stack so you guys can get up to date quickly on the company.
Governance has kept the valuation low- but activists won the recent majority vote- and got the company to buyback shares!
The stock is -20% from my pitch and I sleep so easily because I know this company backwards.
There has been activist win after win that have exceeded my bullish assumptions. T
Mr. Market piles this into the same bucket as the memory trade- its anything but that!
Enjoy!
open.substack.com/pub/archet…
You want to take advantage of the Korea plunge fellow businessmen?
This is the highest return to risk I see in Korea at the moment.
Its my biggest position.
Worldex trades at EV/EBIT of 3.1. It's closest peer Hana Materials (also cheap imo) trades at EV/EBIT 9.
That's a 3X discrepancy.
They are NOT really exposed to memory prices- they are exposed to memory CAPACITY expansion- which will expand regardless.
They make silicon products which are consumables used in the equipment to make memory.
I have never done so before- but I have just turned on the 1 week free trial for my stack so you guys can get up to date quickly on the company.
Governance has kept the valuation low- but activists won the recent majority vote- and got the company to buyback shares!
The stock is -20% from my pitch and I sleep so easily because I know this company backwards.
There has been activist win after win that have exceeded my bullish assumptions. T
Mr. Market piles this into the same bucket as the memory trade- its anything but that!
Enjoy!
open.substack.com/pub/archet…
I pose a simple question to stimulate some dialogue and holy fuck its like I poked a hornets nest.
Bro comes at me with "What happened to real businessmen? Who are all these stock traders?"
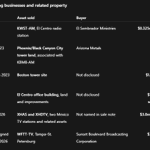
Can we please just have discussion and not get so personal. You suggested they could sell the broadcasting assets (that make a loss currently) for 300-400m? They are on book value at 169m after being impaired every single year.
I asked- How many units EV/EBITDA does EVC need to be discounted to fairly account for its customer concentration risk- where most of its yearly growth (looking at yearly growth mr Roach)- came from.
I'm looking at the revenue drivers that lead to the growth in the business- the UNAMED Hong Kong gaming company. How is the unamed Hong Kong customer doing that accounts for 35% growth? Is that something that interests you?
Instead I should look at a trendline of revenue growth an extrapolate that into infinity?

God forbid you have a different opinion to the consensus 😂
is $EVC cheap or just optically cheap?
LFTO at EV/EBITDA 10- little customer concentration.
EVC at 7. massive customer concentration. And stalled growth.
AppLovin at EV/EBITDA 16. Makes sense.
At EVC 7x multiple. If a big customer stops spend you get a 30-40% gap down,
If they land a new customer it gaps up 30-40%.
Management still don't want to dispose their broadcasting assets- but they're wasting their focus on a non-core part of the business.
Looks fairly valued compared to their competitors. The valuation seems to account for the customer concentration risk and the growth volatility...
1
15
2,516
is $EVC cheap or just optically cheap?
LFTO at EV/EBITDA 10- little customer concentration.
EVC at 7. massive customer concentration. And stalled growth.
AppLovin at EV/EBITDA 16. Makes sense.
At EVC 7x multiple. If a big customer stops spend you get a 30-40% gap down,
If they land a new customer it gaps up 30-40%.
Management still don't want to dispose their broadcasting assets- but they're wasting their focus on a non-core part of the business.
Looks fairly valued compared to their competitors. The valuation seems to account for the customer concentration risk and the growth volatility...