





BokehResearch retweeted
Isn’t there a chance of it being incremental and more minor, consisting of a kind of escalation ladder, with tit-for-tat strikes to test a threshold and then climb down?
Why wouldn’t that be an equally likely scenario ?
What are the chances a president who would spend $5000 per citizen to win midterm elections (>$1 Trillion), would also interfere in the oil futures markets? #oott

Why isn't oil at $200? Because "someone" keeps dumping oil futures all night long, and the CFTC refuses to look into it. Heck, even when it's clear-cut insider trading, the CFTC has been told to "back off," and they did. bloomberg.com/news/features/…


KSA is exporting large volumes via the SoH after the E/W pipeline got hit. Iran has indicated its desire to toll the SoH. Are they willing to toll while being blockaded if the price is right? $10/b on a VLCC is $20USD per ship. KSA would rather pay that then shut-in. #oott
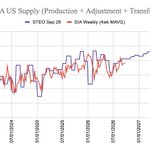
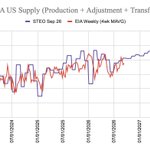
I don't see anything problematic with the EIA's current supply projections, but it's worth keeping an eye on. Supply is aggregated (production, adjustment, and transfer barrels), as that gives the cleanest picture.
@HFI_Research #oott

BokehResearch retweeted

Note published to @SpartaCommo clients last evening, do subscribe if you have not already:
Saudi E/W pipeline outage update
13 Sep 26 - 15:00 CEST
1⃣ According to the Ministry of Energy, the Saudi East-West pipeline in the Riyadh and Madinah regions was subjected to multiple attacks on Thursday 10 September. The pipeline has been shutdown as a precautionary measure. This pipeline typically carries Arab Light and Arab Heavy crude, both to domestic refineries and to the export markets.
2⃣ Duration of the outage is unknown. The attacks apparently came from Iraq, and not directly related to the Houthis that had seized the port city of Mocha on Thursday.
3⃣ If the pipelines flows are restored within a short time, there should have enough buffer within the system to keep the domestic refineries running. However exports of crude via the Red Sea will be met with some difficulty after drawing down from tank inventories at Yanbu.
4⃣ Additionally production shut-ins are likely if the crude stocks hits tank top on the Eastern side of Saudi. We anticipate dirty freight availability to be the key constraint in managing the evacuation option ex Ras Tanura. This will support TD3c markets further.
5⃣ European refiners (particularly in the Med) that have been relying on Saudi crude ex Sidi Kerir will also face temporary prompt shortages. This will mirror how Asian refineries reacted at the onset of the SoH closure, whereby reducing runrates is the likely outcome while waiting for viable crude replacements to arrive.
6⃣ Eastern refiners are not fully spared from this scenario as well since Korea and Japan have been seen chartering cargoes ex-Sidi Kerir but at least they may still benefit from getting crude ex Gulf of Oman in a shorter time if Saudi is able to offer this option.
7⃣ 400 kbd YASREF refinery, 400 kbd SAMREF and 245 kbd Yanbu refinery exports products, mainly distillates. If the pipeline outage exceeds the time the refineries have on available crude buffers, then the refineries may be forced to shutdown later due to crude unavailability. This is the likely worst case scenario which will only happen if the pipeline is out for an extended period of time.
8⃣ This means the diesel tightness we have seen in Europe will become further exacerbated with some Med refineries turning down on intake in the prompt while reevaluating crude replacement options, and potentially facing the worst-case scenario of the Saudi refineries themselves not exporting products.
9⃣ Thus we are likely going to see higher flatprice, Brent-Dubai EFS, DFL, prompt crude timespreads, crude FOB diffs, diesel timespreads and even stronger cracks when we start the week, until further clarity is found. This is of course subject to any new headlines of peace deals that can quickly temper the excitement.
🔟 Jet and mogas cracks will likely be pulled up by the diesel strength. Dirty freight could also move up with more inefficient freight routings anticipated.
An extended outage could also see IEA coming in with further SPR release to calm the markets, but that buffer is getting thinner.
#oott

The SPR has drawn 122mb since Feb, out of the ~134mb awarded. For now, the SPR will not be backfilling in Sep and Oct.
US exports are competitive as Sparta noted "More US crudes are heard to have been purchased by both Japanese and Korean refiners for November arrivals
#oott
Days of Crude Supply excluding Pipeline Fill are at the lows of the last decade (15.7 days). #oott @HFI_Research

Days of Supply Ex Pipeline Fill approaching 10 year lows. Spot 321 Crack > $50. Price collapsing.
#oott

Had the 84mm barrels of SPR releases over the last 12 weeks come out of commercial inventory (hypothetical BS), Days of Supply Ex Pipeline fill would be ~11.4.
** BS because refinery runs, product supplied, & trade would all be affected **. #oott

US Commercial Crude Days of Supply Ex Pipeline Fill
4 more draws like the week (8.3mb), would hit historical minimum.
US Commercial Crude was the last to draw. Products are already tight (GC 321 >$40). SPR sales are slowing the draw (over 50% of the crude draw).
#oott


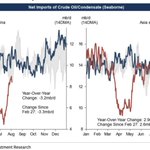
The presumption that China isn't going to buy oil, and instead will draw inventories, with cash Brent trading in the mid 80s seems unlikely. #oott
HOUSTON — The U.S. military is escorting ships carrying approximately 7 million barrels a day of crude oil and fuel products through the Strait of Hormuz, Energy Secretary Chris Wright said Friday.
This seems counter to what most trackers are seeing.
@TankerTrackers #oott