

Most investors look too late. I track where capital moves first. Systematic rankings across 1300+ mining & resource stocks.
Joined April 2022
- Tweets7.7K
- Following171
- Followers9.7K
- Likes41.5K




JUNIOR MINING STOCK RETURNS SINCE THE FEBRUARY 29, 2024 BULL MARKET BEGAN: EXTRAORDINARY GAINS AND DEVASTATING DRAWDOWNS
A historical study of 452 junior mining companies | February 29, 2024 – October 26, 2026
Structural Alpha Research
452 mining companies. Nearly three years of historical data. Extraordinary cumulative gains — and an equally extraordinary collapse in market breadth.
The junior mining sector is experiencing one of the most severe periods of technical deterioration in our historical study.
Yet the data reveal a striking paradox.
Almost three out of four junior mining companies remain in positive territory since February 2024, even though the median stock has fallen more than 50% from its individual high.
How can a market generate exceptional long-term returns while suffering such a devastating correction?
Our study of 452 junior mining companies, covering February 29, 2024 through October 26, 2026, examines cumulative performance, drawdowns, moving-average participation, new lows and relative strength.
The results offer a revealing picture of the sector's internal condition.
1. THE BULL MARKET IS STILL VISIBLE IN HISTORICAL RETURNS
Despite the recent selloff, the cumulative performance of the universe remains remarkable.
Of the 452 companies analyzed:
334 companies (73.9%) have positive cumulative returns.
112 companies (24.8%) have negative returns.
6 companies (1.3%) are essentially unchanged.
The median cumulative return stands at +127.27%.
In other words, the company at the center of the distribution has more than doubled its initial share price.
This is not the profile of a universe that has failed to generate wealth over the full study period.
But cumulative returns tell only part of the story.
They do not reveal how much of those gains has subsequently disappeared.
2. THE OTHER SIDE OF THE RALLY: DEVASTATING DRAWDOWNS
The drawdown statistics are among the most striking findings of the study.
Median maximum drawdown: −61.49%
Median current drawdown: −51.31%
Companies currently down from their highs:
At least 30%: 367 companies.
At least 40%: 311 companies.
At least 50%: 240 companies.
At least 60%: 160 companies.
More than half of the universe is trading at least 50% below its individual high during the study period.
Consider the contrast:
Median cumulative return: +127.27%.
Median current drawdown: −51.31%.
Both figures describe the same group of companies.
A market can retain extraordinary gains over a multiyear period while simultaneously undergoing a correction of exceptional severity.
These are not contradictory observations. They reveal the extreme volatility and dispersion characteristic of junior mining equities.
Importantly, these are cross-sectional company statistics, not the performance of an investable equal-weighted index.
3. MARKET BREADTH REVEALS THE EXTENT OF THE DAMAGE
To understand the current condition of the sector, we need to look beyond cumulative returns.
Market breadth measures how many companies are actually participating in a trend.
And the deterioration has been dramatic.
Participation above the 200-day moving average
On August 28, 50.23% of companies with sufficient data traded above their 200-session moving average.
By October 23, that figure had collapsed to 17.56%.
On October 26, it recovered only marginally to 17.75%.
That represents a decline of more than 32 percentage points in less than two months.
The weakness is no longer confined to a limited group of underperforming stocks.
It has spread across the vast majority of the universe.
Participation above the 50-day moving average
The deterioration is even more severe in the intermediate trend.
On August 28, 78.14% of companies traded above their 50-session moving average.
By October 23, participation had fallen to just 6.83%.
On October 26, it improved slightly to 7.67%.
Fewer than eight out of every hundred companies were above their 50-day moving average.
This is not an ordinary deterioration in momentum. It is an exceptionally broad breakdown in trend participation.
The simultaneous weakness of the 50-day and 200-day measures indicates that both intermediate- and longer-term technical structures have been severely damaged.
4. NEW LOWS CONFIRM THE INTENSITY OF SELLING PRESSURE
Moving averages are only one dimension of market breadth.
New lows provide another important perspective.
On October 23:
40.00% of companies with valid data recorded new 20-session closing lows.
9.51% recorded new 52-week closing lows.
By October 26, those percentages had declined to:
26.38% for 20-session lows.
6.95% for 52-week lows.
The decline in short-term new lows was substantial: 13.62 percentage points in a single session.
However, the distinction between short-term and long-term new lows is crucial.
A surge in 20-day lows can reflect a sharp liquidation event.
A significant expansion in 52-week lows suggests something more persistent: companies are breaking price levels that had held for approximately an entire trading year.
The current correction therefore involves not only intense selling pressure, but also significant deterioration in longer-term price structures.
5. IS A BULLISH BREADTH DIVERGENCE DEVELOPING?
This is perhaps the most important question.
After such an extreme deterioration, investors naturally begin looking for evidence that selling pressure is exhausting itself.
Bullish breadth divergences typically emerge when the market continues to register new price lows, but progressively fewer companies participate in that move.
The internal market begins to improve before the broader recovery becomes obvious.
The October 26 readings offer some preliminary encouragement.
Compared with October 23:
MA200 participation improved from 17.56% to 17.75%.
MA50 participation improved from 6.83% to 7.67%.
New 20-session lows declined from 40.00% to 26.38%.
New 52-week lows declined from 9.51% to 6.95%.
These are favorable developments.
But they represent only one session.
There is not yet sufficient evidence to declare a confirmed bullish breadth divergence.
A durable improvement would require a sustained contraction in new lows, broader participation above moving averages and evidence that the market can maintain its recovery.
An isolated rebound after an extreme selloff is not the same as a structural reversal.
6. RELATIVE STRENGTH: THE NEXT LEADERS MAY ALREADY BE DIFFERENT
One of the defining characteristics of junior mining equities is the enormous dispersion between individual companies.
Some stocks have multiplied their prices many times over since February 2024.
Others have suffered catastrophic losses.
Even among the strongest cumulative performers, the ability to preserve gains varies dramatically.
For example:
San Lorenzo Gold has accumulated a gain exceeding 7,600%, with a current drawdown of approximately 24%.
Patagonia Gold retains a cumulative gain exceeding 2,100%, but its current drawdown exceeds 74%.
Discovery Silver combines a cumulative gain above 1,500% with a current drawdown of approximately 24%.
These examples illustrate an important distinction.
Historical leadership is not necessarily the same as current resilience.
A company may rank among the greatest winners of a bull-market cycle while simultaneously experiencing an exceptionally severe correction.
Relative strength should therefore be evaluated through both cumulative performance and the ability to withstand market-wide selling pressure.
And as market conditions change, leadership may rotate.
The companies that dominated the previous advance will not necessarily lead the next recovery.
7. CORRECTION WITHIN A BULL MARKET — OR THE BEGINNING OF A BEAR MARKET?
The evidence supports two plausible scenarios.
The recovery scenario
The current decline could represent an extreme liquidation phase within a longer-term bull market.
Under this scenario, new lows would progressively contract, participation above moving averages would recover, and a smaller group of resilient companies could begin establishing new leadership.
Breadth improvement might emerge before the broader price recovery becomes convincing.
The prolonged deterioration scenario
Alternatively, the correction could continue eroding the substantial gains accumulated since February 2024.
Initial rebounds might fail to restore intermediate-term trends.
Participation could remain depressed, while persistent 52-week lows would indicate further deterioration in long-term structures.
At present, the data do not allow either scenario to be ruled out.
The decisive factor will not simply be how far prices have already fallen.
It will be whether the market's internal condition begins to improve consistently.
8. WHAT WE ARE WATCHING NEXT
Five indicators will be particularly important over the coming weeks:
50-day moving-average participation: Is the intermediate trend beginning to recover?
200-day moving-average participation: Are longer-term structures being rebuilt?
20-session new lows: Is immediate selling pressure losing breadth?
52-week new lows: Is longer-term technical deterioration beginning to subside?
Relative strength: Which companies are demonstrating resilience and emerging leadership?
No single indicator is sufficient.
The strongest evidence would come from several measures improving together and sustaining that improvement.
THE CENTRAL CONCLUSION
Our study of 452 junior mining companies reveals five essential findings.
First: The cycle since February 2024 has generated extraordinary cumulative gains. Nearly 74% of companies remain positive, and the median cumulative return exceeds 127%.
Second: The correction has been devastating. The median current drawdown exceeds 51%, and more than half the universe has lost at least half its value from individual highs.
Third: Technical deterioration is extraordinarily widespread. Participation above both the 50-day and 200-day moving averages has collapsed.
Fourth: Selling pressure is affecting longer-term structures, as shown by the expansion in 52-week lows.
Fifth: The October 26 improvement is encouraging, but it does not yet constitute a confirmed bullish divergence.
The distinction matters.
Extreme oversold conditions describe the magnitude of a decline. They do not, by themselves, prove that the decline has ended.
The most important signal will not merely be that junior mining stocks stop falling.
It will be that market breadth begins to improve persistently.
Until then, analytical caution remains essential.
READ THE COMPLETE RESEARCH
The full study includes detailed historical breadth statistics, moving-average participation tables, new-low analysis, relative-strength comparisons, methodology and an interactive ranking of all 452 junior mining companies, including cumulative returns and maximum and current drawdowns.
Structural Alpha Research — Full Study:
structuralalpharesearch.net/…
Independent quantitative research. For informational purposes only. Not investment advice.
#JuniorMiners #GoldStocks #SilverStocks #MiningStocks #MarketBreadth #Drawdown #RelativeStrength


Gold's rise may be telling us something far more important than where inflation or interest rates are heading. It may reflect a fundamental shift in confidence in the global monetary system. A perspective worth considering.


Uranium stocks are approaching a historic extreme.
Not because of one spectacular crash, but because the selling has become relentless.
Nearly 90% of uranium-linked stocks fell last week. Fewer than 10% remain above their 200-day moving averages.
And the median stock is now 53% below its 52-week high.
Across 153 weeks of data, market breadth has never been weaker.
Yet there’s a crucial distinction: trading volume hasn't exploded. This looks more like persistent selling and disappearing buyers than a final capitulation.
Is the uranium sector approaching a major opportunity—or is there still another leg down?
The conditions for a powerful recovery may be developing. The evidence of a bottom is not there yet.
Full analysis, historical charts & 75-stock ranking:
structuralalpharesearch.net/…
#Uranium #NuclearEnergy #MiningStocks

Are we witnessing another historic capitulation in junior miners?
Our analysis of 482 mining companies reveals:
• 79.7% declined last week.
• Median weekly return: -8.13%.
• Median drawdown from 52-week highs: -47.99%.
• Only 16.8% trade above their 200-day moving average.
We've seen extreme selling before: 2015, 2020 and 2022.
But there's an important difference this time.
Gold prices remain historically elevated, and many producers are generating exceptional margins.
The market may be pricing a collapse in confidence rather than a collapse in fundamentals.
Of course, not every junior will survive. Financing risk, dilution and poor management still matter.
But history suggests that the greatest opportunities often emerge when investors abandon an entire sector indiscriminately.
The question isn't whether junior miners are cheap.
It's whether the market is failing to distinguish between weak companies and genuinely valuable assets.
#Gold #Silver #JuniorMiners #MiningStocks

GOLD AND SILVER MINERS | Brutal Correction or the Destruction of the Bull Market? The Data Tell a Very Different Story.
I have conducted a quantitative study of 203 gold and silver mining companies, analyzing their performance from February 29, 2024, which I consider the beginning of the current bull market, through October 23, 2026.
The objective was to answer a particularly important question following the violent declines we have witnessed:
How many companies have actually given back all the gains accumulated during the bull market, and how many are still holding on to substantial profits?
To answer this question, I calculated three metrics for each company:
Cumulative return: The percentage change in price since the beginning of the bull market.
Maximum drawdown: The largest decline from a previous peak during the period analyzed.
Current drawdown: The percentage decline from the highest price recorded during the period to the most recent closing price.
The results are extraordinarily revealing.
1. THE OVERWHELMING MAJORITY OF MINERS ARE STILL SITTING ON SUBSTANTIAL GAINS
Of the 203 companies analyzed:
186 companies (91.6%) still show positive returns.
Only 17 companies (8.4%) are trading below their starting levels.
The median cumulative return stands at an impressive +209.67%.
Let's consider that last figure for a moment.
It means that the company at the midpoint of the distribution has seen its share price increase approximately 3.1-fold since February 2024, despite the magnitude of the subsequent correction.
2. THE CORRECTION HAS BEEN EXTRAORDINARILY VIOLENT
The drawdown figures reveal another equally important reality:
Median maximum drawdown: −50.22%.
Median current drawdown: −38.82%.
In other words, the typical company in the sample has experienced a decline of more than 50% from a previous peak at some point during the period and is currently trading almost 39% below its highest level over that period.
This helps explain why investor sentiment has become so negative.
However, there is a fundamental difference between losing 40% from the highs after a stock has multiplied several times in value and losing 40% relative to where it stood at the beginning of the bull market.
These are not equivalent situations.
A company can experience a devastating correction from its recent highs and still retain extraordinary cumulative gains.
3. THE DIFFERENCES BETWEEN INDIVIDUAL COMPANIES ARE ENORMOUS
Some miners have maintained spectacular returns since February 2024:
Benz Mining: +2,774%
Omai Gold Mines: +1,911%
Montage Gold: +1,785%
At the opposite end of the spectrum, we find companies that have not only surrendered all their previous gains but are now trading substantially below their initial levels.
These 17 companies deserve individual analysis to determine whether their declines reflect company-specific problems, deteriorating fundamentals, financing requirements, shareholder dilution, or an excessive market reaction.
But we must avoid jumping to conclusions: a company that has fallen sharply is not necessarily an attractive investment opportunity.
Price action must be analyzed alongside fundamentals, technical structure, and relative strength.
4. WHAT DO THESE RESULTS TELL US ABOUT THE BULL MARKET?
This is, in my view, the most important conclusion.
If we were witnessing a widespread destruction of the gains accumulated during this cycle, we would expect to find a much larger proportion of companies trading below their February 2024 levels.
Yet we are seeing precisely the opposite.
More than 91% of the companies analyzed remain in positive territory since the beginning of the bull market.
The correction has been extremely deep, but it has not erased the enormous gains accumulated by most of the companies in the sample.
This is consistent with my technical interpretation: we are going through a very severe correction, but one of a lower degree than the major structural bear markets of the past.
Naturally, these figures do not guarantee that the lows are already in. Nor do they prove, on their own, that every company still has an intact individual uptrend.
But they certainly put the true magnitude of what has happened into perspective.
5. MY CONCLUSION
Long-term bull markets do not advance in a straight line.
They can experience extraordinarily violent corrections that damage sentiment, trigger substantial losses from peak valuations, and lead many investors to question whether the bull market even exists anymore.
And yet, when we broaden our perspective, we discover that a large portion of the gains accumulated throughout the cycle remains intact.
That is precisely the contrast revealed by these 203 securities: a median cumulative return of +209.67% coexisting with a median current drawdown of −38.82%.
That is why I believe it is essential to distinguish between a severe correction and the end of a bull market.
They are two very different things.
I've published my complete quantitative study of 203 gold and silver mining companies, including an interactive ranking showing the individual performance of every security.
Despite the severity of the recent correction, 91.6% of the companies remain in positive territory since February 29, 2024, with a remarkable median cumulative return of +209.67%, even as the median current drawdown stands at −38.82%.
These findings highlight a crucial distinction: a brutal correction does not necessarily mean the end of a bull market.
Explore the full analysis and interactive ranking of all 203 securities at Structural Alpha Research:
structuralalpharesearch.net/…
Methodological note: This study is based on 203 companies with sufficient price history and available data. Returns represent changes in share prices, not total returns adjusted for dividends. The composition of the sample introduces potential selection and survivorship biases; the conclusions describe the companies analyzed and do not necessarily represent the entire sector.
#Gold #Silver #GoldMiners #SilverMiners #GDX #GDXJ #MiningStocks #BullMarket #TechnicalAnalysis

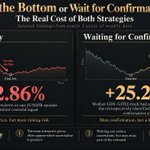
Buy the Bottom or Wait for Confirmation? The Real Cost of Both Strategies
One of the hardest decisions in a mining bull market is knowing when to buy a correction.
Buy too early, and you may have to endure substantial additional losses. Wait for confirmation, and a significant part of the rebound may already be behind you.
In our latest research at Structural Alpha Research, we examined nearly three years of weekly data across the JUNIOR and GDX–GDXJ mining universes.
What did we find?
• In one episode, the median junior miner suffered a further 22.86% decline after the initial oversold signal.
• In another, the median GDX–GDXJ stock had already rebounded 25.22% from the retrospectively identified breadth low before confirmation arrived.
• Confirmation did not necessarily mean the opportunity was over. Significant gains were still possible afterward.
• Neither approach proved consistently superior. Buying early involves greater timing uncertainty; waiting may mean accepting a higher entry price.
The central conclusion:
The most attractive prices often appear when uncertainty is greatest. By the time the market offers convincing confirmation, much of the initial recovery may already have occurred.
There is no perfect entry. Every investor must decide which risk they are more willing to accept.
Read the full study:
structuralalpharesearch.net/…
#Gold #Silver #GoldMiners #GDX #GDXJ #Investing

🚨 JUNIOR MINERS: MARKET BREADTH HITS A 152-WEEK LOW
The correction in junior mining stocks has reached extraordinary levels.
My latest weekly analysis covers 482 securities:
📉 384 declined this week (79.7%)
📉 Median weekly return: −8.13%
🔴 Only 16.81% remain above their 200-day MA
📉 Median 52-week drawdown: −47.99%
Market breadth and median distance from the 200-day MA have both reached their lowest readings in 152 weeks.
Selling pressure is extreme. But does that mean we're approaching the end of the correction?
📊 Full analysis + interactive ranking of all 482 securities:
structuralalpharesearch.net/…
#JuniorMiners #GoldMiners #SilverMiners #MiningStocks

$GDX / $URA | Are We Witnessing the Beginning of a New Era of Leadership for Gold Miners Over Uranium?
The GDX/URA relative strength chart is displaying a long-term technical structure that deserves close attention.
Between 2010 and 2020, we can identify a five-wave impulsive advance, followed by an A-B-C correction that appears to have ended at the 2024 lows.
Since then, the ratio has been recovering, respecting a long-term rising trendline and showing increasingly strong upward momentum.
Three technical factors support this interpretation:
1. Elliott Wave Structure. The A-B-C correction may be complete, potentially setting the stage for a new impulsive advance of a higher degree.
2. Ichimoku. The ratio is currently challenging a major resistance zone around 2.34–2.40, which coincides with the upper boundary of the Kumo. A sustained breakout would significantly strengthen the bullish scenario.
3. Momentum. The momentum oscillator continues to accelerate higher, remaining above its signal line with a positive histogram. There are no obvious signs of exhaustion yet.
Another particularly important technical development is that a sustained move above 2.34 would firmly reclaim the 23.6% Fibonacci retracement level at 2.2217.
The next relevant technical levels would be approximately 2.94, followed by the previous major highs around 3.79.
What does all this suggest?
Gold miners may be entering a new phase of relative leadership over uranium stocks.
And this does not necessarily mean that uranium stocks are headed lower.
If the breakout above 2.34–2.40 is confirmed, we could be looking at a potentially significant long-term technical signal.
#GDX #URA #GoldMiners #Uranium #RelativeStrength #TechnicalAnalysis

$ASM | Could Avino Be the Canary in the Coal Mine for This Correction?
I have a feeling that Avino Silver & Gold Mines' chart could provide some important clues about how much further the current correction in mining stocks has to run.
Its long-term technical structure remains particularly interesting.
The $4.05 area represents a major support level, close to the long-term rising trendline. From current levels, the stock could still decline another 12–13% before reaching that zone.
But here's an important detail: the Ichimoku cloud (Kumo) is sitting in that same general area and is already acting as support. That means it may not be easy for the stock to fall all the way to the rising trendline, let alone break below it.
If Avino eventually approaches $4.05 without damaging its long-term bullish structure, I would consider it an exceptionally attractive buying opportunity — almost a no-brainer at those levels.
The real question is whether Avino needs to reach that support or whether the correction will end before it gets there.
I'll be watching this chart very closely. It may offer an important clue as to where the broader correction in mining stocks could finally come to an end.
#Avino #ASM #Silver #GoldMiners #Gold

THE HIDDEN COST OF WAITING FOR CONFIRMATION 📊⛏️
What if waiting for a confirmed breakout means missing a substantial part of a mining stock's rally?
At Structural Alpha Research, we examined 1,256 early-entry signals across our GDX–GDXJ gold mining universe.
The findings were striking:
🔹 Only 31.8% of early entries subsequently confirmed a breakout within 130 trading sessions.
🔹 Among those that confirmed, stocks had already gained a median 38.7% before confirmation arrived.
🔹 Confirmed setups delivered a median +45.3% over 130 sessions from the early entry.
🔹 Those that never confirmed returned a median −5.3%.
But here's the twist.
We also tested whether volume, relative strength, momentum, and market conditions could identify future winners in advance.
The predictive model failed out of sample (AUC: 0.429).
The lesson?
Waiting for confirmation can be expensive. Buying too early can be even more dangerous.
The real challenge isn't recognizing a breakout after it happens.
It's identifying the right companies before the market confirms their potential.
Full study, methodology, and limitations:
structuralalpharesearch.net/…
#GoldMiners #JuniorMiners #TechnicalAnalysis #QuantitativeResearch

🚨 GDX–GDXJ | EXTREME SELLING PRESSURE
The correction in gold and silver miners continues to intensify.
My latest weekly analysis covers 147 securities, with some historically extreme readings:
📉 139 of 147 declined (94.6%)
📉 Median weekly return: −9.33%
🔴 Only 13.7% remain above their 200-day MA
📉 Median 52-week drawdown: −36.23%
Market breadth has reached its second-lowest reading in 152 weeks, while the 20-session signed volume balance is the third-most negative.
Selling pressure is extreme, but capitulation is not yet confirmed.
📊 Full analysis + interactive ranking of all 147 securities:
structuralalpharesearch.net/…
#GDX #GDXJ #GoldMiners #SilverMiners #MiningStocks

🚨 STRONG VS. WEAK MINERS: WHO REALLY MAKES MORE MONEY AFTER A SELLOFF?
When mining stocks get crushed, investors face a classic dilemma:
Buy the strongest companies that held up during the correction—or the most beaten-down stocks with the greatest rebound potential?
We analyzed nearly three years of historical data covering junior mining stocks.
The results reveal a fascinating paradox.
📈 The strongest stocks win on consistency. They delivered higher median returns and a greater percentage of positive outcomes.
🚀 The weakest stocks win on spectacular rebounds. Some produced extraordinary gains, pushing their average returns above those of stronger companies.
But here's the twist:
Once extreme outliers are removed, the weakest stocks' advantage in average returns virtually disappears.
And after the deepest market corrections? Neither group shows a consistently reliable advantage.
The biggest potential rebound isn't necessarily the best investment opportunity.
📊 Full research, charts, methodology and conclusions:
structuralalpharesearch.net/…
#GoldMiners #JuniorMiners #MiningStocks

🚨 MINING STOCKS ARE GETTING CRUSHED. SO WHY IS THE S&P 500 HOLDING UP?
Our latest global market analysis compares 12 market universes and 2,555 instrument observations, revealing a striking divergence.
📉 Gold, silver, copper, uranium, lithium and junior miners are under intense selling pressure.
🔴 Only 13.7% of GDX–GDXJ and 12.4% of SIL–SILJ securities remain above their 200-day moving averages.
🟢 Meanwhile, energy (69.2%) and the S&P 500 (56.5%) continue to show much healthier market breadth.
The mining sector is experiencing an exceptionally broad correction, but the rest of the market is telling a very different story.
📊 Full global analysis, sector comparisons and market breadth:
structuralalpharesearch.net/…
#MarketBreadth #GoldMiners #SilverMiners #MiningStocks #Copper

$COPX | THE CORRECTION THAT TOOK ITS TIME
Copper miners showed remarkable resilience while the rest of the mining sector was undergoing a sharp correction.
But as we warned earlier, that relative strength was unlikely to keep them immune to the broader correction.
It took longer to arrive, but the correction is finally underway.
COPX has broken below the Ichimoku cloud, and momentum continues to deteriorate.
From an Elliott Wave perspective, we may be seeing wave c of an a-b-c corrective structure, with potentially significant downside still ahead.
📉 $65–66: 50% Fibonacci retracement.
📉 $57: 61.8% Fibonacci retracement, a deeper downside target that I wouldn't rule out.
A correction of this magnitude would not necessarily invalidate the long-term bullish trend.
Relative strength delayed the correction, but it couldn't prevent it.
#COPX #Copper #CopperMiners #MiningStocks

🚨 GOLD & SILVER MINERS: THE GREAT DIVERGENCE — UPDATED
I've expanded yesterday's study from 189 to 214 mining stocks and updated it with the latest available closing prices.
📉 188 stocks in the red (87.9%)
📉 Median return: −28.95%
📉 Median maximum drawdown: −45.11%
The correction since January 29 has been brutal, but the divergence between individual miners remains striking.
📊 Attached: the 30 best and 30 worst performers.
Full updated analysis + interactive ranking of all 214 stocks:
structuralalpharesearch.net/…
#GoldMiners #SilverMiners #MiningStocks


🚨 ASX MINERS: A BRUTAL WEEK
The selling pressure across Australian mining stocks has reached extreme levels.
📉 84 of 89 stocks declined (94.4%)
🔴 Median weekly return: −11.43%
🔴 Only 11.2% remain above their 200-day moving averages.
🔴 Median 52-week drawdown: −40.46%
Even more interesting: median relative volume is just 0.74× its reference level.
Widespread selling pressure, but not necessarily capitulation.
Is the sector approaching exhaustion, or is there more downside ahead?
📊 Full analysis + interactive ranking of all 89 ASX mining stocks:
structuralalpharesearch.net/…
#ASX #GoldMiners #SilverMiners #MiningStocks

189 mining securities. 163 losers. One stock up 164%. ⛏️📉
I analyzed returns and maximum drawdowns across the combined GDX–GDXJ and SIL–SILJ research universes, from January 29 to October 21, 2026.
The results are striking:
🔴 85.9% finished with negative returns.
📉 Median return: −24.1%.
📉 Median maximum drawdown: −43.3%.
Yet the divergence is extraordinary:
🟢 Panoro Minerals: +164.0%
🟢 Sailfish Royalty: +86.2%
🟢 New Pacific Metals: +68.6%
🔴 Hycroft Mining: −62.5%
🔴 Guanajuato Silver: −63.2%
🔴 Manuka Resources: −76.8%
Same correction. Radically different outcomes.
This is why stock selection, relative strength, and entry timing matter so much in mining.
A 50% decline doesn't automatically make a stock cheap. And even some of the strongest performers have suffered brutal drawdowns along the way.
The next mining rally won't reward every company equally.
📊 Top 30 and bottom 30 attached.
🔎 Full research, methodology, and interactive ranking of all 198 securities:
structuralalpharesearch.net/…
#GoldMiners #SilverMiners #MiningStocks


$PAAS – Unusual Relative Weakness. Something Brewing? 👀
Pan American Silver is down around 2% today while $SIL, $SILJ and several major silver producers are holding up significantly better.
This divergence is worth watching.
Could the market be anticipating a corporate transaction, possibly an acquisition by Pan American Silver?
There's no confirmed information suggesting that. But unexplained relative weakness sometimes precedes corporate developments.
Just a hypothesis, not a conclusion.
#Silver #PAAS #MiningStocks
A stock falling 40% doesn't automatically make it cheap. ⛏️
In a mining bull market, some of the biggest opportunities emerge after brutal corrections.
But here's the catch:
A 40% decline in a strong company may be an opportunity.
A 40% decline in a weak company may be just the beginning.
Look at $HYMC and $FSM.
Both suffered corrections exceeding 40%.
$HYMC broke major support and continued falling, eventually reaching a 71% drawdown.
$FSM found buyers near major support around $8 and subsequently rallied more than 50% from that area.
The difference isn't the size of the correction.
It's whether the long-term bullish structure remains intact, whether support holds, and whether selling pressure begins to fade.
I don't buy stocks because they've fallen enough.
I buy when the risk/reward becomes attractive.
Those are two very different things.
#GoldMiners #SilverMiners #TechnicalAnalysis
