

https://teapawt.net/t.co/yfgkx1j1Uv https://teapawt.net/t.co/iKhOOw45jT
npub1d06l80kquxlwnlnz004s5t86q
Joined June 2012
- Tweets9.3K
- Following3.2K
- Followers726
- Likes81.4K





Pinned Tweet
📊 October 2026: Hedge Bots Only
OKX +21.2% (19–26 Oct, hedge bots only) | Binance +8.61% (1–16 Oct, mixed book)
- From 19 Oct the fleet runs hedge bots only: a paired long and short on each name, not one-sided grids. The aim is smoother returns and lower drawdowns.
- Before the switch, Binance (Zignaly) ran our mixed book and made +8.61% for 1–16 Oct.
- The big up on 23 Oct (+17.9%) was an ADL on IRYS. OKX closed our long at the top. Excluding that day, OKX made +3.3%.
- ADLs have always gone our way, but some clients understandably don't want that risk. We now agree the coin universe with each client individually.
- The setup shown is our standard configuration. We accommodate other client requests, and some OKX accounts were already allocated earlier in the month, so they run differently.
- BloFin: we are working to recover the accounts compromised by a fault on BloFin's side. Detail: marginsyndicate.com/venue-st…
- Quants.Space is fixing an accounting bug in its OKX figures. The OKX numbers here are from the exchange's daily PnL. Binance is verified on Quants.Space.
Past performance is not indicative of future results.

Options update: our 26-structure BTC options engine is live on Deribit and Coincall.
Implied vol ~38% vs forecast realised ~51%. Negative VRP, so the model is long convexity (straddles/strangles), not selling vol.
OKX moves to the new engine next.
marginsyndicate.com/options-…

Options demo is live: marginsyndicate.com/options-….
OKX demo account, read-only, positions delayed 15 minutes, every snapshot signed and verified in the browser.
Set up and waiting for the first structures to clear the edge gate; the engine now runs the full 26-structure catalogue, long and short premium, sized off live account equity rather than a fixed constant.
Demo is simulated and not evidence of profitability. It shows what the system does.

OPTIONS: BOTH SIDES OF THE PREMIUM
For most of this year the options mandate sold premium: credit spreads and iron structures, collecting the volatility risk premium. That premium has been poor. Implied volatility has sat below realised for weeks at a time, so the seller is paid less than the volatility costs and an engine that only sells has nothing to do in that regime.
So the catalogue has been extended to the other side. The engine now trades long-premium structures as well as short, across every venue it operates on: long calls and puts, straddles and strangles, debit spreads, reverse iron condors and butterflies, backspreads and protected calendars and diagonals.
Which side it selects is decided on every tick from the sign of the risk premium and the shape of the surface. There is no standing view. When selling is paid, it sells; when volatility is cheap, it buys.
The machinery around it is unchanged. Each client account is isolated and attested at boot. Positions, orders and balances are mirrored continuously and reconciled every tick against the engine’s own book; any discrepancy halts new risk until resolved.
Greeks, margin, drawdown and regime are evaluated on every tick through a deterministic mode state machine and exits are worked as limit-chase programmes rather than crossed through wide option spreads.
marginsyndicate.com/options-…


Zignaly is gone. If you want to run our systems on KuCoin and have never opened an exchange account, Robin at KuCoin (t.me/RobinKucoin) will walk you through it: account, KYC, funding and a Managed Sub-Account linked to Margin Syndicate.
The link works like this. You create the sub-account under your own KuCoin login and bind our UID. We get trading permission and nothing else. You can top up, withdraw or unlink at any time; we never hold withdrawal.
Robin works for KuCoin, not for us. He gets you to the point where the account is linked. Anything about the strategy or your account with us comes through our Gateway group, not through him. t.me/marginsyndicategateway

Zignaly is closing. All Margin Syndicate positions there close today 10:00 UTC; funds return to your Zignaly account. To continue: withdraw to a CEX or Hyperliquid, I send an onboarding form, you add API keys, done. SMA minimums waived for Zignaly clients. t.me/duffelbagdan

Zignaly announced today that it is shutting its platform after nine years to focus on ZIG Finance. All trading services close at 10:00 UTC on 16 October and investor funds return to Zignaly balances for withdrawal until 1 December.
Margin Syndicate ran a small number of services there. Every investor on them has been told what happens, when and how to get their money out. Nothing is pending on our side.
Rolling Sharpe now measuring 4.1.
Volatility 105%
Still up and to the right.
Quantspace Report:
report.quants.space/result/0…
Service:
marginsyndicate.com/derivati…

Options engine update: the structure catalogue has grown from short-volatility-only to 26 bounded templates, long and short vol, with the expanded profile installed and running on Deribit. Coincall remains on the verified four-family build. Profitability unproven.
The 26: 22 single-expiry structures plus four protected calendars and diagonals. Catalogue membership earns nothing by itself; every candidate combination is assessed against portfolio delta, vega, loss, liquidity and account-specific margin before it can enter.
Calendars and diagonals carry a lifecycle rule: 72 hours before the front expiry, roll or close. No exceptions by template.
Regression coverage now spans inverse settlement, account separation, instrument minimum quantities, restart/reconciliation and high-water-mark preservation. The latest forecast repair passed focused, PostgreSQL and full non-integration engine checks.
Deribit: all 26 family permissions are installed and the replacement engine is verified running. Risk is measured in BTC against a drawdown ladder with pause, resume and hard-stop levels; profile renewals preserved the existing high-water mark.
Deployed repairs on Deribit: instrument minimum quantities, account and journal coverage, publisher processing. The last forecast blockage was a stopped history feed, not model incompatibility; the collector is restarted and caught up to current candles.
Open on Deribit: forecast consumption and family evaluation by the engine after the feed fix, and a collector that is still local and time-limited. Unattended continuity is not yet established.
Coincall: the verified build is the four-family system, iron condors, corrected iron butterflies, bull-put and bear-call spreads, with feed-throughput, reporting and forward-price qualification repairs in place. 19-second option freshness, 10 bp forward uncertainty.
Coincall still lacks the broader portfolio profile and carries a pilot lifetime-entry restriction; account-specific cost and margin, combined high-water-mark and recovery qualification remain outstanding. Deribit's inverse, unified-account evidence does not transfer.
Limitations: the expanded portfolio is not verified operating autonomously on both venues. This is the latest evidenced state, not a live audit. Engineering verification is not evidence of edge; the release is explicitly experimental and minimum-size.
Next: operational closure on Deribit with continuous input maintenance, and the broader production package completed and installed on Coincall. Neither is presented as a proven autonomous expanded-strategy deployment.
marginsyndicate.com/options-…

Progress on our cross-venue perp arbitrage system: four paired ETH round trips on Hyperliquid and Lighter testnets, 7,097 tests passing and a read-only shadow run now collecting production market data. Execution works. Profitability is unproven. Thread.
The strategy evaluates both directions of a matched perp pair: long A/short B and short A/long B. Expected basis convergence plus funding carry, less entry and exit fees, executable-depth slippage, capital cost, recovery reserves and an uncertainty haircut.
Candidates must pass freshness, liquidity, margin, capability and delta checks before ranking. Ranking is risk-adjusted expected return over capital reserved on both venues. Margin and liquidation stay venue-local; the engine holds no credentials.
Execution controls: durable paired intent before any order, concurrent IOC marketable-limit slices with unique client IDs, chase of confirmed residual only, immutable adverse-price limits and deadlines, residual-delta accounting, bounded reduce-only recovery then halt.
What traded, 2 Oct: 0.007 ETH each leg, long Hyperliquid, short Lighter. Fills reconciled, normal close, both accounts flat. Cost 0.027489 USDC including fees and execution-price difference. Native account state and durable reconstruction agreed.
Repeatability: three more successes within ten attempts, achieved in nine. Three paired round trips, three one-sided fills recovered to flat without operator orders, three connection failures with no orders sent. Batch cost 0.128436 USDC including recovery.
That is four paired successes, not four consecutive. Connection reliability and simultaneous two-leg completion need work. The failures stay in the evidence. These were authorised uneconomic tests; completion says nothing about edge.
Verification: 7,097 tests across foundation, transport, architecture and shadow suites; strict typing on 218 source files; 463 deployed files matched the committed archive. Independent review drove fixes for cross-route execution authority and concurrent claim handling.
Now running: a bounded shadow collection of production Hyperliquid and Lighter ETH data. No keys, no signers, no orders. Hash-linked journals, both directions, 60s, 5m and 1h horizons. Window closes 4 Oct. No hypothetical trade is reported as profitable.
Limitations: one asset, one authenticated direction. Binance and Bybit adapters built and locally tested, paired execution not yet demonstrated. Aster blocked by testnet access. Mainnet, unattended operation and economic viability are separate acceptance decisions.
Next: verify the shadow journals, calibrate convergence, funding, fee and risk assumptions from evidence, fix measured reliability gaps without loosening admission or recovery, then extend beyond one pair before claiming generality.
marginsyndicate.com/universa…
September: roughly +31.4% on the month. Full report: marginsyndicate.com/stats
That's the mixed book — hedge plus directional grids — with the volatility and drawdown that come with it. No free lunch claimed.
The structural work: net exposure cut hard across the hedge-bot fleet. Fixed telemetry, live impact measurement via Cornix MCP, continuous exchange data, methodology applied on every scan.
This month's study: do the hedge bots earn enough under controlled slope and leverage, net of fees and funding, before we size up. Measured, not assumed.
Our hedging bots are now producing reliable income.
This is still toy money, we haven't started to accelerate.
The choice is leverage and/or slope/gradient - we are leaning toward the latter initially for technical reasons.
The interesting thing about these systems is they are hedged, therefore carry very little delta (subject to slope position and gradient) or drawdown.
I'm not interested in catering for people who want 1 or 2% a month with low drawdown - its not challenging and they tend to be high maintenance customers.
So we will accelerate this month.
The issue was telemetry tracking, ticker choice and system build. We built and improved the technology to fix the issues.
marginsyndicate.com/derivati…

+31.74% on the month. The structural story matters more: net exposure cut hard across the hedge-bot fleet.
Fixed telemetry, Cornix MCP for live impact measurement, continuous major-exchange data pulls. Selection is now a measured property, not a judgement call.
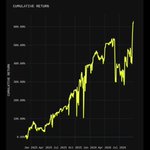
Lifetime: 195% CAGR, Sharpe 1.57, Sortino 2.39 — and a -55% max drawdown to get there. High-variance by construction.
This month was about lowering the variance without losing the engine. Neutral by construction, measured continuously.
marginsyndicate.com/stats
platform.quants.space/api/re…
