

Dispersion is the tax on asymmetry. Disclaimer: All my theories are wrong. Do your own research.
Kepler-452b
Joined August 2013
- Tweets3.7K
- Following425
- Followers3.4K
- Likes8.7K



Pinned Tweet
this is the problem bittensor is solving, and many still don’t see it.
$TAO isn’t an option. it’s the future.
let that sink in.
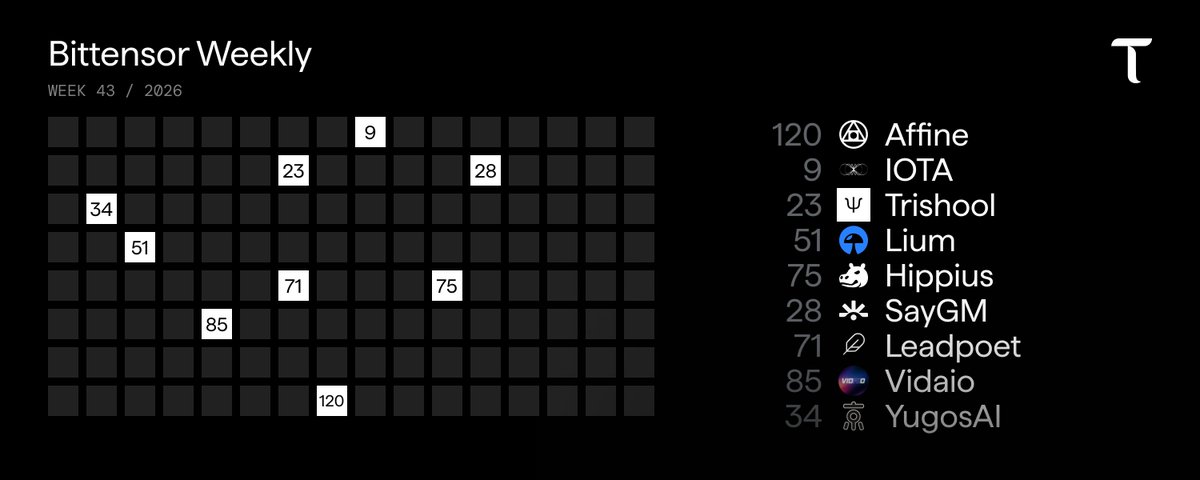
yugos is an interesting project to watch.
the idea is simple: find the best AI model for each task, balancing quality, speed and cost.
openrouter already does a lot of this, alongside competitors like litellm, portkey and not diamond. so the competition is real.
but if yugos can develop smarter routing, prove it performs better and attract real usage, it could carve out its own position.
the bittensor angle makes it even more interesting. competitive miners, better routing and potentially more demand for decentralized inference.
still plenty to prove, but if the team executes, yugos could have a shot.
product, execution and real demand. that's what matters.
#SN34 $tao


good to see some movement. don't stop halfway @jon_durbin

Here's a very crude simplified chutes roadmap/plan, for near term:
- move the most unprofitable things off of the subnet, including today's announcement of some (not all) additional inference options (not paid via emissions)
- this allows us to scale the things we want and need to avoid capacity issues/better direct incentive - this includes models we use to build data pipelines and relationships to other teams/networks/etc
- add options that are completely revenue positive (hourly pricing/rentals/simple docker based jobs/etc), TEE, private, secure, priced above cost, more extensive version of private chutes we have today basically
- expand the hourly compute offerings to also include CPU only (e.g. to run agents, web browsers, sandboxes, non-GPU work of any kind)
- use some of the incentive for ideally non-datacenter based model training and serving
- build a non-extractable product on chutes from the models we build, via dynamic edge nodes, possibly from the epigenesis work (smaller faster cheaper faster than lora customizations from the sparse sections of pretrained model, participant supplied)
- models and pipeline etc. will be open source, the customization and ensemble thereof will live only in chutes, inc. the continuously evolving set of served variations/RL/etc.
We'd like, to the extent we can, attract participants who want to build and have no obligation to pay datacenters or any particular hardware vendor, to keep the value inside the subnet at all times by attacking sell pressure at the source (DC commitments, chip purchases, etc).
We will continue to have secure TEE inference and GPUs; not elimating anything wholesale, just focusing more on a commodity that doesn't have to flow out to DCs and single hardware vendors.
NVIDIA reportedly has 75% profit margins, revenue for the sake of revenue fueling GPU reselling goes straight to one place, basically. Fine, I guess, but I'd rather work together as individuals with whatever hardware we can bring, to a reasonable degree.
“openai loses money, so chutes doesn’t need to be profitable.” incredible logic. openai has massive demand, distribution and access to capital. that doesn’t give every AI project a free pass on economics. you can’t borrow someone else’s valuation and pretend you’ve earned it lol. wake up.
even if parallax becomes a huge success, jon still needs to explain how that translates into sustainable economics and actual value for sn64 holders. company success, product success and token performance are not interchangeable. you keep jumping from one to the next as if there’s no gap. that gap is the entire investment thesis, mate.
and that’s exactly the problem today: the company registered in his name appears to be benefiting from the emissions, while the subnet and its holders are bleeding. so let’s see if, once the company gets what it needs from the subnet, jon throws the holders a bone. until then, spare us the billion dollar victory lap.

how can you hype buybacks, revenue idk what, burns, while the biggest AI labs are losing money as if they didn't think to be profitable, but engy, and all these other inference subnets "need to be profitable" the benchmark is openai and anthropic and they lose but are valued at trillions while developping models that need more and more hardware. Chutes is doing the opposite. do you understand that if they find an AI hardware breakthrough via parralax, while staying alive with sn owner emissions (which is totally fair) only that will be worth billions longterm.
November will be an interesting month for $TAO.
YoY chart shows 2023 +233%, 2024 +60%, 2025 –55%, 2026 YTD +9%. November has been volatile historically.
This time the backdrop is different: subnet external revenue just crossed >$50M annualized (up >40% in a month).
Plus eTAO flexible emissions, 60-day immunity, and real customer metrics accelerating.
Emissions still dominate, but the commercial layer is growing fast.


stop staring at the price. start looking at what’s being built. $TAO

since july, the chutes narrative has been evolving faster than the actual proof.
charts, price predictions, 3.5 hour videos explaining what chutes is, endless theories about the future, and now a $0.2t endgame
at some point, the line between having a thesis and living in a fantasy starts to disappear
a decentralized inference marketplace? dynamic pricing? autonomous providers? sure, these things may be possible. but people talk about them as if every step is guaranteed to happen and every future scenario is already worth pricing in today
that's not fundamental analysis, that's speculation dressed up as certainty
the question isn't how big chutes could become in someone's imagination
it's what has actually been delivered, whether the economics make sense, and what justifies the valuation today
months of explaining the vision don't make it reality
the market doesn't owe anyone a trillion dollar outcome just because they've made enough charts to believe in one
#sn64
while everyone is busy watching price, #sn53 is quietly building an empire.
$214k in buybacks and burns.
134b tokens projected today.
let that sink in.
this is what separates a real contender from a subnet living off hype and emissions.
and yes, this is why sn53 is coming for chutes. the competition isn't just about who can attract the most attention. it's about who can build a sustainable business, create real demand, and deliver value beyond emissions.
keep one thing in mind: sn53 was created on july 22.
look at what's already being built.
price is just a distraction. the fundamentals are what matter.
watch the builders, not the chart. $tao


when i started calling this out, the miners and “supporters” hated me for it. apparently, questioning the economics makes you a hater.
but the numbers were always there.
with the tao pool they’ve accumulated, of course they can take their time. and they’ll keep taking their time. why rush to improve when the protocol keeps paying the bills? emissions have been flowing there for ages, and every tao holder is indirectly paying for that game.
the team and miners have had their upside while investors have been bleeding since the beginning.
chutes has arguably realized more tao value than any other subnet.
at some point, you have to ask yourself: is this the biggest heist in bittensor history, or am i missing something?
i'll leave that judgment to you.
but until the team proves it can deliver the right outcomes for all investors, not just the people benefiting from the current model, skepticism is justified.
this was never personal. it was always about economics.
hype gets attention. fundamentals earn conviction.
make of it what you will.

DeepFuckingValue (τ) retweeted

Last 6 weeks at Bitcast HQ have been busier than ever.
New stuff incoming.
Aiming to have everything on the road map out by the end of year....
....and more. 🤖

Today we’re announcing Bitcast’s expansion.
Over the past year we’ve built the world’s most streamlined creator marketing pipeline.
Today we’re announcing the next chapter.
• Expanding beyond Web3
• New intelligence platforms
• New Web2 facing brand
• AI-powered customer acquisition
• Fiat payments
And more.
🧵


funny how psychology works.
let's put sn53 vs sn51 into perspective.
sn53
> top 5 holders: 52k tao combined
sn51
> top 5 holders: 60k tao locked + another 99k tao, excluding the owner's 60k
and we're comparing the top 5 holders of both subnets here.
so why is holder concentration viewed as a concern for sn53, but not necessarily treated the same way for sn51?
being around longer doesn't automatically mean holders are less likely to sell.
having a large position doesn't automatically mean someone is preparing to dump either.
nobody knows what individual holders will do.
the same goes for team transparency.
algod backs sn51, and its owner, ning, is doxxed.
fish isn't doxxed either. yet people can apply completely different standards depending on which subnet they're looking at.
just think about it. are you looking at the facts, or are you letting your assumptions shape how you interpret them?
every subnet carries risks. nothing is guaranteed. but don't let short term sentiment distract you from the bigger picture: the team, the execution, the progress, and the potential.
i'm very bullish on sn53. i believe they'll keep delivering, improving, and growing.
keep an open mind. question your own assumptions. don't let the noise do your thinking for you.
$TAO #SN53


DeepFuckingValue (τ) retweeted

Grayscale's Bittensor Trust had 3,247,300 shares outstanding on October 13, up 14.25% from 2,842,300 on September 15. Its latest new shares were issued for TAO worth $1,451,029.
@opentensor


DeepFuckingValue (τ) retweeted
Really excited to have Yorgos on board.
We’ve learnt a huge amount from running @Stitch3_ai over the last year.
We’re now pushing the intelligence and automation further.
Yorgos is going to be a huge part of that.
Please welcome Yorgos to Bitcast.
Yorgos recently joined us to help lead the next phase of our creator intelligence - bringing some serious technical firepower with him.
Ph.D. in Computer Science specialising in Graph ML.
His research has been published in prestigious international conferences associated with organisations such as IEEE, ACM and SIAM, including work recognised among the best papers at the SIAM International Conference on Data Mining.
More recently, his work on advanced multi-graph analysis was selected for presentation at Stanford, alongside graph research from teams at NVIDIA, Amazon and others working at the forefront of the field.
He has also worked at Los Alamos National Laboratory, one of the US’s major scientific research institutions.
So why does all of this matter for Bitcast?
Social networks are graphs!
Creators, audiences, conversations and communities form enormous interconnected networks.
Understanding those relationships allows us to go far beyond follower counts and basic engagement metrics.
Who actually influences who? How does information move between them? Who has real influence within a specific niche?
And ultimately: which creators are most likely to deliver results for a particular campaign?
Graph analysis has been a core part of Stitch3 from the beginning.
Yorgos is now helping us push it further, applying advanced Graph ML to build improved ways of identifying influence, understanding communities and matching brands with the creators most likely to reach the right audience.
We want to build the intelligence layer that makes creator marketing automated, scalable and more effective than ever before.
Yorgos is going to be one of the technical powerhouses driving that forward.
Welcome, Yorgos.
