

Europe macro. Opinions my own. All of them.
Joined February 2013
- Tweets7.6K
- Following3.6K
- Followers17.8K
- Likes7.8K
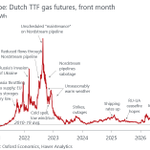




EU wholesale gas prices are a whisker away from €100/MWh, the highest since end-2022 and a key psychological threshold.
Energy prices pushed up Eurozone inflation to almost 4% in September. It will peak much higher with price pressures broadening out. A difficult winter ahead.

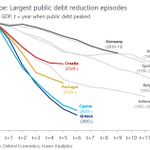
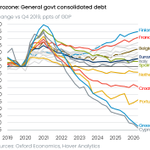
Small South European economies are undergoing the largest and fastest public debt reduction episodes in recent history based on sound fiscal policies and strong growth, not financial repression or inflation. One for the history books. 🇬🇷🇵🇹🇨🇾🇭🇷


A rare W for Eastern Europe and L for the Nordics
(Sine 2021 the EU has a tax on unrecycled plastic packaging)

In 2024, the EU recycled 42.4% of all the generated plastic packaging waste. 🛍️♻️
Highest recycling rate in:
🇱🇻Latvia 71.0%
🇧🇪Belgium (58.2%)
🇵🇱Poland (56.0%)
Lowest in:
🇩🇰Denmark (22.5%)
🇫🇮Finland (26.9%)
🇫🇷France (27.4%)
Read more 👉link.europa.eu/77DrkP

ALT Recycling rate for plastic packaging waste, 2024 (%), EU and EFTA countries
Govt debt-to-GDP ratios 2020 -> 2026 (% of GDP):
🇬🇷 213% -> 137%
🇮🇹 158% -> 138%
🇵🇹 137% -> 87%
🇫🇷 118% -> 120%
🇨🇾 118% -> 49% (among the lowest)
🇧🇪 115% -> 112%
🇸🇮 85% -> 65%
🇫🇮 73% -> 90%
🇸🇰 58% -> 65%
🇭🇷 88% -> 54%
Same currency and fiscal rules. Very different outcomes.

Finland stands out as having the worst debt-to-GDP dynamics. But most of this is due to its unique pension system. It also has a long history of running large primary surpluses. Markets remain sanguine - borrowing costs have risen little and are close to par with the Netherlands.

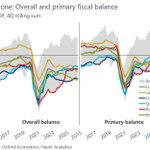
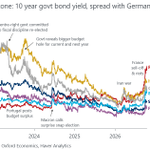
Lost in all the Franco-doomerism is an even more problematic country - Belgium. It has a wider primary & overall deficit with both moving in the wrong direction (former has improved in France) & still no budget. No wonder its yields rose the most after France in current sell-off.

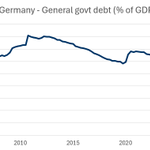
🇪🇺 govt debt-to-GDP ratio is rising again, masking diverging dynamics. 🇫🇷🇧🇪🇫🇮 and increasingly 🇩🇪 are pulling it up. Conversely, 🇬🇷🇵🇹🇭🇷🇨🇾 and to a small extent 🇪🇸 pull in the opposite direction.
Markets are attentive to this, hence different levels of contagion from 🇫🇷 sell-off.

Euro area government #debt at 88.8% of GDP in Q2 2026 (compared with 88.4% in Q1 2026) ec.europa.eu/eurostat/en/web…

ALT General government debt to GDP ratio, Q1 2026 – in percentage
After an initial broad sell-off, markets have started to differentiate among 🇪🇺 govts. Spreads widened again in 🇫🇷 & 🇧🇪, which has a weak backdrop, fractious politics and large consolidation needs, but shrank in South Europe. Bond market is back as the key constraint for govts.

Worth adding that the IMF expects this consolidation to happen fully on the revenues side - ie. taxes going up. By the end of this decade, govt revenue is expected to be over 6ppts of GDP higher than in 2019 - an unprecedented peacetime rise without much to show for it.


The hybrid car deal is an important precedent - the EU got a major concession from China on a key industry without retaliation. But it's just one of many facing clear import surges - the EU will seek to extend the blueprint to other sectors. It may not go so smoothly.


NEW: Emboldened by hybrid car deal, Europe coalesces around a tougher China stance
The mood in Brussels has hardened this week. The place is awash with the notion that standing up to China might actually work
A long read from me ahead of today's EUCO
scmp.com/news/china/diplomac…

No surprises on the use of AI by EU companies at the very top and bottom, but some surprises in between. Based on latest @EurobarometerEU.

The sell off in French govt debt is having ripple effects across other Euro sovereigns with spreads for other high debt countries rising. Here the chances of ECB leaning against it are higher than for France, perhaps starting with verbal interventions.

China's exports to the EU are up by double digits, but that is the case across all regions - the China shock impacts the whole world.
The EU's export share has been stable at 14-15%. A key issue is the collapse in EU import share (12%->8%). Those EU exports are not coming back.

EU is moving to build a wall around its single market to protect it from unfair Chinese competition. But this will increase pressure on EU exporters as China will divert exports into third markets. EU's future is one of less openness & more reliance on domestic-demand led growth.


Amid renewed Franco / Eurodoom, worth pointing out France is a very standard G7 economy. "Only" the govt deficit needs to be addressed (though it is still much better than in the US).
Below based on latest @IMFNews forecasts 👇


IMF Growth Forecast 2026:
🇺🇸 US: 2.3%
🇩🇪 Germany: 1.3%
🇫🇷 France: 0.4%
🇮🇹 Italy: 0.8%
🇪🇸 Spain: 2.5%
🇬🇧 UK: 1.3%
🇯🇵 Japan:0.7%
🇨🇦 Canada: 1.1%
🇨🇳 China:4.5%
🇮🇳 India: 7.0%
🇷🇺 Russia:0.9%
🇧🇷 Brazil: 2.2%
🇲🇽 Mexico: 1.5%
🇸🇦 Saudi Arabia: -3.3%
🇳🇬 Nigeria: 4.2%
🇿🇦 South Africa: 1.0%
imf.org/en/publications/weo/…

French govt debt has stopped rolling off the ECB's balance sheet lately. May reflect maturities of bonds held but it keeps happening around events that caused spreads to jump: Macron losing his majority in parliament (summer 2024), fall of Bayrou govt (2025) and current sell-off.

The surge in EU imports of Chinese hybrids, from 20k/month units last year to trending to over 100k/month by end of this year, was bound to trigger an EU response. Voluntary export restraints is exactly what the US used vs Japan autos in the 1980s. The results were mixed then.


🇪🇺🇨🇳 EU to Cap Chinese Hybrid Car Imports at 350,000 Each Year - Bloomberg
bloomberg.com/news/articles/…


French govt spending is 57.5% of GDP and deficit will be >6% next year absent a consolidation. Melenchon & Le Pen, who look set to make the run-off next year, didn't go into politics to cut pensions. Why French spread with Germany is exploding with contagion on others. Buckle up.


Dynamique inédite pour @JLMelenchon qui se qualifie pour le second tour de l’élection présidentielle dans toutes les hypothèses du dernier sondage Harris Interactive.
Il est le seul candidat capable d’affronter et de battre l’extrême droite.
Rejoignez la bataille pour la victoire ! #Melenchon2027

After weeks of being in denial, the EU is finally moving ahead with soft energy rationing.

The European Commission has told capitals to reduce demand for gas and electricity in a bid to tame prices amid a global energy crunch.
politico.eu/article/eu-commi…

