

EPFR offers financial institutions around the world an unparalleled understanding of how money is moving and why, through fund flows and asset allocation data.
Joined April 2009
- Tweets1.8K
- Following191
- Followers3.1K
- Likes98




𝗧𝗵𝗲 𝟮𝟬𝟮𝟳 𝗜𝗻𝘃𝗲𝘀𝘁𝗺𝗲𝗻𝘁 𝗟𝗮𝗻𝗱𝘀𝗰𝗮𝗽𝗲: 𝗔𝗜, 𝗧𝗿𝗮𝗱𝗲 & 𝗚𝗹𝗼𝗯𝗮𝗹 𝗠𝗮𝗿𝗸𝗲𝘁 𝗦𝗵𝗶𝗳𝘁𝘀
What will shape global markets and investment decisions in 2027?
Join ISI Markets for an exclusive in-person event in Singapore, to explore the key economic forces shaping the 2027 investment landscape.
Register now: eu1.hubs.ly/H0zZKBP0
#ASEAN #APAC #GlobalMarketShifts #AI #Investment

90
𝐈𝐒𝐈 𝐆𝐥𝐨𝐛𝐚𝐥 𝐌𝐚𝐜𝐫𝐨 𝐎𝐮𝐭𝐥𝐨𝐨𝐤 - 𝐄𝐮𝐫𝐨𝐩𝐞𝐚𝐧 𝐔𝐧𝐢𝐨𝐧
CEIC nowcasts point to a Q3 pickup across France, Germany and Italy, with Poland leading the major EU economies. The longer-term picture is tougher. Europe's competitiveness problem is energy, not labor costs: industrial electricity prices are nearly three times China's level.
Chinese manufacturers continue to take share in vehicles, machinery and chemicals across key export markets. Gas storage is entering winter at its lowest seasonal cushion in five years, and the ECB has raised rates as energy pushes inflation higher again.
𝗧𝗵𝗲 𝗰𝗲𝗻𝘁𝗿𝗮𝗹 𝗺𝗲𝘀𝘀𝗮𝗴𝗲? Near-term growth is improving, but energy costs remain the binding constraint on Europe's industrial base.

1
1
464
Download the full report: isimarkets.com/publications/…

342
𝗧𝗵𝗲 𝟮𝟬𝟮𝟳 𝗜𝗻𝘃𝗲𝘀𝘁𝗺𝗲𝗻𝘁 𝗟𝗮𝗻𝗱𝘀𝗰𝗮𝗽𝗲: 𝗔𝗜, 𝗧𝗿𝗮𝗱𝗲 & 𝗚𝗹𝗼𝗯𝗮𝗹 𝗠𝗮𝗿𝗸𝗲𝘁 𝗦𝗵𝗶𝗳𝘁𝘀
What will shape global markets and investment decisions in 2027?
As artificial intelligence transforms industries, global trade dynamics evolve and fiscal uncertainty continues to influence financial markets, investors face new challenges and opportunities in the year ahead.
Join ISI Markets for an exclusive in-person event in Singapore, bringing together market experts and investment professionals to explore the key economic forces shaping the 2027 investment landscape.
𝗗𝗮𝘁𝗲: Wednesday, 13 January 2027
𝗧𝗶𝗺𝗲: 4:00 PM – 6:00 PM (SGT)
𝗩𝗲𝗻𝘂𝗲: Atrium Ballroom, Level 5, PARKROYAL COLLECTION Marina Bay, Singapore
𝗥𝗲𝗴𝗶𝘀𝘁𝗲𝗿 𝘁𝗼 𝗮𝘁𝘁𝗲𝗻𝗱: eu1.hubs.ly/H0zQgDG0
#ASEAN #APAC #GlobalMarketShift #AI #Investment

111
The year-to-date total for all EPFR-tracked 𝗕𝗼𝗻𝗱 𝗙𝘂𝗻𝗱𝘀 has climbed to 99.44% of the full-year record set in 2025, inching closer with daily cumulative flows for the current quarter reaching nearly $84 billion. 𝗗𝗲𝘃𝗲𝗹𝗼𝗽𝗲𝗱 𝗠𝗮𝗿𝗸𝗲𝘁𝘀 𝗕𝗼𝗻𝗱 𝗙𝘂𝗻𝗱𝘀 have surpassed their record inflow total in the prior year by roughly $43.5 billion, a gain of 5%, and standing 12% above inflows seen in 2024. But 𝗘𝗺𝗲𝗿𝗴𝗶𝗻𝗴 𝗠𝗮𝗿𝗸𝗲𝘁 𝗕𝗼𝗻𝗱 𝗙𝘂𝗻𝗱𝘀 have contributed less to this year’s record pace. Their 2025 rebound, which attracted $85.9 billion after three years of net outflows, has proven difficult to match this year.
For more read our Global Navigator: eu1.hubs.ly/H0zN_L60

A Democratic victory in the US midterms failed to dampen investor sentiment. Technology funds attracted $9.8B, while US equity and bond funds drew $48.3B. Falling oil prices lifted risk appetite, but crypto funds suffered sharp redemptions following the $6B Binance hack.
Read more in our Global Navigator: Global Navigator | US political map changes color but flows follow same route in early November - ISI eu1.hubs.ly/H0zLMfH0

143
NDTV Profit link > ndtvprofit.com/videos/busine…
Youtube Channel > youtube.com/watch?v=v5M89ue_…
89
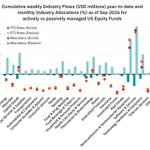
EPFR’s Industry Flows database captured a third straight week of inflows for Semiconductors & Semiconductor Equipment above $5 billion, with their year-to-date total climbing above the $135 billion for passive funds, offset slightly by redemptions of $15 billion from active funds, majority of which has been US led. Passive flows have reached above $120 billion from Software & Services and $77.4 billion for Technology Hardware & Equipment. More striking, actively managed US Equity Funds are underweight Semiconductors and Technology Hardware by the widest margin among all industries, but slightly overweight Software & Services.
For more read our Global Navigator: eu1.hubs.ly/H0zFDW20

1
167
𝐈𝐒𝐈 𝐆𝐥𝐨𝐛𝐚𝐥 𝐌𝐚𝐜𝐫𝐨 𝐎𝐮𝐭𝐥𝐨𝐨𝐤 - 𝐔𝐧𝐢𝐭𝐞𝐝 𝐒𝐭𝐚𝐭𝐞𝐬
The US economy carried robust momentum into 2026, consistently beating growth expectations on the back of resilient personal consumption and private investment. However, the composition of this expansion remains highly uneven. Capital expenditure is acutely concentrated in technology and AI infrastructure.
This targeted capital deployment is yielding macro-level dividends, driving a sharp divergence in labor productivity that heavily favors AI-exposed sectors. Since the launch of OpenAI's ChatGPT in late 2022, average labor productivity in highly AI-exposed sectors has surged by 12.4%, compared to just 5.6% in low-exposure sectors.
𝗧𝗵𝗲 𝗰𝗲𝗻𝘁𝗿𝗮𝗹 𝗺𝗲𝘀𝘀𝗮𝗴𝗲? US productivity growth is concentrated in AI-deploying sectors

1
1
166
Download the full report: isimarkets.com/publications/…
54
𝗘𝘂𝗿𝗼𝗽𝗲 𝗘𝗾𝘂𝗶𝘁𝘆 𝗙𝘂𝗻𝗱𝘀 were again the exception, with redemptions hitting a 13-week high as investors fret about a range of headwinds. In its recently released quarterly outlook, CEIC economists identified the biggest of these headwinds as the perception that Europe is “an AI bystander” and the pressure on Europe’s industrial heartland “from shifting global trade patterns and energy cost disadvantages. Chinese manufacturers continue to capture global market share across passenger vehicles, industrial machinery, and chemicals, eroding European export competitiveness in key third markets”.
For more read our Global Navigator: eu1.hubs.ly/H0zCRS-0

1
157
AI enthusiasm, sticky inflation, and China’s market support measures drove diverging investor behavior in late Oct. Tech funds remained a favorite, bonds drew $15.3B, while crypto and frontier debt funds saw outflows.
Read more in our Global Navigator. Global Navigator | Navigating the late-October crosscurrents - ISI (eu1.hubs.ly/H0zBmq30)

126
The chart below looks at prime contractors in the aerospace and defense industry, alongside major suppliers, space companies and related businesses. Allocation cuts were widespread among many of the industry’s largest holdings by AuM. RTX saw 181 active funds reduce their allocations during August this year versus just nine that increased them, while Boeing (94 vs 4), Howmet Aerospace (176 vs 8) and General Dynamics (127 vs 10), among many others, posted similar one-sided trends, suggesting active managers were taking profits in some of the sector's largest and most widely held names. By contrast, SpaceX attracted strong interest, with 131 active funds increasing allocations compared to just six reducing them. Overall, the data points to a rotation within the sector, with capital moving away from established defense leaders and toward space companies, emerging defense technologies and select Asian manufacturers.
For more read our Global Navigator: Global Navigator | Investors search for the eye of the storm - ISI (eu1.hubs.ly/H0zwsCs0)

145
EPFR Liquidity Offerings data was recently featured in the @Reuters article, "Buybacks just hit an annual record and it's only October," highlighting the massive amount of cash US companies have committed to reducing the share supply of the US equity market in 2026.
Stock buyback announcements in October surpassed the $1.4 trillion mark for the year for the very first time, and $1.5 trillion is within reach. While the headline number is large, buybacks have been concentrated. Announcements from just three companies have accounted for more than a quarter of the overall total (Nvidia, Apple, JP Morgan Chase).
EPFR data shows that repurchase announcement volume has hit new records in each of the past three years. Strong balance sheets and AI have led to the surge in buybacks among large-cap tech, industrial, and financial firms.
Read the full article with link in the comments and learn more about the buyback bonanza.

1
148
• Learn more: tradingview.com/news/reuters…
• The world's prestige media and biggest financial institutions use EPFR to explore global flows. Find out more: isimarkets.com/epfr/

64
𝗝𝗮𝗽𝗮𝗻 𝗘𝗾𝘂𝗶𝘁𝘆 𝗙𝘂𝗻𝗱𝘀 carried the weight among the Asia Pacific groups, absorbing over $6 billion for the first time since late April, the third time in the year-to-date, and just fourth time on record with the other occurring in 2013. The YTD total has reached above $33 billion (or 2.8% of assets), with funds benchmarked to MSCI Japan steadily climbing throughout the year to reach $12.7 billion total (or 13.4% of their assets). The latest week, however, saw Nikkei 225-benchmarked funds account for more than half of the headline number as they absorbed their second-largest inflow behind a 2019 record. Led by funds benchmarked to Nikkei 225 Leveraged, the more volatile group of all 𝗟𝗲𝘃𝗲𝗿𝗮𝗴𝗲𝗱 𝗝𝗮𝗽𝗮𝗻 𝗘𝗾𝘂𝗶𝘁𝘆 𝗙𝘂𝗻𝗱𝘀 saw inflows lift to a 16-week high, snapping a three-week run of outflows.
For more read our Global Navigator: eu1.hubs.ly/H0ztql_0

145
• Learn more: tradingview.com/news/reuters…
• The world's prestige media and biggest financial institutions use EPFR to explore global flows of big money : isimarkets.com/epfr/
37
Geopolitical tensions, rising oil prices and AI investment concerns kept markets on edge. Money Market Fund flows remained volatile as investors prioritized liquidity, while strong demand for US equities and bonds underscored continued appetite for risk assets.
Read more in our Global Navigator: eu1.hubs.ly/H0zrr1L0

142
𝐈𝐒𝐈 𝐆𝐥𝐨𝐛𝐚𝐥 𝐌𝐚𝐜𝐫𝐨 𝐎𝐮𝐭𝐥𝐨𝐨𝐤 - 𝐐4 2026
Persistent energy disruption, renewed monetary tightening, and accelerating AI investment are reshaping global growth.
📢 Key takeaway: Growth remains resilient, but its drivers are diverging. Understanding where growth comes from, and what sustains it, will define the next phase of the macro cycle.
Download the full report: eu1.hubs.ly/H0zqmJj0
#MacroOutlook #Economics #GlobalMarkets #AI

1
127