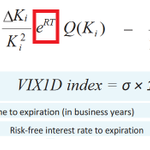EliteVol (@EliteVolatility) header
EliteVol (@EliteVolatility) profile picture

Volatility trader specialized in developing/maintaining adaptive algorithmic trading strategies

Brussels, Belgium
Joined May 2018
Photo by EliteVol (@EliteVolatility)Photo by EliteVol (@EliteVolatility)Photo by EliteVol (@EliteVolatility)Photo by EliteVol (@EliteVolatility)Photo by EliteVol (@EliteVolatility)Photo by EliteVol (@EliteVolatility)Photo by EliteVol (@EliteVolatility)Photo by EliteVol (@EliteVolatility)Photo by EliteVol (@EliteVolatility)Photo by EliteVol (@EliteVolatility)
Today's $VIX expiration should be one for the ages. Current VIX is anybody's guess, as option markets remain closed as long as $ES is in limit-down. SOQ will be chaotic, especially if stocks hit the -7% circuit breaker at the open.
2
For reference: Circuit breaker/Limit Down on Jun #ES contract kicks in at 4755.25 Jun #NQ at 16321.25
1
305
$VXX Better double check guys 🤔
1
381
Did I miss anything while I was gone? 😅
1
413
Following recent rollout of EAFE (VXMXEA) and EM (VXMXEX) VIX indices, CBOE set to launch new range of options based on MSCI global indices on March 18th: World Index Options (MXWLD), ACWI Index Options (MXACW), and USA Index Options (MXUSA) prnewswire.com/news-releases…
1
471
#CNN Fear and Greed Index completely broken for 3 days now🤨🤫
2
546
Exactly 50 years ago today, regulated Call Options of 16 companies started trading at CBOE: They were: AT&T,Atlantic Richfield,Brunswick,Eastman Kodak, Ford,Gulf & Western,Loews,McDonalds,Merck, Northwest Airlines,Pennzoil,Polaroid,Sperry Rand,Texas Instruments,Upjohn and Xerox
1
730
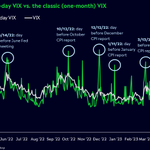
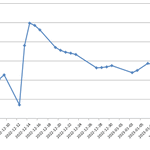
Converting VIX1D closing prices (calc'ed from bus. days) back to cal. days is relatively easy given that there is no interpolation at the close (1 exp only). It clearly shows why CBOE opted for bus. days. As expected, the weekend effect is ridiculous. Spikes remain present $VIX
1
3
562
$VIX CBOE has added historical (close only) data for the new VIX1D index going back to May 13, 2022. The data can be found here 👉 cdn.cboe.com/api/global/us_i…
1
3
6
572
I'm sorry @CBOE , but this is wrong. Risk-free interest rate does not care about Business days/years. The Exponential in the VIX1D formula needs to be calc'ed using calendar days, as is the case with $VIX. Granted, effect is negligible, but correct is correct.
1
4
595
Many things "wrong" with the new VIX1D index. Interpolation within a 1-day timefr. makes no sense. Open+Close will reflect completely different exp. Business day approach will create weekend effect opposite of that present in other $VIX indices as there IS variance premium on WE!
2
395
The Cboe has published a VIX1D white paper cdn.cboe.com/api/global/us_i… . Some significant tweaks have been made to the methodology to compensate for the short time span of the calculation.
1
4
2
30
8,757
$VIX VRO expiration @ 16.75
1
272
Currently the 5th biggest 2-day VVIX pop since inception in 2006 $VIX
4
307
👉Reminder: $VXX about to reverse split 👈
2
363
$NDX Still a typical bear market rally in my book
1
1
1
634