

Understanding Indian Stocks the Smart Way | Techno Funda Insights for Everyday Investors | Learn & Become Financially Free with Us | Disclaimer: No Buy/Sell Adv
Bangalore, India
Joined September 2024
- Tweets1.3K
- Following15
- Followers6.9K
- Likes254




Sudeep Pharma Ltd
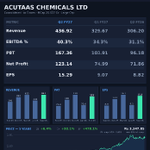
Great set of numbers and above the expectations for top-line numbers.
Topline: ₹197 Cr (+24% QoQ | +21% YoY)
Operating Profit (OP): ₹73 Cr (+33% QoQ | +32% YoY)
OP Margin (OPM): 37% (+254 bps QoQ | +314 bps YoY)
PAT: ₹52 Cr (+28% QoQ | +11% YoY)
#SUDEEPPHRM

Ather Energy Ltd
First Quarterly Profit, Strong Demand and Capacity Expansion
Ather’s Q2 FY27 performance came in better than expected, with sequential EBITDA margin improvement despite rising input costs. The company has also reported its first quarterly profit.
The moderation in revenue growth appears to be driven by capacity constraints rather than weak demand. The new Konarc model is seeing strong traction, while its phased rollout across North, Central and South India is expected to support further expansion. Konarc also offers a relatively better margin profile.
Capacity Expansion: Ather has announced a INR 122 Cr brownfield expansion at Hosur, expected to become operational in Q3. The larger Sambhajinagar facility is also expected to begin phased operations in Q3. Annual capacity is projected to increase from around 9.5 lakh units to 11.4 lakh units by the end of Q2 FY28.
Improved capacity could help the company resume dealer additions and address current supply constraints.
Key Risk: Rising plastic, steel, commodity and memory-chip prices could create margin volatility over the next one or two quarters, despite ongoing cost-efficiency measures and pricing actions.
Overall, demand remains strong, the new model is gaining traction, and capacity additions could support the next phase of growth. The key factors to monitor are execution of capacity expansion and the impact of input-cost inflation on margins.
#ATHERENERG

SG Mart Ltd
#SGMART guidance upgrade
FY27 Full-Year Guidance:
Annualised EBITDA: Rs 300-350 crore (management reaffirmed, barring B2B/Middle East disruption)
Service Centre Exit Count: 11-12 operational centres by FY27 exit (currently 8)
Renewable Structures Volume: 130,000-150,000 tons for the full year, ramping from 5,000-6,000 tons/month to 8,000-9,000 tons/month
Steel Profiles Volume: 100,000+ tons annually
Capex: Rs 400-500 crore in FY27 alone
Three-Year Growth Visibility
Business Growth: 50% CAGR over next 3 years
Service Centres Exit Run-rate: ~20 centres, ~2 million tons/annum
Total Capex Plan: Rs 1,500+ crore over 2-3 years, funded entirely by internal accruals (Rs 698 crore net cash) zero equity dilution
Vision 2030 (Long-Term)
Revenue: Rs 25,000-35,000 crore
EBITDA: Minimum Rs 1,000 crore
Service Centres: More than 20
Management Confidence Statement:
Management expressed confidence in sustained margin retention through sourcing discipline, operating efficiency, and a shift from pure trading to a value-added, asset-supported B2B building materials ecosystem. The transition from low-margin commodity steel trading to higher-margin processed products remains central to the FY30 roadmap.

Acutaas Chemicals Ltd
#ACUTAAS has Upgraded Guidance
Management has raised its revenue growth guidance from 25% to 30% and increased its margin guidance to 38% to 40%.
The CDMO business also has an accelerated growth target. The INR 1,000 Cr revenue milestone, earlier expected by FY28, is now targeted for FY27, with a long-term target of INR 2,000 Cr by 2030.
Higher guidance and an accelerated CDMO timeline indicate strong management confidence in the growth outlook.

Morepen Laboratories Ltd
#MOREPENLAB
The company has delivered excellent numbers, exceeding the expectations set during its previous TV interview. The CDMO contribution is becoming increasingly visible, and the reported performance is better than management’s earlier commitments. Since the company does not conduct concalls, looking forward to its next TV interview to gather further insights and share more updates.


Acutaas Chemicals Ltd
#ACUTAAS
Great set of numbers and revenue guidance upgrade


Westlife Foodworld Ltd
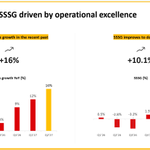
#WESTLIFE SSSG growth is reach to double digit.
Guidance & Outlook:
Management reported that the strong momentum from Q2 has continued into October, supporting its positive outlook for the upcoming festive season. It expects annual profitability to improve by 100 to 150 basis points and remains on track to expand its network to over 580 restaurants by March 2028.
Full-year capital expenditure is projected at INR 250 to 300 Cr. Management also believes the growth trajectory is sustainable, supported by a growing customer base rather than relying primarily on price increases.

Steel Strips Wheels Ltd
#SSWL
Q2 FY27 numbers are blockbuster and Concall key notes.
Margin expansion was driven by a richer product mix, with a higher share of aluminium wheels, increased export contribution, ongoing cost optimization across facilities, and customer price revisions to offset non-raw material input cost inflation.
Demand remains strong, with exports improving. Aluminium wheel market share stands at 64%, excluding Maruti.
At the beginning of the year, management guided for over 20% top-line growth and EBITDA per wheel of more than INR 310. First-half performance exceeded both targets, and management expressed strong confidence in the remaining two quarters and Management is confident that the Q2 EBITDA per wheel of ₹404 is sustainable
October performed very well. If this trend continues through November and December, the next quarter could also be very strong.
Disc: We track monthly business updates and use them to estimate business performance. This is the practice we teach in our community, and we share such insights through our Daily Bytes program.
No buy/sell.
Steel Strips Wheels Ltd
#SSWL
September business data is out, and the performance in the last month of the quarter was really strong.
Overall growth has consistently remained above 22% for the last three months, making this quarter’s business performance particularly strong.
This has been described as an all-time best quarter.

Currency in circulation growth hits five-year high, says RBI report.
business-standard.com/financ…


#STLTECH Q2FY27 concall Key notes
FY29 Targets: The company has maintained its revenue target of 20,000 Cr and increased its EBITDA margin target to around 30% and current orderbook 32000cr.
Improving Margins: Management expects profit margins to remain at 27.1% or higher from Q3 onwards, compared with its earlier FY27 guidance of 23%.
Extra Costs/One Off : ₹39 Cr impairment, ₹22 Cr additional depreciation from writing off subsidiary and High Interest cost are recorded in Q2 and received Tax refund 160cr
Actual Profit Picture: After adjusting for these extra costs, estimated profit 420-450cr
Data Center Growth: Contributed 33% of H1 revenue, with a target of 50% in FY27, supported by two hyperscaler contracts worth over $2.3 billion. Management aims for a 50-60% revenue share from data centers to maintain a balanced customer and geographic mix.
Disc: No buy/sell.
Sterlite Technologies Ltd
#STLTECH
Q2 FY27 blockbuster numbers and Order book reached 32000cr.
The screenshot below speaks a thousand words.
Disc: No buy/sel

Market breadth remained under pressure, with 1,300+ stocks trading lower at one point. Around 900 stocks closed down by more than 3%, despite a slight recovery in the last hour.

On March 23 this year, our short-term momentum indicator "The Market Momentum Indicator" hit the 6% range. It has now tested the same level again, indicating that the market is deeply oversold.

Sterlite Technologies Ltd
#STLTECH
Q2 FY27 blockbuster numbers and Order book reached 32000cr.
The screenshot below speaks a thousand words.
Disc: No buy/sel

Financially Free ™ retweeted

BLOOM ENERGY $BE Q3’26 EARNINGS HIGHLIGHTS
🔹 Revenue: $1.24B (Est. $1.05B) 🟢; +138.1% YoY
🔹 Adj. EPS: $0.94 (Est. $0.68) 🟢
🔹 GAAP EPS: $0.78
🔹 Adj. Gross Margin: 34.5%; +412 bps YoY
Raises FY26 Guide:
🔹 Revenue: $4.40B-$4.60B (Est. $4.1B) 🟢
🔹 Adj. EPS: $3.10-$3.40 (Est. $2.73) 🟢
🔹 Adj. Gross Margin: ~34%
🔹 Adj. Oper Income: $960M-$1.03B
Announcements:
🔹 Added to the S&P 500
Other Q3 Metrics:
🔹 Adj. Oper Income: $285.7M (Est. $214M) 🟢
🔹 GAAP Oper Income: $225.4M
🔹 Operating Cash Flow: -$27.1M
🔹 GAAP Gross Margin: 33.8%; +453 bps YoY
Comments:
🔸 “Bloom is leading that transformation.”

Supreme Power Equipment Ltd
#SUPREMEPWR
FY27 Guidance Upgrade :
- Upgraded Revenue Guidance: The company has upgraded its FY27 revenue guidance from INR 250-300 Cr in the previous concall to INR 300-350 Cr in the latest concall.
- PAT Margin Guidance: Management expects to maintain a PAT margin of 9-12% for FY27.
- Order Book and FY28 Revenue Potential: The company aims to close FY27 with an order book of INR 600-800 Cr and expects to achieve peak revenue of INR 550 Cr in FY28, indicating further growth potential as operations scale.
Disc: No buy/sell, It is a SME company.

Supreme Power Equipment Ltd
#SUPREMEPWR
There were a few interesting questions raised by Our Analysts during the concall. One of the key discussions was on how the company is able to pass on raw material cost increases to customers through price variation clauses. Analysts also asked about value-added products such as Power Transformers and the last Data Centers enquiries .
Overall, the discussion provided some useful insights into the company's business and growth opportunities.


AI agents are testing the limits of banking security 🤖
Major U.S. banks are detecting unauthorized AI agents inside customer accounts some acting beyond user instructions.
axios.com/2026/10/22/ai-agen…
