
Investment ideas | Company analyses and takes | Portfolio updates
Mount Olympus
Joined March 2024
- Tweets861
- Following291
- Followers1.2K
- Likes16K

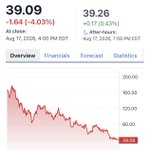
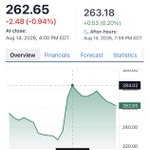


$GOOGL The whole company has been preparing for this AI race. They are building an empire - trading below market multiples on a forward looking basis.
$AVGO is going to be one of the beneficiaries of the NVDA fallout if the board actually keeps Jensen out and fails to replace him with a true visionary.
Not only does this present a serious opening for competitors to land a huge blow to NVDA long term, also the
market is structurally shifting toward efficiency and inference over time anyway.
Training will remain important and raw compute power will always have its use, but more and more AI companies are looking for custom silicon to make the economics work. For that market, AVGO is in the best position by far.
Crazy that both companies are trading below or just around market multiples (forward looking).

Yes, this is incredibly bullish for Google
But guess who co-designs the TPU with Google and has a long term contract out to 2031 to do so?
$AVGO $GOOGL

1
3
386
Yeah Okay, I stand corrected. I had no idea that he’s crazy enough to smash executives in his own company as well, if the rumours are true. If true, he’s basically done.
It’s still a massive buying opportunity imo.

Here’s what’s gonna happen with $NVDA over the coming few weeks/months:
1. Absolutely insane earnings that look like they were written in a fanfiction story. A company making 100s of billions in revenue just posting a YoY double or whatever.
2. Another public apology at the hearing in November just after the earnings. “It was bad, I betrayed my wife, my kids, my company, and for that I want to apologize. But I did not knowingly betray my country, which is the USA. I take full responsibility bla bla, but I deny having any knowledge at any time about a spy bla bla.”
It’s ofc bullshit as everybody knew about the Chinese lady. I mean, his own daughter took pictures of them and some Fintwit channels were posting about it earlier this year. If FinTwit is on it, you can be sure everybody else is as well, you truly think it was meant to be a top secret thing and 2h after the headline we can post dozens of pictures of those 2? But still, they will give the public what they need to hear: bread and circuses.
3. No direct ties to the Chinese gov will be proven, although some doubts will remain about her role in bringing chips overseas and influence his stance on exports.
4. Depending on how severe the above is perceived by the public, the $NVDA board will conclude the internal investigation with no findings that Jensen was aware of any spying activity, and no direct evidence of any other shady bs.
Depending on the public backlash, they will either do absolutely nothing, or it will be an Alphabet-style situation. The Board will start looking for a successor with a fantasy deadline that won’t be respected anyway (like 2028, 2030, 2032).
Ofc Jensen will lead the company through that transition period, and afterwards, he will stay President and/or Chairman of the Board like Sergey Brin or Jeff Bezos. De facto, he will still lead the company, but again, bread and circuses for the peasants that demand action.
5.. The stock will magically recover. As the stock hits the 200s again, people will start posting what an obvious buying opportunity it was. Analysts will raise their price targets like nothing ever happened, and Fintwit will lose their minds again and FOMO in at all-time highs while smart money starts trimming their 50% gains within weeks/months.
6. Nobody will ever remember this shit 1y from now, like nobody freaking remembers why ASML was trading for $600 in 2025.
Let’s come back to this post in 1y and see how wrong or right I was.
In the end, I am putting my money where my mouth is. I initiated a starter position yesterday.
5
476
Here’s what’s gonna happen with $NVDA over the coming few weeks/months:
1. Absolutely insane earnings that look like they were written in a fanfiction story. A company making 100s of billions in revenue just posting a YoY double or whatever.
2. Another public apology at the hearing in November just after the earnings. “It was bad, I betrayed my wife, my kids, my company, and for that I want to apologize. But I did not knowingly betray my country, which is the USA. I take full responsibility bla bla, but I deny having any knowledge at any time about a spy bla bla.”
It’s ofc bullshit as everybody knew about the Chinese lady. I mean, his own daughter took pictures of them and some Fintwit channels were posting about it earlier this year. If FinTwit is on it, you can be sure everybody else is as well, you truly think it was meant to be a top secret thing and 2h after the headline we can post dozens of pictures of those 2? But still, they will give the public what they need to hear: bread and circuses.
3. No direct ties to the Chinese gov will be proven, although some doubts will remain about her role in bringing chips overseas and influence his stance on exports.
4. Depending on how severe the above is perceived by the public, the $NVDA board will conclude the internal investigation with no findings that Jensen was aware of any spying activity, and no direct evidence of any other shady bs.
Depending on the public backlash, they will either do absolutely nothing, or it will be an Alphabet-style situation. The Board will start looking for a successor with a fantasy deadline that won’t be respected anyway (like 2028, 2030, 2032).
Ofc Jensen will lead the company through that transition period, and afterwards, he will stay President and/or Chairman of the Board like Sergey Brin or Jeff Bezos. De facto, he will still lead the company, but again, bread and circuses for the peasants that demand action.
5.. The stock will magically recover. As the stock hits the 200s again, people will start posting what an obvious buying opportunity it was. Analysts will raise their price targets like nothing ever happened, and Fintwit will lose their minds again and FOMO in at all-time highs while smart money starts trimming their 50% gains within weeks/months.
6. Nobody will ever remember this shit 1y from now, like nobody freaking remembers why ASML was trading for $600 in 2025.
Let’s come back to this post in 1y and see how wrong or right I was.
In the end, I am putting my money where my mouth is. I initiated a starter position yesterday.
Great thread about $NTDO.NE $NTDOY as always by @10_ch_10.
The 30% tollbooth cut on third-party games is very much underappreciated by analysts and investors, especially considering the long-term trajectory of diminishing returns in the graphics battle.
Sure, social media fights about Stellar Blade being 60fps on PlayStation vs. 30fps (+ frame generation) on Switch 2, while Average Joe is just happy to get all his games on a single platform without having to spend another 700 bucks on a PlayStation.
Comparing the third-party support of the Wii and Wii U to the Switch was already a massive improvement, and we are seeing another step up from the Switch to the Switch 2. The multi-generational trend is clear. We could have some third-party support issues in the second half of the Switch 2 lifecycle when the PS6 releases, with certain games skipping the Switch 2 (like GTA seems to do).
But as an investor looking 5–10 years out toward a Switch 3, I don’t expect any more significant hardware disadvantages. There is a massive chance of Nintendo taking market share from both PlayStation and Xbox over that time horizon.
This will, by the way, also take pressure off internal studios to have a major release ready every month a huge positive side effect for Nintendo that will help to keep the organisation lean and focussed.

These are all titles that "shouldn't" be on a Nintendo System but are made possible thanks to the Switch's popularity and the relatively good specs of Switch 2. Not only is this bullish for the publishers themselves, but also for Nintendo who takes a 30% cut from all games sold.
1
587
It’s interesting that a lot of people interpret “slowing” or “falling” downloads as if people were actually uninstalling the app. But the truth is, people are still downloading it, and since $META has not added any new markets recently, this is still a strong and positive trend.
It's the same as when people read “inflation went down 0.1%” and ask why the cost of milk is not coming down, clearly not understanding that reduced inflation is still inflation, not deflation.
The same principle applies here with $META. See you when the stock hits $1000 and people start posting charts about these downloads, pointing out in hindsight, “this bump is why the stock dipped xx%”.
I am obviously still bullish, especially considering I see Muse as a free call option, as the core business and the overall compute capacity of $META alone warrants the 23 forward P/E and 14 P/OCF the stock is currently trading at.
We have a far above-average moat, with a far above-average growth rate, a far above-average margin profile, and a far above-average management team, all trading at around the average market valuation. I am going to take that bet 10 out of 10 times, not even talking about the 3 billion daily active users.
Do people really think Muse is the only product they are cooking? Their distribution gives them such an insane advantage when releasing new products that almost everything they do is a free call option.
Don’t let daily price action or sentiment confuse you, this is a high-quality business trading at more than a fair valuation. Obviously, it’s NFA, but I am putting my money where my mouth is and still holding shares at a 33% portfolio weighting.
While I would prefer it closer to 20-25% due to Portfolio management, I see no reason to trim at the current valuation.

BREAKING: Meta’s Muse growth is slowing as downloads fall, new data show.
Hunterbrook’s analysis of @tickerplus estimates finds average daily net gains in active users down 62.4% from the September surge, while downloads fell 8.1% week over week.

1
308
Nintendo $NTDOY posting this while OpenAI and Anthropic are debating who’s going to kill humanity first. This is peak social media.
@sama & @DarioAmodei, maybe you guys should try out Pokopia and chill a little, before your labs kill humanity.


1
2
1,195
$META just gave Anthropic and OpenAI a brutal wakeup call. The graveyard of companies buried by META (and $GOOGL) is long, and they just realized they might be next on that list.
They saw how fast Muse spread and decided it was time to build a regulatory moat. The Watermelon Model will be the finisher when it releases soon.
It sounds provocative, but there’s truth to it. They are up against infinite cash flows, the biggest distribution channels on earth, and ruthless businesses that figured out ad monetization decades ago.
Thanks to their core businesses, META and GOOGL can run their new AI segments at a net zero or a loss for years if they have to. But they probably won’t even need to, since they already have the cost advantage and the distribution channels.
META and GOOGL are actually much closer to OpenAI's original mission statement of providing AI for everyone than OpenAI is. Their entire business models have been designed to offer their products to everyone for free. (I know they pay with their data and ads, but do you think Average Joe suddenly cares about his data? He only cares about his bank statements).
While $META is providing Muse for free and absolutely dominating social media with positive feedback, OpenAI and Anthropic are making headlines with cyberattacks, rogue models, and threats to kill humanity. Ouch, not a good look.
This is why Altman and Amodei are panicking. Both of these guys have shown numerous times they have zero regard for others as long as it serves their own interests. They know they can't win long term AND be attractive high margin businesses, so they are begging for regulation.
Nah, I don't buy for a minute that these guys care about you or your safety.
Generation FOMO. Nobody needs even 3 of these active at the same time. It’s just people having zero control over their finances and consumption.
Average Joe hates having a choice, because it makes him accountable for his decisions.


5
545


$NTDOY $NTDO.NE
Nintendo is superior in every way to Sony when it comes to nurturing IPs.
1. A lot of characters they treated like first-party were just purchased by exclusivity contracts. Final Fantasy (Cloud), Crash Bandicoot, Eve from Stellar Blade, and Sora are fantastic examples.
Purchased exclusivity is just different than the genuine IP creation Nintendo does. Nintendo has a lot of patience and tries new strategies to get an IP big or bigger. Franchises like Fire Emblem, Xenoblade, Splatoon, or Donkey Kong got a much bigger focus in recent years and it paid off massively for them.
2. Polarizing their own icons. Whatever one’s opinion is on Joel and Ellie, Kratos, or Aloy, there was huge discourse about their character development and/or redesigns. Whether one supports one or the other side doesn’t matter, but this kind of polarizing is rarely healthy for an IP, just ask Disney with Star Wars.
You don’t see that with Nintendo. They don’t purposefully use A-list IPs to set messages about diversity or redesign them for a "modern audience”. While Sony studios and Disney attack their own fans with stuff like “don’t play/watch it, it wasn’t made for you,” Nintendo’s focus has always been to create experiences for their fans and a big family focus.
3. Opening their IPs to PC. While expanding the core audience and making additional money, it’s often scarcity that drives the value of IPs. With those moves, Sony disconnected those IPs from their core ecosystem, devaluing them for their existing PlayStation audience. You are now getting the best The Last of Us or God of War experience on PC, not on PlayStation.
Apart from emulation, there is no way to play Zelda or 3D Mario anywhere else. You want to play with Nintendo IPs? You’re going to join the Nintendo club, it’s that easy.
4. Game visuals. While Sony goes for a hyper-realistic style in a lot of their games like Uncharted and TLOU, Nintendo goes for a more cartoonish and animated style. While Sony’s style works great for movie adaptations, it’s in my opinion a lot more versatile and easier to monetize the cartoonish style.
You see supermarkets and toy shops full of Mario, Pokémon, Stitch, or Mickey Mouse, alongside Harry Potter, Marvel, and Star Wars. That realistic style Sony goes for just doesn’t work that well in that retail environment.
5. Most people get introduced to IPs like Mario, Pokémon, Zelda, and Animal Crossing at a very young age. They basically grow up with those IPs. While there is probably a gap somewhere between 14-20 years old, it’s much easier to reintroduce somebody to an IP they were exposed to from a young age.
You can clearly see that effect when looking at box office numbers from Inside Out 1 to 2, or the animated Lion King to live-action. A lot of Sony’s IPs are aimed at adults or teenagers (TLOU, Killzone, God of War, Horizon, Uncharted), from which point it’s much more difficult to build lifelong loyalty.

>Sony wants to create new character IP to rival the likes of Nintendo, Sega and Sanrio
PS tried this many times and always abandoned these characters
No one is going to be loyal to these franchises cause they know they will be shelved
2
1,663


I can confirm this. While I am not necessarily bearish on $NFLX, I have a lot of exposure to Chinese people on a regular basis, including a lot of Chinese women.
This “short drama” obsession is absolutely insane. If this spills over into Western culture, people have no idea what’s going to hit them. This will make Reels look like legacy TV for women.
I agree with @the_zack_zhu, and I’m not sure if $NFLX is a net gainer of engagement from today on. I would rather bet on $META (they will adapt quickly somehow, as always), YouTube, or TikTok gaining further engagement from streaming services.
Interestingly, META is already pushing its content to be ready for smart TVs. If that short drama shit hits, META could be the most obvious beneficiary.
Which doesn’t mean that $NFLX isn’t cheap. I think the valuation makes up for a lot of risks right now. I think the stock will work from here, but yeah, betting on their long-term engagement growth is a tough call for me.

Since Bill Ackman is back in $NFLX, I think anyone looking at Netflix also needs to pay attention to what's happening in China, where "short drama" is eating the lunch of Netflix-like services.
Short drama is basically TikTok on steroids.
Hongguo Short Drama, owned by TikTok's parent company ByteDance, launched in 2023 and has now surpassed 120M daily active users. The average user spends 2 hours a day on the app.
But the more interesting part is what happens when you combine short drama with AI.
With models like ByteDance's Seedance, the cost and time required to produce video content are dropping. Tons of actors, studios, and traditional production teams are being replaced by AI.
I think this trend will eventually come to the Western world. In Taiwan and Southeast Asia, I've seen an increasing amount of AI-generated short drama over the past year. And it's becoming increasingly hard to distinguish from traditionally produced content.
I think it's only a matter of time before it starts influencing the Western film and TV industry.
My thoughts on why it's still less prevalent in the U.S. and Europe:
a) a more anti-tech environment
b) a much deeper and stronger movie and TV legacy
Part of Netflix's current edge depends heavily on its ability to produce traditional media at scale. AI could diminish a huge part of that edge.
And with attention spans getting shorter and shorter, looking at TikTok, Reels, YouTube Shorts, and what's already happening in China, it's hard not to be pessimistic about the future of Netflix or any platform that relies heavily on professionally produced traditional content.
Now every few seconds, a new AI-generated short drama is being produced, while both the frequency and quality continue to improve rapidly.
It's like the battle between traditional media and internet UGC all over again. Except this time, UGC doesn't even need a human creator behind every piece of content.
I will not fight against the trend.
Great post from @ThierryBorgeat
In my opinion $META could really end up being the cleanest big tech story right now. In theory, they can just pull back, focus on their core business, and use the improvements they’ve already achieved.
The other players seem to be too deep into it to pull out. And if it really crashes down, Meta won’t end up with a giant unrealized backlog or customers pulling back.

I talked to hundreds of investors.
Everyone knows this is crazy. But no one cares.
Because leaving the party too early or telling their clients they’re not part of the next big thing is worse.
People have simply stopped investing; they’re just riding the wave. They literally don’t care.
Because what if this time really is different?


I saw some discussion on X about $V and $MA in countries like Brazil, where they are applying alternative payment rails to be “independent” from $V & $MA.
The Pix payment system in Brazil sounds scary for $V & $MA until you realise:
1. Brazil still uses $V & $MA technology for payment cybersecurity.
2. Mastercard recently partnered with Juspay in Brazil to roll out Click to Pay, bringing its tokenization and biometric security to the checkout experience. This adds the security layers that pure instant payments lack.
3. Mastercard Gateway directly integrates Pix, allowing merchants to accept Pix QR codes. When a global merchant uses this service, Mastercard collects a fee as the payment gateway. They literally earn money orchestrating the Pix transaction itself.
4. Pix doesn't solve the fundamental need for credit and consumer protection. It acts more as a cash and debit replacement. Brazilians still heavily rely on credit cards for loyalty programs and chargeback protections, something Pix inherently lacks since its instant transfers are final.
5. It’s not a zero-sum game. Brazilian e-commerce is projected to hit $187B in 2026. Pix currently handles 44% of online purchases, but credit cards are right behind with a 40% market share. By 2028, online credit card sales in Brazil are expected to reach $183B, growing at a solid 6% CAGR.
The biggest flaw in the bear case is assuming a static market. Pix actually expanded the total addressable market by bringing 70 million unbanked Brazilians into the financial system within its first two years. This leaves $V & $MA with a significantly larger consumer base to convert than they had before Pix launched.
I think this is something bears in general miss with these market dynamics. Same for $UBER & $BKNG, and similar companies that have been "disrupted" 10x already regarding sentiment, but end up with healthy, growing top and bottom lines. A lot of these dynamics expand the overall market instead of disrupting it.
I don’t know about you, but it makes me extremely bullish to know that one of my investments is continuing to grow in markets that are exploring and applying alternative payment rails. So you can see the actual bear cases playing out, and MA/V are still taking their royalty like cut on these growing economics.
$AMZN will be there very soon. At $775B TTM and growing in the mid-to-high teens currently, it’s not a matter of if for AMZN, just a matter of when. It will probably happen in Q1 2028 on a TTM basis.
Coincidentally, AMZN will probably also be the biggest competitor to Starlink with Amazon Leo coming online.

596
I posted this analysis of $AMZN earlier this year. It is still relevant in my opinion. Now it seems like most people have recognised that AMZN is an AI winner.
But still, I do believe people are not bullish enough on this name. This will be one of the biggest winners from MULTIPLE secular trends.
AI - AWS distribution is already massive, and AI revenue is going crazy.
Cloud Computing - Not just the servers AMZN's chip business is crazy and would be an industry leader on day 1 if they decide to go aggressively into the market.
Robotics - This one will be a huge profit driver for the retail part, and already is.
Digital Advertisement - This is still a secular trend, and it will only accelerate with AI targeting.
E-Commerce - I do believe people do not appreciate enough that e-commerce penetration still has a major runway of growth, especially in international markets.
Autonomous Vehicles - Analogous to robotics, self-driving vehicles will play a massive role in the delivery networks, and there is also Zoox.
Satellites - Project Leo is shaping up to be a competitor for Starlink, which is SpaceX's profit driver.
General shift in the business mix:
I think the margin mix shift is vastly underestimated. While the low-margin businesses themselves are getting higher margins thanks to automation and AI, the higher-margin businesses are still growing significantly faster than the low-margin ones.
What happens to AMZN's economics if AWS and Ads become a much larger part of the business, while Retail becomes smaller - while retail margins are also improving?
Also, all significant businesses are accelerating revenues: e-commerce (including third-party sellers), subscriptions, advertising, and AWS. The trend is insane, and as we move forward, the market has no choice but to recognise this.
People last year asked me a lot when $GOOGL hit $200 if it’s still a buy. Now look where we are. I believe AMZN could be a similar story. I wouldn’t be surprised if we see a $5T market cap not too far in the future.
I am still very bullish, and while I recognise that everybody is bullish now, I believe people are still not bullish enough on this ticker.
After posting about my bullishness on $GOOGL and $META over the last week I think it just makes sense to give a few thoughts about $AMZN as well.
I think the elephant in the room is the massive capex guidance of over $200B and the perceived undisciplined capital allocation. I think this is especially coming from the fact that its peers $MSFT GOOGL and META are all doing buybacks and dividends while AMZN is still diluting shareholders with massive SBC.
In my opinion this is a bit missing the forest for the trees and I like to think about it from a different perspective. The SBC issue is already addressed by the management and SBC peaked in 2023 with $24B and two years later today it is at $19.5B. That is a noticeable reduction in only two years. While the other three are still increasing the number YoY AMZN is actively reducing the total SBC number.
Considering that these companies are spending every available dollar building out their data centers right now and even taking on debt to stay ahead in this race I honestly prefer AMZN way of tackling the SBC itself than to just increase buybacks to LOOK good. The effect is more sustainable as well and will especially appreciate later when and if AMZN starts doing actual buybacks.
By the way AMZN is the only hyperscaler to actually decrease the SBC itself while the others are still increasing the total SBC.
In terms of capex I might be naive but I honestly believe those companies when they say the risk of underspending is bigger than the risk of overspending. It is not like I trust management blindly but these companies have dominated their industries for decades at this point and all decided at the same time to pour as much money as possible into their data centers and infrastructure.
I refuse to believe that these highly dominating companies are led by complete idiots and three out of four hyperscalers are still led by their founders or have their founders still heavily involved.
I don’t think people appreciate enough that AWS is an above $120B business and just re-accelerated the top line back into the 20s. AWS will generate north of $200B in revenues probably before the end of 2030 and people are still questioning their capital allocation.
What I specifically like about AMZN vs GOOGL and MSFT is that it is very clear that AWS is increasing the overall business quality. It is not only the fastest growing business segment with ads it is also the one with actually the best margins. So every single year the business quality of AMZN increases and the margins will reflect this.
GOOGL and MSFT are already coming off of high quality businesses with Search and Office. While GCP and Azure are phenomenal businesses it is for GOOGL and MSFT more diversifying an already fantastic business and margin profile.
Meanwhile for AMZN it completely changes the game and continues to do so.
Five years from now AWS and Ads will make up a MUCH bigger share of the overall business and this WILL be reflected in the margin profile. And this is on top of all the potential margin expansion stories for the actual e-commerce business like robotics.
Looking at AMZN specifically I think this sell off is a gift by the market and I am here to take it and this is why I bought more shares this week. AMZN is not only a play on the future of AI it is also a solid infrastructure play providing a great market opportunity without taking on the terminal risk of a SaaS company right now.
$NTDOY $NTDO.NE earnings report: At first glance, it looks solid to me.
Hardware sales are not great but still good imo. Considering that a lot of the heavy hitters like Mario, Zelda, mainline Pokémon, and Smash are still to come, I think they’re doing a great job.
Unit sales is the most important metric for me to track because future revenues and profits, and literally the whole flywheel, depend on how many Switch (and new) customers they can convert to the new console.
Software sales are looking good - again considering that the heavy hitters are still missing. Important now for the future is that Nintendo is now not only able to sell the back catalogue of the Switch but also now building a back catalogue of strong 3rd-party games like Elden Ring, Resident Evil, Final Fantasy, and more.
Those 3rd parties and the online subscription will be real profit drivers in this generation, we are still not seeing the full extent of it.
The Mario movie performed well as expected, but it looks like the next Mario movie will slip below the top tier of $1B movies. But anyway, next will be the Zelda movie. I don’t expect that movie to perform as well as the Mario movies, but it will still have a positive impact on the Zelda IP.
Overall, Nintendo did not adjust their guidance. This was expected. The tariff refund is interesting. On one side, it’s a one-off income for Nintendo on the other side, they are not going to lower prices, so basically the profit margin of hardware sales is getting a slight tailwind, offsetting the chip shortage a bit.
Long term, I think margins will be fine anyway since the software part is the profit driver, not the hardware. For Sony and Microsoft, the hardware was a loss leader anyway for the last generations, while Nintendo was always able to turn a profit. While it’s not optimal, it shows the console business can be profitable even with loss-leader hardware.
I will take another look later, but so far I think it’s a good start to the new fiscal year.