

20+ yrs in finance. Ex-J.P. Morgan analyst. Stocks & businesses. Follow my daily stock notes. Here to share & learn with investors across industries. 👇
California, USA
Joined March 2013
- Tweets142K
- Following454
- Followers6K
- Likes55K




Grant Whitaker retweeted

32 years. No emotions. Just these rules:
📉-10% → Hold
📉-20% → Add 10%
📉-30% → Add 30%
📈+10-20% → Hold
📈+30% → Sell 10%
📈+40% → Sell 20%
📈+50% → Sell 30%
📈+60% → Sell 40%
📈+100% → Exit
This is the exact logic Buffett dropped in his early interviews ↓
Discipline > Emotion.
Risk control creates long-term returns.
When the price drops, buy more. Judge the business like a farm — by what it produces, not by the daily quote. Most people do the opposite and get scared when others are fearful. That
Save this. Validate later.
Grant Whitaker retweeted
$NVDA just got flushed to $125 on a volume spike.
Most retail is calling it panic selling and heading for the exits.
The same chart is what a lot of bigger accounts are quietly watching for entries.
This is the exact moment the gap between “I wish I bought” and “I actually bought” usually opens.
Are you selling the fear or sitting on your hands waiting for more pain?

Grant Whitaker retweeted
That $83 IPO price is a reference point, not a floor. The real test is whether buyers show up now that the debut-day hype has faded.
Grant Whitaker retweeted
Anthropic IPO: A $1.4T valuation—and investors still want in
Bankers have floated a $1.4 trillion valuation, putting Anthropic at roughly 40 times trailing sales. Amazon trades at 3.5 times; Alphabet at 7.3 times.
Reuters reports strong institutional demand, with retail investors eager to secure shares.
Many traditional investors remain skeptical of the price. My view: AI adoption is an inevitable part of technological progress. We’re still discovering what it can do, and I expect it to influence many industries in the years ahead.
Is $ANT on your watchlist? Drop your thoughts below—let’s compare notes.
#Stocks #Anthropic #Investing #Markets
Grant Whitaker retweeted
AI demand hasn’t vanished, but $1T in capex doesn’t guarantee $1T in returns. After NVDA’s $115.8B quarter, the next question is whether customers can make money on all that compute.
Grant Whitaker retweeted
I’ve been comparing notes with several well-known finance creators on X about $NVDA recent moves and what comes next for AI stocks.
We discussed which names could outperform, where we see downside risk, and what prices would make them worth buying. I’ll share the entry levels we’re watching in upcoming posts.
Join our group through the link below to exchange ideas with the creators involved and learn together.


Grant Whitaker retweeted
Wall Street assess the fallout from Nvidia’s spy scandal and what it means for AI stocks.
After this selloff, I’m watching customer financing: Nvidia provides financial support to parts of the ecosystem buying its hardware.
Evidence that customers can fund expansion with less support from Nvidia would give this recovery a much stronger foundation.


$SPY $QQQ — bulls are celebrating cheaper oil. CPI is about to check last month’s receipts.
Oil’s drop is helping sentiment, but today’s report covers October. Yesterday’s selloff in crude won’t magically rewrite those numbers.
That’s the awkward setup: the outlook can improve while the inflation report still looks ugly.
I’m watching core CPI and the 2-year Treasury yield. Softer core inflation with falling yields would give this rebound more support. Hot core inflation and rising yields could leave dip buyers holding the bag.
You can be right about inflation cooling next month and still get your 0DTE calls smoked today.
Follow for the post-CPI breakdown. Let’s see whether the bond market buys the rally.
#CPI #StockMarket

$NVDA could deliver strong earnings and still disappoint shareholders.
Investors pay for confidence in the people running a business, too.
Nvidia’s board has opened an independent investigation. It says it currently has no reason to believe company secrets or U.S. national security were compromised. The review remains open.
My concern: investors could pay less for every dollar of earnings while those questions hang around. No earnings downgrade required.
The more indispensable bulls say Jensen is, the harder it becomes to dismiss uncertainty around him.
A review that finds no business impact could help restore confidence. Until then, I’d want clarity on leadership and execution before calling a lower P/E a bargain.
Follow for my next $NVDA update. I’ll be watching the board’s findings and whether guidance changes.
#Nvidia #StockMarket
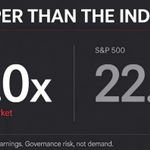
$NVDA is trading at 22x trailing earnings, just below $SPY at 22.8x. Didn’t expect to see that with earnings eight days away.
The board investigation adds uncertainty, so I get the selloff. But I don’t think the headline alone tells us much about demand.
I’m long. My 12-month target is $250, with a bear case around $150. Tempted to add here, but I’ll let the news settle first.

2
110
Nvidia's earnings grew roughly 60% this year.
The stock is flat.
And people are still calling this a bubble.
If that's what a bubble looks like, sign me up for more of them.
Two decades covering semis. I watched Cisco in 2000. I watched memory in 2018. I watched NVDA itself go from $330 to $108 in 2022.
People keep throwing around the word "bubble" this week. Let me define it properly, because the definition matters more than the opinion.
A bubble is when PRICE runs away from EARNINGS.
Cisco, 2000: price doubles, earnings barely move. Multiple goes UP. That's a bubble.
Now do the same exercise on NVDA:
Price today: $186.64
Trailing multiple: 23.3x
Same multiple last fiscal year: 37.5x
Earnings up ~60%. Price went nowhere. The multiple got cut almost in half.
You cannot have a bubble that compresses its own valuation while the business grows 60%. Those two facts are mutually exclusive. One of them has to give, and it won't be the earnings.
Here's what nobody on this app is talking about — the bounce on Friday, Nov 6. Look at the ORDER, not the size:
Cloudflare +9.91%
TSMC +6.33%
Micron +5.12%
Nvidia +2.78%
The market did not buy "AI." It bought CHEAP.
Money went into the names that got gutted hardest, not into the leader. That's not conviction, that's bottom-fishing.
And it tells you exactly how the repair trade works: NVDA is the most crowded, most institutionally-owned name in the entire complex. It will be the LAST to heal, not the first.
Which is the whole opportunity. You buy the leader when it's boring, not after it's already up 20% and everybody feels safe again.
Now the part where I don't cheerlead.
The risk was never AI demand. Anyone telling you demand is rolling over hasn't read an earnings call in two years.
The risk is two dates:
Dec 9 — FOMC. Odds of another hike sit near 80% after that 165K payroll print.
January — hyperscaler 2027 capex guidance. If they trim, the entire chain re-rates down. Me included.
23x does not protect you from a capex cut. Nothing does. I'll say that plainly.
But understand what actually sold off on Nov 5:
Retail, selling at the fastest pace since March 2020.
Systematic funds, with UBS estimating $100B+ of forced selling Friday.
That's forced selling. Not informed selling.
And here's the distinction that decides this trade: on Nov 5, not a single GPU order was cancelled. Not one. The trigger was an election result and a regulatory headline — a POLICY risk, priced as if it were an ORDER BOOK risk.
Policy risk gets priced in a week. Order book risk takes two quarters to show up in the numbers.
The market just priced the first one as if it were the second.
My call, on the record, no hedging:
$250 in 12 months. That's 31x trailing earnings — a multiple this stock carried for most of the last two years, now applied to a materially bigger earnings base.
If I'm wrong: $150.
Roughly +34% against −20%. Call it 1.7 to 1.
I've been in this industry too long to call that a coin flip.
$NVDA $SPY $QQQ #AI #Semiconductors
Short it if you disagree. Screenshot this. See you in a year.

4
1
315
AI's most critical component fell 17.5% in ONE day.
Its P/E is now 9.19.
Nine. Not ninety. Nine.
Let me explain why this doesn't make sense 👇
Micron (MU) on Nov 5:
• −17.46% in a single session
• −22% since Oct 31
• Now at $690
At $690, the market is paying 9.19x trailing earnings for the company that makes the HBM memory inside every AI accelerator on earth.
HBM isn't a "nice to have". It's the physical bottleneck. No HBM, no AI training. Demand isn't slowing — the BUILD OUT PACE slowed.
Here's the tell nobody mentions:
MU's earnings went UP as the stock went DOWN.
PE compression like this is what happens when price collapses faster than fundamentals.
What's actually priced in right now?
• Complete halt of data center capex
• A recession
• AI demand rolling over
One of those might happen. All three won't.
Repricing math (assumption, not prediction):
→ At 12x earnings: ~$901
→ At 15x earnings: ~$1,126
Versus $690 today.
The bear case: memory is cyclical. Always has been. If the AI capex cycle truly breaks, MU goes to 6x and stays there.
The bull case: you just got the AI supply chain's most irreplaceable piece at a multiple usually reserved for dying businesses.
I know which side I'm taking.
$MU $NVDA $SPY #Semiconductors #AI #StockMarket
Would you buy 9x AI right now? 👇

The AI trade just got its first real margin call.
Nov 5, 2026 — one session:
• Nasdaq −5.52% (worst day in 19 months)
• Philadelphia Semiconductor Index −12.25%
• $2.9 TRILLION wiped off the S&P 500
• VIX +70%
Two days earlier the market was celebrating a midterm election.
Six minutes after the open, every cent of that gain was gone.
What actually broke it — in order:
1. Democrats swept the midterms. AI regulation and data-center restrictions suddenly became a real risk. UBS: ~30% of 2028 US data-center capacity could be delayed.
2. Retail investors ABANDONED the buy-the-dip playbook. Fastest selling since March 2020.
3. October jobs: +165K vs +65K expected. December hike odds: 80%.
So here's the honest question:
Is this capitulation — or just the first chapter?
Bulls say: "AI demand never changed, only the buildout pace."
Bears say: "The earnings model that justified 27x is dead, and nobody knows where it resets."
My read: this isn't the end of AI. It's the end of buying AI on narrative.
From here the market prices COST, not story.
Cash-flow AI and debt-funded AI are about to be treated very differently.
CPI Tuesday decides the next move.
$NVDA $AMD $TSLA $SPY $QQQ $INTC #StockMarket #AI
Which side are you on below 👇

4
279
$U is getting my attention. $PLTR would be next on my list.
$U: Vector revenue grew 126%, and Unity delivered its first GAAP-profitable quarter since going public. That gives the turnaround some substance. Reported takeover talks add interest, but I wouldn’t buy assuming a deal happens. Results · Reuters
$PLTR: Revenue up 96%, U.S. commercial up 148%. Those numbers keep me interested after the pullback. My concern is how much growth investors have already paid for. A great business can still be an expensive stock. Results
$TSLA: FSD subscriptions rose 67%, but operating margin was just 2.6%. I see the appeal of the autonomy business. I’d still want improving profits before getting aggressive. Results
$CRWV: November 10 earnings are the next big test. I’ll be watching financing costs, spending and how quickly capacity turns into revenue. This is the most speculative pick of the four for me. Earnings date
#Stocks #Earnings

1
336
The midterm trade is splitting in two.
Democrats won Congress. Trump remains president. Policy expectations are moving faster than actual legislation.
Here’s how I’m looking at these five:
$CNC — One of the clearer beneficiaries of hopes for stronger ACA and Medicaid support. That could improve the coverage outlook, but medical costs and reimbursement rates still decide the earnings story. I’m constructive. The $67.49–$70.21 gap is worth watching on a pullback.
$FSLR — A friendlier Congress could improve sentiment toward domestic solar manufacturing and clean-energy incentives. But the initial post-election gap already filled on Nov. 5. A sustained reclaim of $200 would make the setup more convincing.
$VST — Texas election results raised concerns about data-center approvals and future power demand. Yet the company’s Nov. 6 results showed ongoing-operations adjusted EBITDA growth above 50%, with a higher midpoint for its 2026 outlook. That keeps me interested. Strong current earnings and uncertain future development can coexist. The $128.07–$136 gap remains an overhead reference.
$CRWV — The concern is deployment: tougher approvals can delay capacity, revenue and cash flow. An election doesn’t automatically cancel existing contracts. There’s recovery potential if delivery and financing hold up. I’m watching $50 for a reclaim and $40.58 as the recent low.
$DJT — The most direct political-sentiment trade of the group. A rebound is possible, but I don’t see a clean policy tailwind here. $4 is the round-number test; $3.80 is the recent low.
My preference: CNC and FSLR for the policy setup, VST for a recovery backed by earnings. CRWV needs execution confirmation. DJT is the speculative trade.
Price levels: Nov. 5 close.
VST earnings update: Nov. 6.
The election matters, but it isn’t the only thing moving these stocks.
#Stocks #Midterms #StockMarket

1
183
Our trading group has been going for eight years. People from all walks of life, sharing ideas and talking markets.
I’ve made enough to live comfortably. These days, I get more satisfaction from helping someone else figure things out and improve their trading.
That’s why I keep doing this. I’d like the experience I’ve gained to be useful to more than just me.
If you enjoy discussing stocks, comparing ideas, and hearing a different perspective, you’re welcome to join us.
DM me “GROUP” and I’ll send you the details.


