

Ex @KyberNetwork @KrystalDeFi. Builder at @VemoNetwork and @Brownfiamm. Running a LP community: https://xitter.cf/t.co/EjLHd0iHpw
Joined April 2021
- Tweets2.5K
- Following1.9K
- Followers1.7K
- Likes4.6K


I know. Actually this is inventory discrepancy, not IL in bonding curve AMMs. I just use "IL" term so normal LPs understand what I'm talking about right away.
Many people think that @metricxyz PropAMM is the holy grail of liquidity provision with high capital efficiency and no IL risk, just like bonding-curve AMMs such as CPMM/CLMM/DLMM.
But wake up, Tinker Bell.
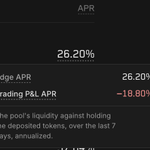
The reality is: by LPing on Metric, you still get IL as usual (even higher than a normal CLMM if the curator doesn’t do a good job), and you’re also exposed to other risks like stale prices, rebalancing losses, and bad or malicious quotes.
At the end of the day, there’s no free lunch in LPing at all.
*In the picture, Trading P&L APR (the IL) of ETH/USDG pool on Robinhood is -18.80%.

Should be happy when $SPY goes down. Because it will go back to the track anyway with some extra fees for you.

Day 31 of LPing on @giga_dex
$SPY is down -1.77% at the time of writing.
My initial investment of $1,975.04 would be worth $1,940.08 if I had just bought $SPY
My LP is currently worth $1,954.06, meaning I have outperformed full porting $SPY by 0.71%
And I have earned ~$7.52 of fees on this position - 0.38% in 4 days!
Do more with your stocks on @giga_dex!
jasonvu.tech (🦇🔈 ,💧,🐻⛓️) retweeted

ETH-USD pools highlight on BrownFi
ETH-USD pairs are the most common LP pairs across EVM chains. LPs are always chasing the same thing: low IL, high yield. Here’s how BrownFi delivers it across chains 👇
🔹 ETH/USDG (@RobinhoodCrypto): 68.89% APR
🔹 ETH/USDC.e (@berachain ): 22.15% APR
🔹 ETH/USDC.e (@hemi_xyz ): 29.58% APR
🔹 ETH/VUSD (@hemi_xyz ): 43.24% APR
🔹 ETH/USDC.e (@LineaBuild , auto-compound): 72.58% APR
As you can see, all 3 oracle-based pools from BrownFi are offering low IL (the pool on Linea even delivers “positive” IL, outperforming a Buy & Hold portfolio) while returning juicy yields to LPs.
As an LP, you don’t need to monitor positions manually. Let BrownFi handle the “low IL, high yield” part for you now:
👉 app.brownfi.io/pool

Ve33 model envolves over time.

A lot of LPs just farm and dump.
$UP is changing that by incentivizing people to trade their emissions for locked veUP with a bonus.
Up is literally solving a lot of problems that old veDEXs faced. Much better team, product, and totemics imo.
Consider this case as DCA-out UNI token. At the end of the day, you still need to realize profit from alt-coin to BTC, ETH or stablecoins right? Don't hold it forever.
Using Kyber Zap to Take Profit in UNI Token
Take a look at the UNI/ETH chart on Uniswap (Arbitrum). ethereum:0x1f9840a85d5af5bf1d1762f925bdaddc4201f984 got a nice run during @RobinhoodCrypto chain hype last September, going from 0.002 ETH all the way up to 0.004 ETH.
Then Robinhood stopped its gas sponsorship program, meme tokens dropped, volume on the chain fell, and the hype around UNI faded with it.
So I decided to lock in some profit into ETH. Looking at the chart, UNI/ETH hasn't been able to break out of the (0.002;0.005) range for over 4 years. I jumped into this range using @KyberNetwork zap function, which swapped roughly 85% of my UNI to ETH and added it to the position in one transaction. No manual math, no multiple steps.
Then 02 scenarios can play out from here:
⚡️Scenario 1: If UNI price drops, my ETH will DCA-in more UNI. And I'm also happy with that.
⚡️Scenario 2: If UNI price pumps, it's historically rare for it to break out of the range and stay above 0.005. The data is on my side.
Either way, I'm earning 30–42% fee APR while I wait.
LPing isn't about betting on direction. It's about planning for every scenario.


Getting 40% APR on ETH/USDG on Robinhood is tough these days. BrownFi gives you 70% APR with low IL and zero range monitoring required.

Take a look at the ETH/USDG pair on BrownFi vs. Uniswap.
ethereum:native plunged 4.95% today, pushing most Uniswap positions out of range (APR 40.55% for active ranges only). BrownFi held up well with low IL comparable to Uniswap V2, plus 70.12% in $GIGA emissions.
👉 Add liquidity, enjoy low-IL-high-efficiency with @giga_dex propAMM (powered by BrownFi) now: gigadex.fi/pool/0x9fae770e44…


Time to get back to Berachain though.
If you're not obsessed with chasing fee APR (]and risking IL, you might want to provide liquidity to the ETH/USDC.e pool on @berachain .
This pool offers almost no IL (LPing vs. HODL = -1.75%) while earning 21% in berachain-bera:native emissions.
👉 ETH/USDC.e pool: app.brownfi.io/pool/80094/0x…

LPing is almost reaching saturation 🤔
In tradfi, fee reduction is the worst tactic to compete with others. Competitors fight each other by cutting fees to attract users and volume, but they also cut their own margin. Good for users, but at the end of the day, none of those exchanges win.
But in the on-chain LPing game, fee reduction seems like the only choice DEXs have right now to suck up volume.
Take a look at the swap fees of ETH/USDG from 3 different DEXs on Robinhood:
▶️ @Uniswap : 0.01%
▶️ @giga_dex : 0.005%
▶️ @uponrh : 0.0087%
All 3 are offering swap fees way lower than a CEX, which normally sits around 0.1%.
And according to ETH annualized volatility at 48% (Deribit stats), if you play a safe ±50% range strategy, you only get approx 10-15% APR. That's acceptable, and I believe this is the final backstop for the LPing game. We're almost at equilibrium.
If these platforms keep lowering fees below current rates, I'm afraid LPing just isn't worth it anymore. LPs will remove their positions, and no one wins.

Mix of Lping Strategies (Day 138)
Time to catch the dip?
Yes, but in LPing style.
My HemiBTC/VUSD position has earned me 42 USDC in incentives on Hemi so far.
I harvested the incentives and then set up a single-sided ETH/USDC position with a range of $2,000–$2,590.
Unrealized PnL = $281 (22%)


Mix of LPing Strategies (Day 115)
You may wonder:
"Hey Jason, I see you writing a lot of content about LPing. Why don't you show us how you apply it in reality to earn real profits? Numbers speak louder than words when it comes to whether your strategy works or not."
Yeah, this inspired me to take on the ultimate challenge with a $1,050 initial capital ($1,000 in USDC + $50 worth of ETH for gas fees). I am calling it the "Mix of LPing Strategies" challenge. I will either raise this to $10,000 or crash it down to $0, only time will tell.
During this challenge, I won't be stuck with just one single strategy. Instead, I will have the flexibility to switch between CLMM, oracle-based AMMs, trading, incentive farming, staking, and more.
👉 My entire LPing diary will be recorded live on X and tracked in a Google Sheet here: docs.google.com/spreadsheets…
👉 Or you can track my wallet on Debank here: debank.com/profile/0x0f45cd4…

And here as well: xitter.cf/JasonvuTech/status/210…
How KyberSwap protects your rate twice: off-chain, then on-chain
Aggregator quote spoofing is real. 0x just published the data: of 84,163 Uniswap v4 hooks they scanned, they classified 54% as malicious. In the worst cases, users received up to 50% less than the quote showed.
Well, I agree on the diagnosis. But I disagree on the cure.
The problem isn't hooks. It's that quoting happens off-chain, before your trade settles.
A hook can show a tight quote to win the route, then widen the spread before execution. So can a PropAMM. So can a sandwich attack. So can an LP pulling JIT liquidity. Every one of these exploits the same gap: the router decided seconds ago, and your money moves now.
Filtering pools doesn't close that gap. It narrows your liquidity and punishes good hooks along with bad ones.
However, @KyberNetwork solves this with two layers:
1️⃣ Layer 1 — Dynamic Trade Routing (off-chain):
- Scans every pool and DEX on the chain
- Splits your trade across the best combination
2️⃣ Layer 2 — Smart Settlement (on-chain):
- Sends backup candidate pools along with your transaction
- The contract compares them at the moment of execution
- Executes whichever actually pays most, right then. This is not about prediction, but about measurement
Here's a real example on Base:
- User demand: 662,820 BASECAT → USDC
- One leg was routed to a vanilla v4 pool that, at execution, would have paid 0.130484408 ETH
- Smart Settlement compared it on-chain against a hooked v4 pool paying 1.116392138 ETH (8.5x more) and replaced the bad pool with the better one.
- The trade delivered 13,241.92 USDC against an 11,487 USDC floor. Without that on-chain switch it would have dropped below the floor and reverted outright
- tnx hash: basescan.org/tx/0x80a1d9a95b…
⚠️ note: On this transaction you'll see an [execution reverted] label, which can be confusing. That's simply Smart Settlement rejecting the vanilla Uniswap v4 candidate and executing the better one.
In general, you can't fix quote-time routing by curating the quote. You fix it by deciding on-chain, inside the transaction, at the moment your money moves.
🗒️ For further reading:
- Uniswap v4 hooks were a mistake (published by 0x): xitter.cf/0xProject/status/20995…
- Go with any hook. Settle with the good one (published by KyberSwap): xitter.cf/KyberNetwork/status/21…
- Kyber Dynamic Trade Routing docs: docs.kyberswap.com/developer…
- Kyber Smart Settlement docs: docs.kyberswap.com/developer…

