





Pinned Tweet
shopify is STEALING $5,000,000+ from ecom people EVERY SINGLE DAY
frozen accounts
paused payets
banned merchants
they’re WORSE than Netanyahu’s PayPal
so i put together a 38-page guide on how to AVOID getting hit with this BS
like + comment “SCAMIFY” and i’ll send it to your DMs
(must be following + RT for priority access)
You've been researching high-risk processors and alternative platforms and you're overwhelmed by the options and conflicting advice from people who've never actually run a business in your category.
Let me simplify this for you.
Proper payment infrastructure for a supplements, peptides, or CBD brand has three layers.
Layer one is your primary processor - a high-risk specialist who understands your industry, accepts your risk profile, and won't panic when your monthly volume fluctuates or your chargeback rate spikes temporarily. You'll pay 4-6% plus per-transaction fees, but you'll have stability.
Layer two is your backup processor - a completely separate merchant account with a different acquiring bank, already approved and tested, ready to handle volume if your primary has issues. This isn't optional, it's insurance.
Layer three is your platform separation - your website hosting and your payment processing should never be controlled by the same company. When Shopify bans you, you lose everything. When your processor bans you but your site is on WooCommerce or BigCommerce, you switch processors and keep operating.
The merchants who build this infrastructure spend more upfront on processing fees and platform costs. They also sleep better at night and don't have panic attacks every time they log into their dashboard.
DM me "SETUP" and I'll help you build the exact infrastructure your business needs.
Jericho
3
7
499
You know you need to get off Shopify Payments. You know you need a high-risk processor. You know your current setup is a liability waiting to explode.
But you haven't done anything about it because the migration seems overwhelming and you're terrified of breaking something that's currently working.
I get it. You've got revenue coming in, customers who expect seamless checkout, and a thousand other priorities competing for your attention. The idea of rebuilding your payment infrastructure while simultaneously running your business feels impossible.
Here's what I want you to understand - the merchants who wait until their accounts are frozen to start exploring alternatives discover this information when it's already too late. They're making decisions in crisis mode, rushing implementations, and accepting whatever terms they can get because they have no leverage.
The merchants who migrate proactively? They negotiate better rates because they're not desperate. They test new systems thoroughly because they have time. They train their teams properly because they're not putting out fires.
And most importantly, when something eventually does go wrong with one processor - because something always eventually goes wrong - they have backup systems already in place and approved.
The best time to fix your payment infrastructure was before you needed to. The second best time is right now while you still have access to your money and your data.
DM me "MIGRATE" and I'll walk you through exactly how to transition without disrupting your business with no upfront cost
Jericho
2
433
You built your entire business on a single platform and you probably never thought twice about it.
Your website, your payment processing, your customer data, your order management, your email lists - everything lives in one place because it was convenient and the integration was seamless and you had a million other things to worry about when you were getting started.
But here's what that convenience actually means in practice.
One algorithmic decision can shut down your entire operation overnight. Not just your payment processing - your entire business. Your subscriptions get canceled, your customers can't rebill, your revenue stops, and you can't even export your data fast enough to rebuild somewhere else.
I've seen store owners lose $500,000 in active subscriptions because an automated system decided they looked "risky" despite having a 0.07% chargeback rate and six years of clean processing history.
The platform that made it easy to start your business also made it easy for them to end it whenever they want.
And buried in those terms of service you agreed to without reading is language that says they can terminate for any reason, they have no liability for business interruption, and all decisions are final.
Your money isn't actually yours until it hits your bank account.
DM me "RISK" if you want to know how exposed your business really is.
Jericho
3
5
447
Every single week I watch successful store owners lose access to $200k-$500k.
They log into their dashboard expecting to see revenue for the week but instead they're greeted with a message that their account has been flagged, their payouts have been paused, and they need to "verify" their business before accessing their own money.
The $200k+ they were counting on to pay suppliers and run payroll is completely inaccessible.
That's the greyhat truth almost NO ONE tells you about ecom.
Those same patterns that show business success are exactly the patterns that trigger fraud detection algorithms.
These patterns tend to be:
Seasonal sales spikes/influencer partnerships.
Viral marketing campaigns that dramatically increase traffic.
Successful product launches that generate concentrated order volume.
All of these look statistically similar to the patterns that actual fraudsters create, which means the better your business performs, the more likely you are to get flagged.
And once you're flagged there's no phone number to call or human to explain your situation to.
Support genuinely sucks.
I’ve seen brands lose chunks of their money completely because of this.
And if you're running supplements it’s even wrose. Peptides, CBD, or any product in a "sensitive" category, you're operating on borrowed time whether you realize it or not.
All of these niches get screwed by processors at one point.
But you can prevent it by being smart.
- Jericho
p.s. - i’ve helped multiple brands avoid/navigate these exact situations, DM me "AUDIT" and I'll show you exactly where your payment setup is vulnerable
1
3
376


once upon a time acai berries became the hot "superfood"
oprah mentioned them
dr oz talked about them
celebrities posted about them
suddenly everyone wanted acai
nutra ops even created fake news sites:
"Oprah Loses 40 Pounds With This One Trick"
picture of oprah + acai berry bottle
except:
- oprah never endorsed it
- dr oz never recommended it
- all fake
but customers believed it
they scammed with "free trials" too lol
"Try Acai Berry FREE - Just Pay $4.95 Shipping"
customer signs up thinking:
"cool free trial"
buried in terms (tiny text):
"by accepting free trial you agree to monthly shipments at $89.95/month until cancelled"
this is called "negative option billing"
you're automatically enrolled
unless you ACTIVELY cancel
most people:
1. didn't read terms
2. forgot about trial
3. didn't know they were enrolled
14 days later:
$89.95 charged
30 days later:
another $89.95
and only then do these mfs realize
and this was legal too (buried in terms)
THE PAYPAL/STRIPE LOOPHOLES
early 2000s payment processors didn't catch this
nutra ops would:
- use vague business names
- describe as "health supplements"
- hide the rebill structure
paypal approved them
stripe processed them
didn't realize the scam until complaints piled up
THE CALL CENTER NIGHTMARE
when customers called to cancel:
1. put on hold for 30+ minutes
2. transferred multiple times
3. told "you have to email"
4. email goes unanswered
5. meanwhile keep getting charged
it was designed to make cancellation impossible
some ops literally:
- ignored all emails
- had no working phone number
- made cancellation take months
one brand doing this could literally make:
100,000 "free trial" signups
70% don't cancel in time (70,000 people)
70,000 × $89.95 = $6.3M first month
then recurring:
50% stay subscribed (don't know how to cancel)
35,000 × $89.95 = $3.1M/month ongoing
$100M+ per year per brand
insane
eventually the customers found out ofc
called their bank
disputed charges
chargebacks flooded in
5-10% chargeback rates
some brands hit 15%+
payment processors panicked
stripe started banning:
"any acai berry or colon cleanse products"
paypal followed:
"negative option billing prohibited"
so overnight thousands of accounts were banned
millions were in holds
THE CLASS ACTION LAWSUITS
law firms smelled blood:
class action lawsuits against:
- fake celebrity endorsements
- deceptive billing practices
- impossible cancellation
settlements:
$10M-50M per brand
some founders went bankrupt
eventually the FTC stepped in:
filed complaints
demanded refunds
seized assets
made examples of biggest operators
some got:
- permanent bans from supplement industry
- court-ordered refunds
- personal liability
THE AFTERMATH
entire rebill nutra industry collapsed
what worked:
- finding trending products
- using celebrity hype
- free trial offers
what killed it:
- fake endorsements
- deceptive billing
- impossible cancellation
- ignoring complaints
if they had:
- honest advertising
- clear billing disclosure
- easy cancellation
- responsive customer service
could still be operating
realize that rebill model isn't illegal though
subscription products are fine
but:
IMPOSSIBLE cancellation = scam
FAKE celebrity endorsements = fraud
HIDDEN billing terms = deceptive practices
the difference:
legitimate subscription:
"$29.95/mo for supplements"
"cancel anytime easily"
scam subscription:
"free trial!" (secretly $89.95/mo that’s impossible to cancel)
nutra ops went full scam
got destroyed
this messed up the current state of nutra
but it still exists
just slightly differently:
- clear billing disclosures required
- easy cancellation required
- no fake endorsements allowed
- processors watch closely
margins are lower
but it's sustainable
going too black gets you sued
but pretty much:
subscription models print money
free trials convert like crazy
celebrity hype sells
just avoid fake endorsements and stuff
stay honest enough to survive
- jericho
3
594
october 1, 2025
visa's VAMP enforcement just started
if you're running peptides, nutra, CBD/THC, or supps
your payment processor is about to fuck you
here's what's actually happening:
THE VAMP BOMB
visa acquirer monitoring program:
new fraud/dispute tracking system
stricter thresholds than ever
$8 fee per dispute over limit
starts october 1, 2025
most ecom brands have NO idea this exists
THE NEW THRESHOLD
VAMP ratio limit: 2.2%
meaning:
if more than 2.2% of transactions = disputes/fraud
you're in VAMP program
$8 per dispute/fraud transaction
april 2026:
drops to 1.5% in US/EU/APAC
THE CALCULATION
here's how they fuck you:
VAMP ratio = (TC40 fraud reports + TC15 disputes) / total transactions
TC40 = fraud alerts from banks
TC15 = customer disputes
both count against you
even if you WIN the dispute
THE DOUBLE-COUNTING SCAM
fraudulent transactions counted TWICE:
1. TC40 fraud report (filed immediately)
2. TC15 dispute (when customer disputes)
same transaction
counted twice in your ratio
THE ENUMERATION TRAP
card testing attacks also monitored:
if 20%+ of transactions = enumeration attempts
you're in VAMP
minimum 300k transactions to qualify
what's enumeration:
fraudsters testing stolen card numbers
your processor sees it as YOUR fault
THE MINIMUM COUNTS
you're only tracked if you hit:
1,500+ monthly disputes/fraud reports
so:
small brands: safe (for now)
scaling brands: fucked
THE PENALTY STRUCTURE
exceed 2.2% threshold:
$8 per dispute
$8 per fraud report
charged monthly
no cap
$10k in disputes monthly = $80k in fines annually
THE PROCESSOR PASS-THROUGH
visa charges processors
processors charge YOU
plus:
processors add their own penalties
tighter internal thresholds (1.5% or lower)
account restrictions
potential termination
THE GRACE PERIOD (EXPIRED)
april - october 2025: advisory period
visa monitored but didn't penalize
october 1:
enforcement started
fines began
THE ECOM REALITY
ecom brands typically run:
2-5% chargeback rates (normal)
3-7% for supplements (customer "doesn't work" claims)
5-10% for peptides (grey market stigma)
all OVER the 2.2% limit
THE PEPTIDES NIGHTMARE
peptides hit hardest:
customers don't understand research use
dispute charges thinking it's fraud
"I didn't authorize this"
banks auto-file TC40s
your 5% dispute rate:
now costs $8 per transaction
on top of losing the sale
THE NUTRA TRAP
nutraceuticals killed:
rebill models = high disputes
"I didn't know it was subscription"
standard 3-5% industry chargeback rate
VAMP doesn't care about "industry standard"
2.2% or you pay
THE CBD/THC ISSUES
cannabis adjacent gets wrecked:
banks already hate you
higher fraud flags
customer confusion on legality
disputes spike
you're fighting uphill already
VAMP makes it impossible
THE SUPPS PROBLEM
even clean supplement brands:
customers claim "doesn't work"
return window expired = dispute
fitness bros charge back everything
2-3% dispute rate was manageable
now it costs $8 per transaction
THE PROCESSOR RESPONSE
what processors are doing now:
implementing 1.5% internal limits (below VAMP)
instant account reviews at 1%
reserves increasing to 20-30%
shutting down "high-risk" categories
THE CATEGORY BANS
processors preemptively banning:
peptides (too risky)
kratom (legal but flagged)
nootropics (disputes too high)
detox products (refund requests)
not waiting for VAMP
just banning entire categories
THE SHOPIFY PAYMENTS CRACKDOWN
shopify payments tightening:
used to be lenient
now tracking VAMP closely
automatic pauses at 1.8%
permanent bans at 2.2%+
THE STRIPE RESPONSE
stripe got even worse:
already had strict limits
now using VAMP as excuse
banning brands at 1.5%
no appeal process
THE MERCHANT ACCOUNT REALITY
even high-risk merchant accounts:
used to allow 3-5% chargebacks
now enforcing 2% maximum
VAMP gives them cover to be stricter
THE FALSE POSITIVE PROBLEM
TC40 reports filed automatically:
customer reports card as stolen
even if purchase was legitimate
TC40 filed immediately
counts against your ratio
you can't dispute TC40s
they're permanent
THE 3DS LOOPHOLE (CLOSED)
used to be:
3D secure shifted liability
fraud chargebacks didn't count against merchant
VAMP changed this:
TC40 still filed
still counts in VAMP ratio
even if you're not liable
THE RDR EXCLUSION (REVOKED)
rapid dispute resolution:
was supposed to exclude disputes from VAMP
visa reversed this march 2025
TC40s count even if RDR resolved
THE PREVENTION COSTS
staying under 2.2% requires:
fraud prevention tools: $500-2000/month
chargeback alerts: $500-1000/month
3DS implementation: setup + fees
manual review team: 1-2 people
costs eat into margins
THE MARGIN SQUEEZE
ecom already tight margins:
product cost: 30-40%
ads: 20-30%
processing: 3-5%
shipping: 10-15%
now add: fraud tools + VAMP fees
profit disappears
THE SCALING IMPOSSIBILITY
you're stuck:
can't scale without higher dispute volume
higher volume = over VAMP threshold
over threshold = $8 per dispute
makes scaling unprofitable
THE ACQUIRER PRESSURE
your processor's processor (acquirer):
tracked by VAMP too
if portfolio exceeds 0.7% = fined
pushes risk down to merchants
acquirer pressure = processor bans you
THE MATCH LIST THREAT
exceed VAMP consistently:
processor terminates you
reports to MATCH list
other processors see it
can't get processing anywhere
business death sentence
THE OFFSHORE PUSH
brands moving offshore:
non-US processors
caribbean banking
asian gateways
escaping VAMP jurisdiction
but higher fees (8-12%)
THE CRYPTO CONSIDERATION
some brands going crypto-only:
USDC/USDT payments
no chargebacks
no VAMP
no banks
but: customer friction
THE BUSINESS MODEL BREAK
VAMP breaks ecom fundamentals:
can't offer easy refunds (encourages disputes)
can't be customer-first (customers dispute)
can't scale aggressively (volume = disputes)
THE COMPETITOR ADVANTAGE
big brands with <1% disputes:
amazon: huge volume, tiny dispute ratio
established supplements: loyal customers
brand names: less fraud
they're fine
small brands scaling:
destroyed
THE TIMING DISASTER
rolled out now (2025-2026):
post-covid ecom boom
brands at scale
perfect time to crush small operators
THE VISA MOTIVATION
why visa doing this:
"reduce fraud" (official)
push risk to merchants (reality)
protect banks (priority)
small merchants = acceptable casualties
THE ACQUIRER MOTIVATION
why acquirers enforce strictly:
their own VAMP penalties
portfolio risk
easier to drop merchants than fight visa
THE PROCESSOR MOTIVATION
why processors ban preemptively:
fear of VAMP fees
fear of losing processing rights
easier to ban than monitor
you're expendable
THE MONITORING DIFFICULTY
you can't even track it properly:
TC40 data not easily accessible
need to request from processor
processor delays providing it
by the time you know, you're over
THE APPEAL PROCESS (NONE)
no way to dispute:
VAMP ratio is automatic
TC40s are permanent
no review process
no human override
algorithmic death
THE CATEGORY DEATH SPIRAL
what's happening now:
peptides brands: banned en masse
kratom: processors exiting
CBD: tightening restrictions
nutra: rebills dying
entire categories disappearing
THE COMPETITIVE MOAT
this creates moat for:
brands grandfathered in before VAMP
brands with established low dispute rates
brands with dedicated high-risk processing
impossible for new entrants
THE REAL SOLUTION (NONE)
you can't actually stay compliant:
ecom = inherent disputes
customers = always dispute
product claims = invite disputes
scale = more disputes
math doesn't work
THE PROCESSING ALTERNATIVES
what's left:
high-risk specialists (8-15% fees)
offshore processors (10-12% fees + sketchy)
crypto only (lose 90% of customers)
shut down
THE BOTTOM LINE
VAMP enforcement started october 1
if you're running:
- peptides
- nutra
- CBD/THC
- supps
- any high-dispute ecom
you're about to get:
- $8 per dispute fees
- processor bans
- account terminations
- MATCH list
- business death
april 2026:
threshold drops to 1.5%
gets even worse
THE HONEST TRUTH
visa just made ecom unsustainable
for high-risk categories
they don't care
banks don't care
processors don't care
small ecom brands:
acceptable casualties in fraud war
you need:
- high-risk processor now
- fraud prevention tools
- dispute management
- or exit plan
- jericho
DM me "PAYMENTS" for a payment processor that doesn't screw you over like this for 0,01% chargeback rates (free setup)
7
2
551
from the recent articles this is BY FAR the most valuable
actually read and implement you have NO IDEA what you're missing
184
visa's VAMP enforcement just started and ecom brands are losings $1M+
basically if you're running peptides/nutra/CBD/THC/supplements
your payment processor is about to screw you 🤣
here’s the situation:
1. they’re monitor everything
2. an $8 fee per dispute over limit
3. they have stricter thresholds than ever
4. they have a new fraud/dispute tracking system
issue is most ecom brands have NO idea this exists
the VAMP ratio limit is also 2.2%
this means more than 2.2% of transactions = disputes/fraud
crazy work
on april 2026 this drops to 1.5% in US/EU/APAC
the numbers are messed up too:
VAMP ratio = (TC40 fraud reports + TC15 disputes) / total transactions
TC40 = fraud alerts from banks
TC15 = customer disputes
so both count against you
even if you WIN the dispute
fraudulent transactions are also counted TWICE:
1. TC40 fraud report (filed immediately)
2. TC15 dispute (when customer disputes)
same transaction but counted twice in your ratio
you’re just burning free money here
THE ENUMERATION TRAP
card testing attacks will be monitored too:
if 20%+ of transactions = enumeration attempts you’ll be in VAMP
you need minimum 300k transactions to qualify
and enumeration in a nutshell is:
- fraudsters testing stolen card numbers
- but the processor sees it as YOUR fault
not ideal as you could’ve guessed
you're only tracked if you hit 1,500+/mo disputes or fraud reports though
so small brands are safe (for now)
but scaling brands are screwed
THE PROCESSOR PASS-THROUGH
visa charges processors & processors charge YOU
processors then add their own penalties:
- tighter internal thresholds (1.5% or lower)
- potential termination
- account restrictions
there’s literally nothing you can do
and problem is ecom brands typically run:
2-5% chargeback rates (normal)
3-7% for supplements (customer "doesn't work" claims)
5-10% for peptides (grey market stigma)
all WAY OVER the 2.2% limit
for brands like peptide ones this is even worse:
1. customers don't understand research use
2. dispute charges thinking it's fraud
3. banks auto-file TC40s
meaning your 5% dispute rate now costs $8 per transaction
that’s ON TOP of losing the sale
this even includes brands in nutra/CBD/THC/supplements
processors are even preemptively banning them
they’re not even waiting for VAMP
just banning entire categories
THE FALSE POSITIVE PROBLEM
there’s another MAJOR issue
if a customer reports card as stolen?
even if purchase was fully legitimate?
TC40 gets filed immediately counting against your ratio
but you can't dispute TC40s since they're permanent
now all this used to be done with 3DS (it shifted liability)
but VAMP just had to change this
they quite literally broke it
THE RDR EXCLUSION (REVOKED)
the rapid dispute resolution was supposed to exclude disputes from VAMP
but then visa reversed this so TC40s count even if RDR resolved
the issue is that staying under 2.2% requires:
1. fraud prevention tools: $500-2000/month
2. chargeback alerts: $500-1000/month
3. 3DS implementation: setup + fees
4. manual review team: 1-2 people
costs eat into margins & you can’t predict humans
ecom has almost always had BAD margins too
i know a friend who was making $1.3M/mo
i asked how much profit he said $18k/mo
those are horrible margins so you just end up stuck
THE MATCH LIST THREAT
if you exceed VAMP consistently your processor terminates you
then they report it to the MATCH list where other processors see it
you won’t get processing anywhere anymore
this is why brands are moving offshore now
they’re escaping VAMP jurisdiction
even if it means higher fees (8-12%)
some brands are even going crypto-only:
USDC/USDT payments
no chargebacks
no VAMP
no banks
the main issue with this is customer friction though
overall this is why big brands with <1% disputes are winning:
established supplements: loyal customers
amazon: huge volume & tiny dispute ratio
brand names: less fraud
they're fine
so you’re either a small brand or a super big one
if your disputes are under <1% you’re good
this is hard to get with scaling brands
THE VISA MOTIVATION
visa is officially doing this to "reduce fraud"
but they actually want to push risk to merchants
this protects banks
there’s literally no way to dispute either:
1. VAMP ratio is automatic
2. TC40s are permanent
3. no review process
4. no human override
if you’ll try they take forever too
if you’re in the space you know they’re slow
this is exactly why so many niches/brands are dying
once they get hit by this they can’t even dispute
it’s sleaziness at it’s peak
THE REAL SOLUTION (NONE)
you can't actually stay compliant:
ecom = inherent disputes
customers = always dispute
product claims = invite disputes
scale = more disputes
you’ll either do it illegally or accept it
you could try some processing alternative too but:
offshore processors (10-12% fees + sketchy)
crypto only (lose 90% of customers)
high-risk specialists (8-15% fees)
there’s a lot of risk
the fees are high too
so if you don’t know what you’re doing?
just accept the situation
visa literally made ecom unsustainable for high-risk categories
they don’t care
banks don't care
processors don't care either
it’s making them all money long-term
but also screwing a lot of brands
this is simply how the game is
you need to be adaptable
- jericho
p.s. DM me “VAMP” and i’ll set you up with a payment processor that won’t screw you over (no upfront fee)
1
245
or if instead of protecting your shopify from this you just want an alternative that doesn't screw you over
i know payment processors and banks that won't freeze your account on your first chargeback
DM me "SHOPIFY" if you want me to connect you with them (at no upfront costs)
teapawt.net/messages/compose?recip…
119
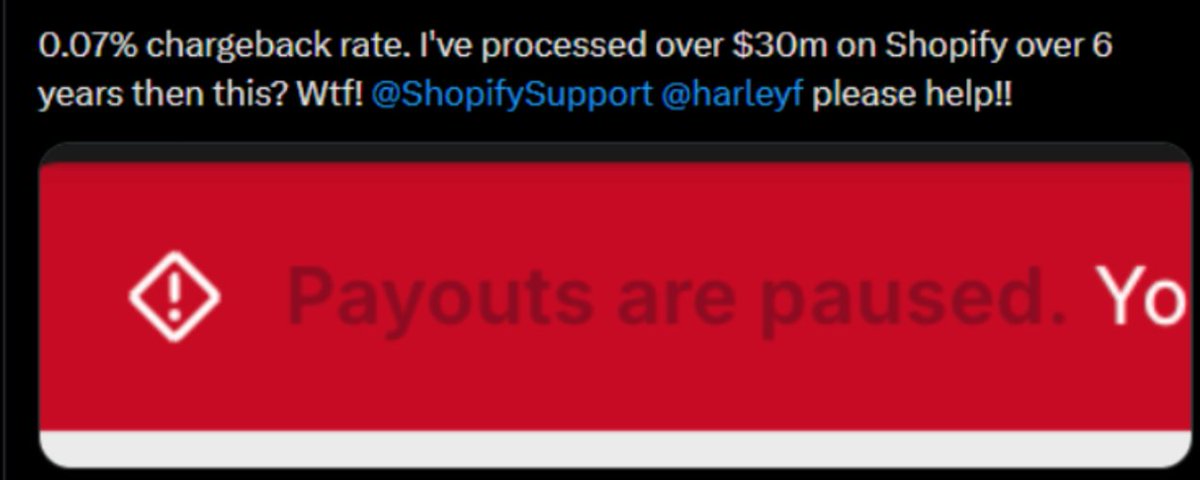
.@CharlieCannon9 EXPOSED how @Shopify deleted $500k+ of subscriptions:
- had a 0.07% chargeback rate
- also had $30M processed over 6 years
he tried to appeal this
but shopify responded saying "payouts are paused"
his not the first tho
let me tell you what's happening:
charlie had $500k+ in active subscriptions vanish overnight
even though his chargeback rate was insanely low
industry average is literally 1-2%
charlie had a 0.07% chargeback rate
this guy's rate is 30x better than average
there was nothing that should’ve been flagged
what’s also crazy is that $500k in subscriptions means:
1. maybe 10,000+ active subscribers
2. recurring monthly revenue $50k+/month
3. a predictable cashflow & legitimate business model
keep in mind spotify also profits from this
but now all of it was gone instantly?
something was definitely going on
what’s wild is this isn't an isolated event
i’ve seen shopify do this dozens of times
it’s also not just shopify but we’ll get into it soon
what probably happened was the algo flagged his account
then they probably didn’t do any human review
since if they did then someone got fired
not only did charlie lose a lot of revenue
but shopify lost too including a lot of trust
this is NOT a good look
THE CUSTOMER IMPACT
10,000+ customers had their subscriptions canceled
no notification and a huge hassle
i’m sure most won’t resubscribe
this is ends up being a massive dent
it’s not like shopify can’t just do this either
they can
literally buried in their terms is:
"we can terminate for any reason"
"no liability for business interruption"
"decisions are final"
and you are forced to agree
then there’s the fact they process all payments
whatever money you make they can control
this is why i recommend using other processors
had he used separate processor?
1. paypal bans you = keep using shopify
2. stripe bans you = switch to other processor
3. processor issues = move money elsewhere
not to say they don’t have their own problems
it’s easy to say "just use stripe separately"
except:
- shopify pushes their payments
- better rates on shopify payments
- most merchants use shopify payments
not to mention their integrated checkout
and it’s not like stripe DOESN’T do this either
brands just don’t lose their entire stores over it
so it would be much safer long-term sure
shopify can (and will) take your store
THE APP STORE DEPENDENCY
if you used shopify apps:
recharge (subscriptions)
gorgias (support)
klaviyo (email)
they’ve all integrated with shopify
switching over to other places sucks
this includes integrating them
it’s like going from apple to android
the deeper you’re in their ecosystem the harder it becomes to leave
this is why platform dependency kills:
one decision = unnecessary risk
shopify owns everything
there’s no recourse or backup
they make it really hard to pivot
THE HONEST REALITY
shopify payments is:
convenient until it isn't
cheap until they ban you
integrated until they delete you
i’ve seen this pattern everywhere though
stripe deletes $100k+ accounts
paypal freezes $200k balances
shopify nukes $500k subscriptions
so it’s not just shopify
this is why i recommend you use separate processors:
1. stripe/authorize .net/high-risk provider
2. separate from shopify hosting
3. backup payment methods
4. diversify risk
this costs more & might be more complex
but one freeze or ban won’t destroy your brand
it’s how charlie cannon lost $500k in subscriptions
possibly way more than that long-term too
but this could’ve been avoided
never depend on one platform
it’s bad business practice
it’ll get you cooked
- jericho
DM me if you want me to connect you with an alternative payment processor that doesn’t screw you over like shopify
($100k+ processed + no upfront/setup fee)

‼️INSANE
$500,000 of Subscriptions DELETED
@harleyf
0.07% chargeback rate. I've processed over $30m on Shopify over 6 years then this? Wtf! @ShopifySupport @harleyf please help!!

1
5
452
here’s how adobe DESTROYED a 14 year old's business over $300:
i have a buddy who’s trying to “escape the matrix”
he’s a 14/yo thumbnail designer
the goal was to help his parents
then adobe ruined his hustle
let me explain what they did:
THE SITUATION
his family situations is tough
only one parent working
they were struggling financially
they couldn't afford much
so he was motivated
started teaching himself photoshop
making thumbnails for youtubers
he was earning $0-$7 per thumbnail
helping family with money
solid for a beginning
THE ADOBE SUBSCRIPTION
he needed photoshop
saw adobe creative cloud for $30/mo
seemed affordable
so he signed up
but what he didn't see buried in terms:
"annual plan"
"paid monthly"
meaning signed up for FULL YEAR
he’s just paying for it MONTHLY
can’t blame adobe for this
still kind of sad to see
adobe denied any cancellations/refunds
and the issue was my friend:
1. doesn't have $300
2. family can't afford it
3. can't keep paying $30/mo
he was TRAPPED
so he did the only thing he could think of:
withdrew all money from his credit card
ignored adobe's emails & hoped it would go away
THE CONSEQUENCES
of course adobe didn't just cancel:
- sent to collections
- credit ruined at 14
- credit card blocked
- collections agencies calling
even collections agencies were calling the family
they were demanding $300+ fees
won't accept "he's 14" as an excuse
crazy
THE SYSTEMIC PROBLEM
adobe uses:
aggressive collections
dark patterns in signup
no exceptions for minors
complex cancellation terms
don’t blame them though
this is super common
lots of companies do so (apple/spotify etc)
but the question is:
can 14 year old even sign binding contract?
most countries disagree
contracts with minors are voidable
but adobe doesn't care
they send to collections anyway
his family doesn't know their rights
THE PAYMENT PROCESSOR ROLE
adobe processes through stripe/paypal/direct billing
processors enabled:
- deceptive annual billing
- aggressive collections
- minor contracts
there’s zero accountability
this is a major problem
THE COMPETITOR COMPARISON
this is a big reason some avoid adobe
for example affinity photo (competitor):
1. no subscription
2. $70 one-time purchase
3. full photoshop alternative
he didn't know it existed
adobe dominates search results
either way he learned to read every word
and not to trust subscription services
he should only do one-time purchases only
thousands of kids also:
same trap
same collections
sign up for adobe
same credit damage
adobe makes billions partly from this
because thye’re literally optimized for comfort
1) easy signup (get them hooked)
2) hidden terms (trap them)
3) expensive cancellation (keep them paying)
4) aggressive collections (scare them)
the comfort ends once you want to cancel
that’s how they get you in the long-term
but personally if you’re under 16-18
avoid legally binding contracts
corporations don’t care
they want your $$$
that’s why i deliver payment processors that don’t screw you over like that
no accounts freezes for no reason
this is my why
- jericho

4
349
the FTC hit amazon with a $2.5B lawsuit just because Jeff Bezos tricked millions into prime subscriptions lmao
type shi that don’t appear on TV 🤣
let me explain the scam:
amazon prime is really sneaky
their checkout page be moving like counterfeit nigerian organizations:
1. giant "join prime" button
2. tiny "no thanks" link hidden
2. desktop has deceptive placement
4. mobile has terms at bottom (must scroll)
this way users accidentally enroll
most don’t cancel either
kind of dumb
but this isn’t a big deal ofc
the real SCAM comes later down the line:
THE CANCELLATION MAZE
FTC called it "THE ILIAD FLOW"
named after homer's epic poem
all because it was so long and complicated
to cancel prime you had to:
- go through 4 pages
- 15 different options
- discount attempts
- benefit reminders
- repeated offers
it was designed to prevent cancellation
and internal amazon documents showed:
"when we make cancellation easier sign-ups drop"
"revenue impact is significant"
"we need to keep the friction"
they KNEW it was deceptive
but did it anyway
the scale was huge too so they printed:
200 million US subscribers
$44 billion annual revenue
$14.99/month per person
FTC estimated tens of millions subscribed accidentally
that’s a crap ton annually for amazon
FTC then pressed charges
amazon had tons of violations:
1. restore online shoppers confidence act (ROSCA)
2. FTC act section 5 (deceptive practices)
3. collecting payment info before disclosing terms
4. dark patterns in enrollment
5. sabotaging cancellation attempts
they were in deep with no way out
THE $2.5B BREAKDOWN
the settlement:
$1B civil penalty (largest ever for FTC violation)
$1.5B consumer refunds (second largest restitution)
consumers get up to $51 back per person
amazon loses 0.1% of their market cap
which is basically nothing to them
but here's the disgusting part:
stripe processed prime payments
paypal processed prime payments
they processed BILLIONS in deceptive subscriptions
zero consequences
probably since it made THEM money too
but then there’s a peptide brand
maybe one you even use
they get some refunds and end up flagged
some even get banned for a 2% chargeback rate
but when amazon tricked people?
they didn’t care
THE PROCESSOR PROTECTION
stripe/paypal protect amazon because it prints
amazon brings in a ton of revenue
especially with those subscriptions
amazon can also threaten:
"ban us and lose billions in processing fees"
stripe/paypal are NOT okay with that
that would be a huge dent in revenue
THE SETTLEMENT DETAILS
the $2.5B is nothing for amazon
so amazon just had to:
1. simplify the cancellation
2. clear enrollment disclosure
3. no dark patterns
4. third-party monitor compliance
but there was no admission of wrongdoing
business continues normally
it’s crazy because stripe & paypal knew
they saw the signup flows and everything
but they kept processing
it brought in a lot of money
corporate greed at its finest
but if you ran this scheme:
stripe: instant ban
paypal: permanent limitation
chargebacks: through the roof
legal: immediate lawsuit
you'd be destroyed in 30 days
THE SPOTIFY PARALLEL
spotify is doing something similar
they just raised prices on 281M users
no issue processing that
it’s not exactly illegal
but we know why they did it
“but why aren't processors liable?”
they FACILITATED the deception:
- processed the payments
- enabled the subscriptions
- saw the patterns
- did nothing
basically they’re too big to prosecute
that’s pretty messed up i can’t lie
any smaller brands get screwed
banned because they’re "high risk"
by the same system protects big brands
it’s not about compliance
it’s all about power
if you got the funds you’re basically untouchable
- jericho
p.s. DM me “ANTIFTC” for a payment processor that isn’t biased (no upfront fee)

4
596
NOBODY knows why andrew tate got banned from EVERY payment processing option out there
they say it was jail
others say it was jews
others say it’s controversy
here's what actually happened though:
THE RISE THAT STARTED IT
tate built:
hustlers university (online course)
$49/month subscription
50,000+ members
$2.5M monthly revenue
processed through:
stripe initially
paypal
various processors
then came the day of his death:
THE SOCIAL MEDIA BAN WAVE
august 2022:
instagram: banned
facebook: banned
youtube: banned
tiktok: banned
reason: "violating community guidelines"
(controversial opinions on masculinity)
THE PAYMENT PROCESSOR CASCADE
once social media banned him:
stripe: "high risk association"
paypal: "reputational risk"
banks: "controversial figure"
crypto exchanges: "regulatory concerns"
all banned within weeks
even random ass companies like whatsapp banned him lmao
THE REPUTATIONAL RISK EXCUSE
processors claimed:
"we can't be associated with controversial figures"
except:
they process for:
- actual adult content
- gambling sites
- payday lenders
but opinions on masculinity?
apparently seems too risky
THE COORDINATION
bans happened:
simultaneously
across multiple platforms
within days of each other
suggests:
either coordination
or automated reputation monitoring
THE PAYMENT INFRASTRUCTURE CONTROL
modern payment processors can:
deplatform anyone
for any reason
no due process
no appeal
and even his banks:
closed his accounts
froze his funds
no explanation
moving money became impossible
THE CRYPTO SOLUTION ATTEMPT
tate tried crypto:
binance: banned
coinbase: banned
kraken: banned
even decentralized finance:
can't use centralized exchanges
can't cash out easily
THE AFFILIATE BAN
anyone promoting tate:
stripe: banned for association
paypal: account frozen
banks: closed accounts
guilt by association
(multiple mfs i know got lifetime bans from clipping for him)
THE HUSTLERS UNIVERSITY IMPACT
50,000 paying members
couldn't process payments
had to:
- use crypto only
- offshore processors
- manual wire transfers
- lose most customers
THE LEGAL VS ALLOWED
everything tate did:
completely legal
no criminal charges at that time
(later arrested in romania, separate issue)
but legality didn't matter
THE PROCESSOR TERMS OF SERVICE
buried in TOS:
"we can terminate for any reason"
"reputational risk"
"association with controversial content"
translation:
we can ban you for opinions
THE PRECEDENT
if they can ban tate they can ban anyone for any opinion they don't like
today: controversial masculinity
tomorrow: wrong political view
next week: unpopular opinion
THE SMALL BUSINESS PARALLEL
if tate can be banned:
your business can too
for:
- customer complaints
- controversial products
- wrong associations
- processor doesn't like you
THE APPEAL PROCESS
tate tried appealing:
stripe: automated rejection
paypal: no response
banks: "decision is final"
zero due process
THE REVENUE LOSS
$2.5M monthly to zero
because:
payment infrastructure denied access
not illegal
not scam
just controversial
THE CURRENT STATE
tate now uses:
crypto exclusively
offshore banking
wire transfers
smaller processors
real physical money
made it work
but lost 80% of customers
THE WARNING
payment processors have:
absolute power
zero accountability
no competition
monopoly control
THE SYSTEM ABUSE
they can:
ban you for opinions
freeze your funds
destroy your business
no recourse
bottom line:
tate was banned
not for illegal activity
for controversial opinions
payment processors coordinated:
stripe, paypal, banks, crypto
if they can ban tate:
they can ban anyone
your business is one wrong opinion away from complete deplatforming
mainstream payment infrastructure is:
centralized
monopolistic
weaponized
never forget that
- jericho
This quoted post is unavailable.
13
4
410
spotify raised prices by $2 and made an extra $6B+ yearly
from $9.99/mo to $11.99$/mo
$2 might seem small but they have 281M+ users
not to mention bigger pricing plans 😂
let me explain why this is genius:
the opt-out is small
cancelling sucks anyway
it’s basically a forced rebill
but payment processors won’t even care
if you were to try that you’d get banned
you don’t have the leverage spotify has
spotify brings processors:
1. $2.8B+ monthly in rebills
2. 281M recurring transactions
3. <0.5% chargeback rate
4. decades-long relationship
then spotify announced they’d increase prices
individual: $9.99 → $10.99
family: $15.99 → $16.99
duo: $12.99 → $14.99
this is an automatic rebill increase
no confirmation needed
no re-authorization required
most don’t even check their emails
literally free money
but if you tried this:
"hey we're charging $10 more next month"
stripe will screw you with:
"account review"
"high risk behavior"
"increased chargeback risk"
"requires customer re-authorization"
all because you lack power
this is all about leverage
spotify also has brand protection
- legal armies
- household name
- compliance teams
- market dominance
- processing leverage
it would be stupid to ban them
spotify can even threaten stripe
"process our price increase"
"or we switch to adyen"
stripe listens like a good boy
THE SUBSCRIPTION DYNAMIC
spotify has a custom deal with processors:
- custom rates (way below 2.9%)
- dedicated account reps
- instant payouts
- no reserves
- zero holds
they can do this because they’re so big
smaller brands couldn’t
spotify's chargeback rate is also <0.5%
despite 281M users
why?
people don't check statements
autopay blindness
"it's only $2 more"
this is genius
THE SCALE ADVANTAGE
processors love spotify because:
1. virtually zero chargebacks
2. predictable revenue
3. low risk (recurring)
4. massive volume
smaller businesses tend to be unpredictable
that messes with a lot
especially long-term
spotify also operates globally (obviously):
different currencies
different regulations
different consumer protection laws
processors handle it all no questions asked
spotify even has custom processor integrations
and if they mess up there are fallback payment methods
they’re super safe
but these only come if you’re big
i know some smaller brands have it
but most don’t (major problem)
THE REGULATORY ARBITRAGE
spotify even operates in countries with weak consumer protection
they process through favorable jurisdictions
then use complex corporate structures
this legal but slightly grey
but it prints a lot
since they can get away with stuff
THE PROCESSOR INCENTIVES
stripe makes more money from:
- 281M x $0.30 per transaction
- plus processing percentage
- equals millions in fees
than from your $10k/mo processing
if even that lol
so who cares if you're banned
spotify is irreplaceable for stripe
they can force stripe’s hand
it's never about compliance
it's about leverage & power
you’ll see this everywhere
that’s the way of life
until you’re big enough to be chased by the elites
find a payment processor that works

spotify has 281 million premium users and just raised their price from $10/mo to $12/mo
meaning that they will literally make an extra of $6,744,000,000 a year from that small ass change
i think we gotta take a quick sec to acknowledge that motion

2
7
422