

Quant Macro | Economic Policy | Cross-Asset Trading
New York, NY
Joined May 2024
- Tweets3.7K
- Following535
- Followers1.5K
- Likes14.8K
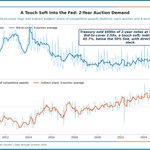


Treasury sold $69B of 2-year notes at 4.708% on Monday. Bid-to-cover 2.59, a touch soft. Indirect buyers took 45.7%, below the 50% retreat line, with directs picking up the slack, heading into Wednesday's FOMC decision.

Was getting annoyed that my charts kept uploading all fuzzy and apparently it's because data saver somehow got turned on smfh
Online keeps taking share from the store, a bit more slowly. Nonstore retailers took 19.0% of retail sales over the year to September, growing 7.4% against 3.4% for stores. The four-point gap is below its 2010s average, yet the share still climbs almost a point a year.

Two inflations into tomorrow's Fed. Core PCE ran 2.05% annualized over the three months to August against 3.01% over twelve, so the real policy rate is 0.9 or 1.8 points depending on the window. Headline, at 3.42%, is running on oil.
New Beam: lighthousemacro.substack.com…

Update on a favorite.


I still love this chart of Japan & China's 30yr Yields. It's like the bond market giving an an entire economic theses on the massive structural changes occuring for 2 of Asia's most powerful nations, as they attempt to undo & shutter the failed policies of recent past.
But instead of words it's just two lines.

The 5s30s Treasury curve was 51bps on Friday, +2bps since the Sep 16 hike. Over the same 26 sessions in 2022 it moved -27bps, and each of the five cycles since 1994 took it to 20bps or less (2015 was the high). So far the long end is holding its slope as the Fed tightens.

For those unfamiliar with our Crypto Liquidity Impulse, here's the Quintile buckets by forward return. The current reading is at lower bound of Q2 seems to be heading towards the Q1 bucket. Either bucket, as you can see, tells us that now is not the time to be getting long $BTC.


In the words of warrior poet, Fred Durst, keep rollin' rollin' rollin'.

GDPNow's 3.4% for Q3 is 4.4 pts of domestic demand and -1.0 from trade and inventories (net exports -2.9, inventories +1.8). That swing has run 1.1 pts of std dev since 2025 vs 0.7 in 2015-19. Read Thursday's print through domestic demand.

The Mooch was cookin’ here


Biden was actually good for the stock market.
Rates were heading lower. Inflation was coming down.
The 10-year was at 3.96%. Gas was in the 3’s.
If Trump had just fixed the border, which most Americans wanted, and left everything else alone, we’d probably be doing a lot better right now.
Instead we got tariff which have been an unmitigated disaster.
Yes, the stock market is doing okay, but it could be doing so much better.
And here’s the thing: we personalize economics onto presidents when it’s mostly situational.
Bush Sr. got blamed for a recession from the Gulf War. Clinton got credit for a recovery that was probably just cyclical.
This time though is self-inflicted. The president has inflicted self-harm on the economy.
I will never understand investors who fall in love with an investment to the point they champion it online AND get mad at people who say anything moderately bearish. Bitcoin does not care about you. That illiquid small cap doesn’t love you. TSLA/Elon don’t know you exist.
With all the buzz about Anthropic’s IPO I’m sure many of you are wondering when our plans. After discussing it with our board members and largest investors, we feel it is most appropriate for us to remain a private enterprise at this time. Thank you for your attention to this matter.

The union wage catch-up is close to finished. Union wages rose 3.57% y/y in Q2 against 3.10% nonunion. The gap peaked at 2.85 points in Q3 2024 as post-2022 contracts reset and is now 0.47, so one source of wage heat into Friday is fading.

Across 38 FOMC decisions since 2022, SPY averaged +0.01% on decision day, up 17 of 38 times. The 2y fell an average 1.7bps on the day and 1.8bps the next. On the Sep 16 hike the 2y rose 7bps, then gave back 7bps. Wednesday is decision 39.


Treasury sold $69B in 2-year notes at 4.708%. Bid-to-cover 2.59, a touch soft. Indirect buyers fell to 45.68%, below the 50% retreat line, with directs picking up the slack. A touch soft heading into Wednesday's FOMC decision.

I just ran the numbers, we're never going to lose again. And in fact, the model made it clear that if the Giants ever do lose again, that would be undeniable evidence that the other 31 teams & Goodell are colluding against the Giants. Presumably to hurt me, personally. I knew it
Lighthouse Macro retweeted
SLOOs (inv, adv +15m) & loan demand (+9m)
-Standards leads demand 4-5Q.
- Demand leads grow by 2-3Q.
- Jan to September: From contracting loan growth to double digit growth
Chart 2:
- Demand (+6m) ➡️ loan growth
- Borrowing ⬆️ coincides with Capex orders ⬆️


To narratively frame it: end of last summer lending standards began to loosen, a little later businesses started shopping for loans again a bit after that a lot more loans were being given out. Those businesses are using those loans to fund their orders.
Credit fueled growth. Still growth. So don’t ignore that part. But I’m much more cautiously watching it than I was earlier in the cycle.