
I write about high-quality stocks with 10x return potential. My weekly portfolio update, trades, & research: https://xitter.cf/t.co/XkR3FbgzS6
See Portfolio & All Trades 👉
Joined June 2012
- Tweets38.5K
- Following2.7K
- Followers74.3K
- Likes11.6K



Pinned Tweet
Legendary investor Howard Marks just released a new memo.
“In my 53 years in the investment world, I’ve seen economic cycles, manias and panics, bubbles and crashes, but I remember only two real sea changes. I think we may be in the midst of a third one today.”
My Notes…
Feels relevant given the recent comments by @elonmusk

The real reason the $NBIS $CRWV $IREN sell-off after the $META news is 100% justified is because it proves that Neoclouds are a temporary solution for the largest customers until the economics make sense for them to build their own.
It doesn’t mean that Neoclouds are unnecessary. A lot of companies will still need them.
However, it does turn them into more of a commodity and begin to put a ceiling on demand.
With that comes a re-rating which is what we are starting to see.
Anyone who denies this is biased. It’s a fact.
Feels like it’s a good time to resurface this
xitter.cf/liebermanaustin/status…

Pretty much.
As of the past few weeks, debt markets have almost entirely shut off access to money for any company that doesn’t have substantial revenue independent of AI data centers.
SpaceX closed $40B of debt for GPUs, but we’re investment grade and have Starlink & launch revenue.
That means the 200+ neoclouds are going to see guppy-level death and consolidation. Some will make it through, but not many.
Reckless prediction. Market is gonna rip today.
Took the hedge off and slowly starting to build positions up again.
Sitting at 54% cash and in no rust to get fully invested. I think we’re in for a bit of a volatile period which is great for stock pickers.
Full update coming shortly to premium subscribers

Took my $SQQQ hedge off and made a few small purchases. Sitting at 54% cash and in no rush to get fully deployed.
Will build out positions opportunistically.
The most important thing is to control your emotions and not get married to certain stocks if they get way over valued.

Exceptional deep dive into $BRO from @FASTGraphs
My absolute favorite recent follow. Give them a follow now!

$BRO has raised its dividend for 33 years in a row, but the stock is down 43%.
Is this a buying opportunity or a falling knife?
VALUATION (from @FASTGraphs):
Blended P/E: 15.87x
Normal P/E: 22.64x over 20 years
5-year normal P/E: 26.31x
EPS yield: 6.30%
Dividend yield: 0.94%
Since December 2006, earnings are up 729%, while the stock price is up 361%, lowering the P/E from roughly 28x in 2006 to 16x today.
The stock peaked near $125 in March 2025, at a P/E of roughly 29x. Four quarters later it's at $70 and a blended P/E near 16x.
THE BUSINESS:
When a trucking company, a hospital, or a city needs insurance, it usually does not call an insurer. It calls a broker, who shops the risk to carriers, negotiates the terms, and collects a commission on the premium every year the policy renews. Brown & Brown is one of the world's five largest insurance brokers: $5.9 billion in revenue in 2025, about 23,000 employees, and more than 700 offices.
It carries no underwriting risk. The carriers pay the claims.
$BRO was founded in Daytona Beach in 1939. Hyatt Brown joined the family agency in 1959, bought it out, became CEO in 1961, and ran it for 48 years, listing it on the NYSE in 1993.
His son Powell has served as CEO since 2009, and Hyatt remains chairman. The company grew through hundreds of acquisitions of smaller agencies with operating margins near 30%, and it joined the S&P 500 in 2021. One segment sells insurance and benefits to businesses, governments and individuals. The other sells to other brokers and runs insurance programs on behalf of carrierBsR.
THE FUNDAMENTALS (2022 to 2025):
Revenue: $3.57B to $5.90B (18.25% CAGR)
Operating income: $1.04B to $1.70B (17.56% CAGR)
Net income: $659M to $1.04B (16.53% CAGR)
Operating cash flow: $881M to $1.45B (18.05% CAGR)
Operating margin: 29.23% to 28.72%
Return on equity: 15.03% to 9.62%
Return on invested capital: 9.35% to 7.32%
LT debt/capital: 44.23% to 34.87%
Profit grew with revenue, and margins held. In 2025, the company doubled in size.
Total assets went from $17.80B to $30.65B, equity from $6.44B to $12.57B, and the company spent $7.91B on acquisitions, with $7.71B raised in stock and debt.
Return on equity and invested capital fell because the new capital arrived in June and the acquired earnings only started in August. After the acquisition, Enterprise value stands at $31.03B against a $23.60B market cap.
EPS HISTORY:
2006: $0.62
2011: $0.57
2016: $0.91
2020: $1.67
2023: $2.81
2024: $3.84
2025: $4.26
2026 estimate: $4.49
2027 estimate: $4.85
2028 estimate: $5.34
EPS growth has depended on the strength of the broader insurance market. No growth for five years from 2006 to 2011. Then $0.57 to $4.26 over 14 years, about 15% a year. The 54% jump in 2017 and 16% drop in 2018 on the chart are the 2017 tax law passing through the numbers. Analysts model 5%, 8%, and 10% from here. The dividend went from $0.11 to $0.62 over the same 20 years, requiring roughly 15% of earnings.
THE CATCH:
Revenue grew 35% in Q1 and 30% in Q2. Almost all of that growth was from acquisitions. The core Brown & Brown business grew 10.4% in 2024, 2.8% in 2025, was flat in Q1 of 2026, and -0.7% in Q2, excluding contingent commissions. A broker's commission is a percentage of the premium, so when rates fall, the same clients pay less. Catastrophe property rates fell 15% to 35% last quarter, and management expects more. The last time rates fell like this is the 2006 to 2011 stretch on the chart.
The company bought Accession Risk Management for $9.825 billion, its largest deal to date, closing on August 1, 2025. It paid with about $4 billion of new stock sold at $102 a share in June 2025, another $1.2 billion of stock issued to Accession's owners at $110.57, and debt. The stock is at $70.53 today, 31% below the offering price, and the company has since bought back about $500 million of shares in the 60s. A $400 million note comes due in December. The market's other worry is that software replaces the middleman. Management announced AI partnerships this year and says the benefits will arrive in three to five years.
In its favor: adjusted EPS still grew 7.8% in the first quarter and 3.9% in the second, with zero organic growth, because Accession's earnings came in. The FAST Graphs Analyst Scorecard shows Brown & Brown beat both the one and two-year estimates 55% of the time and hit estimates the other 45%, with no misses.
On the Forecasting tab, 2028 EPS of $5.34 at the 5-year normal P/E of 26.31x results in a share price of $140.37, a 37.57% estimated annual return with dividends.
At the 20-year normal P/E of 22.64x, the share price would be $121. At the 15x fair value multiple, it would be $80.
These scenarios are based on analyst estimates, which can be wrong. They are not predictions or recommendations to buy or sell the stock.

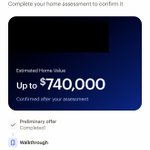
This is hilarious literally 7 minutes after posting something nice about $OPEN I got emailed this updated offer estimate from them 😂😂.
Gotta be a coincidence but still funny.

I actually think $OPEN could outperform from here over the next 5+ years.
It’s a heck of a lot more attractive now than at $10 but it should be treated and sized for what it is.
A speculative position and you should be ready to lose 100% of whatever you have invested in it.
I actually think $OPEN could outperform from here over the next 5+ years.
It’s a heck of a lot more attractive now than at $10 but it should be treated and sized for what it is.
A speculative position and you should be ready to lose 100% of whatever you have invested in it.
$META did it.
Short term pain for them to crush competitors who don’t have the same balance sheet strength for long-term gain.
Will look to re-enter $META soon. Yes I sold before earnings (shared it in an update to subscribers)
I think we’re in for a pretty brutal rest of the week leading into $META reporting and Zuck giving bearish commentary.
Why? Because he’s a savage and bearish sentiment will crush his competitors.
META has the balance sheet to withstand it but his competitors are strapped with debt and/or are trying to IPO (OpenAI/Anthropic)
Classic short-term pain/long-term gain mindset from Zuck.
I’ll likely start looking to deploy some cash Friday afternoon or next week depending on how this week goes but I’ll do it slowly.
No reason to rush into it.


I have nothing against $OPEN but I think management pumped the stock and played the stupid $OPEN army thing up way too much and that Rabois clown is a total jerk to anyone who isn’t a fanboy.
With that being said, this isn’t a good look.
Wouldn’t be surprised to see them acquired for their data by a real biz like Zillow or Redfin.
Everyone was pumped about @nejatian’s time at $SHOP but I really don’t think he was that influential there.
Tobi and Harley are legends. It’s a mistake to extrapolate $SHOP success to $OPEN
xitter.cf/lucmatheson/status/211…
Quick $META earnings review 100% free and X will let you read it right here in the app.
austin.substack.com/p/meta-q…
Pretty decent quarter from $META but one yellow flag is that they’re raising FY revenue guidance by less than they beat this Quarter.
That means Q4 is actually softer than previously expected.
Could be a slight sign of growth slowing down more than expected.
Excited to watch the momentum for @hebbia and @gsivulka.
If you’re looking to streamline your firm’s research you should definitely check them out.
🤝 Paid partnership

Q3 was the biggest quarter in Hebbia's history, and I’m incredibly proud of the team that made it happen.
• New ARR tripled quarter over quarter
• Daily active users grew 5x
• Gross revenue retention exceeded 95%
The usage growth is especially exciting to me. More people are using Hebbia, and a greater share are coming back every day.
We also shipped three major launches:
• Max, an AI teammate that works the way your firm works.
• Matrix 2.0, our next generation of agents for research and analysis.
• Our API and MCP server, bringing Hebbia into the tools our customers already use and build.
Seeing the team deliver these products while more customers make Hebbia part of their daily work makes this quarter particularly meaningful. Last week alone, we won five new banks to kick off the quarter.
Thank you to our customers for trusting us with your work, and to everyone at Hebbia for making this our strongest quarter yet.

It is difficult to exaggerate the amount of damage done to $OPEN shareholders since @nejatian became CEO (down 85%)

$META could single handedly hurt OpenAI’s next funding round with disappointing Muse numbers and negative commentary from Zuck when they report tomorrow.

