

It’s not rock science… It’s #LiquidityLogic™ Created by @mathovermyth
Toidy Toid n Toid
Joined December 2024
- Tweets213
- Following2
- Followers46
- Likes1.5K




Pinned Tweet
Welcme to #LiquidityLogic™
Cheat Code Levels for any HTF Candle
1. High
2. Low
3. Open
4. Close
5. EQ (Low - High)
6. Body EQ (Open -Close)
7. Bearish Liquidity Pool EQ (O/C - High)
8. Bullish Liquidity Pool EQ (O/C - Low)
Instant clarity
Get yourself some
$NQ #NQ_F Everything’s Textbook 🧲
It’s not Rocket Science 🚀🧬
It’s #LiquidityLogic™💧🧠
—————
#FuturesTrading #NQ $NDX $QQQ


LiquidityLogic™ retweeted
#NQ_F Target Acquired: Prior Year High ☑️
“New Weekly Bearish Imbalance should send price down into Discount and bounce off the 2025 High.”
—LiLo (10/23/26)
The sequence is the sequence 🌀
It’s not Rocket Science 🚀🧬
It’s #LiquidityLogic™ 💧🧠
—————
#NQ $NQ #QQQ $QQQ


$NQ #NQ_F Charts with Quarterly Levels
New Weekly Bearish Imbalance should send price down into Discount and bounce off the 2025 High, which is also a Bullish Break Bumper.
The sequence is the sequence 🌀
It’s not Rocket Science 🚀🧬
It’s #LiquidityLogic™ 💧🧠
————————
#TradingSetup $QQQ $NDX $COMP


LiquidityLogic™ retweeted
My $MSTR Paper doesn’t even tackle the fiduciary breach from a corporate governance perspective. Just the reactor core math.
Saylor’s a special kind of fraudster.
Watched him do it during the DotCom Bubble, or what I call Tech Wreck 1.0, and now he’s trying to lead #TechWreck2.
The 2000 and 2008 Lineage
This exact loop mirrors the Dot-Com crash of 2000. Companies like Inktomi and WorldCom traded at massive, astronomical multiples. They used their highly inflated stock as currency to acquire other tech companies, or to buy telecommunications capacity and advertising traffic from each other. This circular spending created fake revenue growth, which pushed stock prices higher, allowing them to issue even more overvalued shares to keep the loop going.
It is also identical to the CMBS/CDO structural loop of 2008. In the lead-up to the Global Financial Crisis, investment banks took underlying mortgage cash flows, sliced them into complex tranches, and manufactured "synthetic CDOs"—essentially using the derivative products to buy more underlying mortgage debt, pushing real estate prices up artificially. The derivative market became larger than the actual physical asset market supporting it.
Phase B: Navigating the Xenon Pit with "Digital Credit"
In the Chernobyl timeline, the disaster began when operators tried to reduce power too quickly, inadvertently trapping the reactor core in a xenon pit. Xenon-135 is a powerful neutron absorber; it "poisoned" the core and choked out the reaction. Desperate to force the power back up to complete their test, the operators manually yanked out nearly all of the reactor's boron control rods, leaving the core profoundly unstable and stripped of its safety buffers.
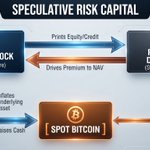
Over the past year, $MSTR encountered its own financial xenon pit. As structural market dynamics matured and the launch of spot #Bitcoin ETFs saturated the landscape, institutional capital no longer needed an expensive corporate proxy to gain exposure to crypto. The premium to NAV aggressively compressed, flatlining toward 1.0x parity or dipping into a technical discount.
A compressed premium is fatal to the Paddy's Dollars loop: you cannot accretively buy Bitcoin by printing stock if your stock trades below the value of the Bitcoin you already own. To fight this structural poisoning, management systematically pulled out the financial control rods. They transitioned from basic equity dilution into aggressive, complex financial engineering.
To override the xenon pit, the operators constructed a massive, multi-layered senior liability stack:
—Convertible Bonds: Billions in debt obligations that convert to equity if stock prices rise, but remain hard liabilities if they fall.
—Programmable Digital Credit (The Strife/Strike Series): Transitioning the company’s perpetual preferred stock into a 24/7/365 daily compounding dividend scheme. Next-business-day payouts were engineered to mimic tokenized ecosystem yields, forcing legacy markets to afford MSTR a premium based on synthetic cash flow.
—The Parity Defense: Actively utilizing corporate capital to conduct billions in repurchases of their own credit tranches to artificially defend the par value of their debt and keep the core mNAV premium floating between 1.13x and 1.21x.
This mirrors the frantic late-stage actions of 2007-era mortgage desks. When the underlying subprime mortgages started failing, the "xenon pit" of the housing market began to choke the system. To keep the machine running, banks didn't stop printing CDOs—they started engineering Synthetic CDOs-squared (derivatives of derivatives) and offering hyper-complex credit default swaps to trick institutional buyers into providing liquidity, pulling the final safety buffers out of the banking sector.
Phase C: The Accounting Distortion: Turning Hidden Liabilities into Liquidity
When Bernie Ebbers ran WorldCom, Dennis Kozlowski led Tyco, and Gary Winnick built Global Crossing, they didn't just rely on a circular network capacity economy; they aggressively utilized accounting manipulation, off-balance-sheet vehicles, and cost capitalization to alter their liquidity ratios and mask massive operational deficits.
———
🧵8/12 $BTC #BTC $BTCUSD #BTCUSDT


LiquidityLogic™ retweeted
Based on the Strategic Analysis of $MSTR published by @mathovermyth under the #LiquidityLogic framework, a breakdown where #Bitcoin ($BTC) falls below $75,000 while #MSTR drops below $120 marks the complete inversion of @Saylor’s recursive capital flywheel.
In this specific threshold regime, the corporate structure transitions from an exponential value creator into an unstable, low-power state. The white paper outlines three critical systemic failure modes triggered by these price points:
1. Inversion of the "Saylor Loop" (Premium Compression)
The Premium Death Spiral: The primary mechanism driving MSTR's multi-billion dollar premium over its Net Asset Value (mNAV) is the market's expectation of infinite, accretive token purchases per share.
The Break-Even Threshold: As #BTC dips under $75K—sliding right against MSTR's aggregate historical cost baseline—and the equity drops below $120, the market rapidly begins stripping away this premium.
Asset Parity Repricing: Without the premium, MSTR loses its unique dual-engine capability to issue expensive stock to buy cheap Bitcoin, forcing the enterprise value to contract to match only its raw digital holdings.
2. Fiat Revenue Deficit vs. Debt Service
The Legacy Engine Math: The white paper highlights that MicroStrategy's legacy enterprise software utility generates roughly $500 million in total annual revenue.
The Unfunded Capital Stack: This native cash flow is mathematically incapable of covering the massive debt service required by the company's aggressive, low-coupon convertible notes and capital stack engineering.
Valuation Dependency: Below these key technical levels, the firm cannot rely on At-The-Market (ATM) equity issuance without punishing dilution, creating a structural cash-flow deficit that relies purely on expanding credit markets to roll over liabilities.
3. The Collapse of "Project Paddy's Dollars"
The Reflexive Illusion: The white paper mockingly categorizes the architecture as Project "Paddy's Dollars"—referencing a self-sustaining currency loop that only works as long as external participants keep injecting value into the ecosystem.
Systemic Failure Regime: Once both thresholds breach, reflexivity works in reverse. Lower stock prices stop the accretive buying machine; lack of buying pressure stalls Bitcoin; and a stalling Bitcoin further compresses the stock multiple. The financial reactor effectively running out of kinetic energy, locking shareholders into a vehicle holding highly volatile digital commodities encumbered by heavy senior claims.
LiquidityLogic™ retweeted
Conclusion
The structural "bomb" inside MicroStrategy was built by the operators themselves the moment they tied a cyclical, highly leveraged fiat debt structure to a volatile, non-yielding digital asset—re-using the exact blueprints that broke Wall Street in 2000 and 2008. The operators have successfully pulled the reactor out of its stagnation pit using synthetic credit engineering, but they have stripped the mechanism of all independent safety buffers. The entire multi-billion-dollar architecture now runs on a razor-thin margin of error, wholly dependent on the assumption that global liquidity will return to re-inflate risk assets before the compounding weight of their own "Paddy’s Dollars" triggers a core melt.
———
🧵11/12 $BTC #BTC $BTCUSD #BTCUSDT
LiquidityLogic™ retweeted
Forgot to attach.

Phase E: The High-Timeframe Macro Squeeze (The Deflationary Meltdown)
The ultimate failure mode of the MSTR reactor does not look like a sudden, fiery explosion; it takes the form of a slow, crushing deflationary black hole triggered by high-timeframe macro realities.
In 2000, the trigger was the Federal Reserve aggressively raising interest rates, which starved the dot-com startups of easy venture capital. Once the "outsiders" stopped injecting fresh fiat, the circular stock-buying loop stopped, and companies like WorldCom couldn't pay their bills. In 2008, the trigger was a minor tick upward in nationwide mortgage defaults. Because the financial products were hyper-leveraged and stacked on top of each other, a 5% drop in real estate values caused a 100% destruction of the derivative tranches below them.
If the global economy enters a prolonged stagflationary regime—where higher interest rates, surging crude oil, and geopolitical friction cause capital to rotate cleanly out of risk assets and into safe, high-yielding risk-free government bonds—the entire "Saylor Bank" architecture undergoes an inversion:
If #Bitcoin enters a prolonged, multi-year sideways grind or a deep bear market under a risk-off macro regime, time becomes the ultimate neutron poison. Management currently boasts that they hold a fortress buffer with enough USD reserves to cover 3.4 years of interest and dividend obligations, noting that Bitcoin would have to drop 78% to hit their absolute liability floor.
However, the invisible liability is time. If the market enters a grinding macro discount range, the 3.4-year fiat cash runway will steadily burn away to service the compounding 365-day preferred dividend mandates. Since they can no longer print stock at a premium to save themselves, the hidden liability stack begins systematically consuming the asset stack.
Just like the collapsed tech giants of 2000, $MSTR will be legally forced to liquidate its underlying core treasury to pay off senior creditors, precipitating a cascading liquidity failure.
———
🧵10/12 $BTC #BTC $BTCUSD #BTCUSDT
LiquidityLogic™ retweeted
Phase E: The High-Timeframe Macro Squeeze (The Deflationary Meltdown)
The ultimate failure mode of the MSTR reactor does not look like a sudden, fiery explosion; it takes the form of a slow, crushing deflationary black hole triggered by high-timeframe macro realities.
In 2000, the trigger was the Federal Reserve aggressively raising interest rates, which starved the dot-com startups of easy venture capital. Once the "outsiders" stopped injecting fresh fiat, the circular stock-buying loop stopped, and companies like WorldCom couldn't pay their bills. In 2008, the trigger was a minor tick upward in nationwide mortgage defaults. Because the financial products were hyper-leveraged and stacked on top of each other, a 5% drop in real estate values caused a 100% destruction of the derivative tranches below them.
If the global economy enters a prolonged stagflationary regime—where higher interest rates, surging crude oil, and geopolitical friction cause capital to rotate cleanly out of risk assets and into safe, high-yielding risk-free government bonds—the entire "Saylor Bank" architecture undergoes an inversion:
If #Bitcoin enters a prolonged, multi-year sideways grind or a deep bear market under a risk-off macro regime, time becomes the ultimate neutron poison. Management currently boasts that they hold a fortress buffer with enough USD reserves to cover 3.4 years of interest and dividend obligations, noting that Bitcoin would have to drop 78% to hit their absolute liability floor.
However, the invisible liability is time. If the market enters a grinding macro discount range, the 3.4-year fiat cash runway will steadily burn away to service the compounding 365-day preferred dividend mandates. Since they can no longer print stock at a premium to save themselves, the hidden liability stack begins systematically consuming the asset stack.
Just like the collapsed tech giants of 2000, $MSTR will be legally forced to liquidate its underlying core treasury to pay off senior creditors, precipitating a cascading liquidity failure.
———
🧵10/12 $BTC #BTC $BTCUSD #BTCUSDT
LiquidityLogic™ retweeted
While $MSTR remains structurally compliant with GAAP regulations, the economic reality of its capital architecture creates what forensic analysts view as a hidden, off-balance-sheet liquidity trap that directly mimics the early 2000s accounting defaults:
The WorldCom Cost Transformation
WorldCom famously achieved an illusion of health by capitalizing ordinary "line costs" (operating interconnect fees) as long-term assets, boosting net income while hiding a bleeding operational cash flow deficit.
MicroStrategy executes a legal version of this accounting distortion. Because their multi-billion-dollar convertible notes carry zero or near-zero coupons, they avoid mapping ongoing interest drag as an immediate operating cash expense. On paper, their corporate liquidity ratio sits at an immaculate 5.5. However, this current ratio is entirely synthetic—propped up not by a profitable software business, but by a $5.1B fiat cash reserve raised entirely by issuing more debt and preferred obligations.
The Global Crossing/Tyco Synthetic Swap
Global Crossing inflated its metrics through circular "capacity swaps"—selling fiber bandwidth to a competitor while simultaneously buying the same amount back, creating fake revenue out of thin air. Tyco relied on unrecorded, off-balance-sheet Special Purpose Vehicles (SPVs) to hide liabilities. MSTR operates a permanent, structural capacity swap with the global digital asset market. Under current accounting rules, MSTR carries its 848,517 #Bitcoin at an archaic historical cost-minus-impairment on its audited GAAP balance sheet.
The Hidden Liability Dislocation
This creates an immense, unrecorded dependency. Because the underlying assets are valued on the fair market at over $65B, the company's true liquidity and survival ratio are tied completely to an off-balance-sheet reality: the real-time spot liquidity of Bitcoin. Because the legacy enterprise software company cannot generate the organic cash flow required to maintain a multi-billion-dollar debt architecture, MSTR has tethered its entire survival to an external, volatile asset class that does not map to traditional balance sheet safety tests.
Phase D: The Upcoming "AZ-5" Scenario — The MSCI Catalyst and Retail Panic
The ultimate crisis in an RBMK reactor occurs when the core enters a runaway power excursion, and the operators press the AZ-5 emergency button to insert the control rods back into the core. Due to a fatal design flaw, the tips of the rods were made of graphite, which briefly displaced the coolant water, triggering a massive, instantaneous localized power spike that fractured the channels and blew the roof off the building.
The impending global index provider catalysts (such as MSCI's finalized framework targeting "non-operating companies") represent a structural threat to the reactor's grid certification. Because MSTR's core enterprise software business has shrunk to a rounding error relative to its treasury, the company squarely fails MSCI's new asset screens and financial ratios.
While existing member "two-year trailing buffer rules" protect MSTR from immediate automated deletion on November 11, the behavioral psychology of retail investors acts as an unscripted operator inside the control room:
—The Retail Panic (The Graphite Tip Impact): Anticipating an institutional index dump on the effective date, anxious retail investors try to front-run passive ETFs by panic-selling their shares first.
—The Premium Inversion: A rapid retail-driven exit immediately crushes the mNAV premium, driving MSTR into a deep discount.
—The Flywheel in Reverse: Once the stock trades at a persistent discount, the Paddy’s Dollars loop completely breaks. They cannot issue equity to buy more Bitcoin without triggering cataclysmic dilution. The primary narrative engine of the stock stalls out.
———
🧵9/12 $BTC #BTC $BTCUSD #BTCUSDT

LiquidityLogic™ retweeted
The 2000 and 2008 Lineage
This exact loop mirrors the Dot-Com crash of 2000. Companies like Inktomi and WorldCom traded at massive, astronomical multiples. They used their highly inflated stock as currency to acquire other tech companies, or to buy telecommunications capacity and advertising traffic from each other. This circular spending created fake revenue growth, which pushed stock prices higher, allowing them to issue even more overvalued shares to keep the loop going.
It is also identical to the CMBS/CDO structural loop of 2008. In the lead-up to the Global Financial Crisis, investment banks took underlying mortgage cash flows, sliced them into complex tranches, and manufactured "synthetic CDOs"—essentially using the derivative products to buy more underlying mortgage debt, pushing real estate prices up artificially. The derivative market became larger than the actual physical asset market supporting it.
Phase B: Navigating the Xenon Pit with "Digital Credit"
In the Chernobyl timeline, the disaster began when operators tried to reduce power too quickly, inadvertently trapping the reactor core in a xenon pit. Xenon-135 is a powerful neutron absorber; it "poisoned" the core and choked out the reaction. Desperate to force the power back up to complete their test, the operators manually yanked out nearly all of the reactor's boron control rods, leaving the core profoundly unstable and stripped of its safety buffers.
Over the past year, $MSTR encountered its own financial xenon pit. As structural market dynamics matured and the launch of spot #Bitcoin ETFs saturated the landscape, institutional capital no longer needed an expensive corporate proxy to gain exposure to crypto. The premium to NAV aggressively compressed, flatlining toward 1.0x parity or dipping into a technical discount.
A compressed premium is fatal to the Paddy's Dollars loop: you cannot accretively buy Bitcoin by printing stock if your stock trades below the value of the Bitcoin you already own. To fight this structural poisoning, management systematically pulled out the financial control rods. They transitioned from basic equity dilution into aggressive, complex financial engineering.
To override the xenon pit, the operators constructed a massive, multi-layered senior liability stack:
—Convertible Bonds: Billions in debt obligations that convert to equity if stock prices rise, but remain hard liabilities if they fall.
—Programmable Digital Credit (The Strife/Strike Series): Transitioning the company’s perpetual preferred stock into a 24/7/365 daily compounding dividend scheme. Next-business-day payouts were engineered to mimic tokenized ecosystem yields, forcing legacy markets to afford MSTR a premium based on synthetic cash flow.
—The Parity Defense: Actively utilizing corporate capital to conduct billions in repurchases of their own credit tranches to artificially defend the par value of their debt and keep the core mNAV premium floating between 1.13x and 1.21x.
This mirrors the frantic late-stage actions of 2007-era mortgage desks. When the underlying subprime mortgages started failing, the "xenon pit" of the housing market began to choke the system. To keep the machine running, banks didn't stop printing CDOs—they started engineering Synthetic CDOs-squared (derivatives of derivatives) and offering hyper-complex credit default swaps to trick institutional buyers into providing liquidity, pulling the final safety buffers out of the banking sector.
Phase C: The Accounting Distortion: Turning Hidden Liabilities into Liquidity
When Bernie Ebbers ran WorldCom, Dennis Kozlowski led Tyco, and Gary Winnick built Global Crossing, they didn't just rely on a circular network capacity economy; they aggressively utilized accounting manipulation, off-balance-sheet vehicles, and cost capitalization to alter their liquidity ratios and mask massive operational deficits.
———
🧵8/12 $BTC #BTC $BTCUSD #BTCUSDT
LiquidityLogic™ retweeted
C. The Preferred Liquidity Squeeze: With the equity printer disabled, the fixed $1.712B annual dividend and senior note obligation bears down fully on a software segment that brings in just $500M in revenue. This forces the company to launch its BTC Monetization Program, marking the first time the corporate vehicle must sell from its core #Bitcoin holdings into a down market to service fiat liabilities.
Phase 9: The September 2027 Put Option Wall — The Core Detonation
The final phase of the structural breakdown occurs in September 2027, when the initial $1.01B tranche of Senior Convertible Notes reaches its investor put option maturity wall.
A. The Put Activation: If the stock is trading below its strike price post-MSCI exclusion, bondholders will exercise their put options to demand full principal repayment in cash rather than converting to depressed shares.
B. The Cash Run: Facing a $1.01B immediate cash demand with a frozen equity machine, the company will be legally forced to liquidate a massive portion of its Bitcoin reserve, turning the private balance sheet strain into an immediate liquidity shock for the broader digital asset market.
———
Addendum Document: The RBMK-Paddy Flywheel — MicroStrategy Crypto Reactor Failure Modes
The structural architecture of Michael Saylor’s MicroStrategy ($MSTR) represents a historical convergence of two seemingly incompatible frameworks: the volatile, self-reinforcing physics of a Soviet RBMK-1000 nuclear reactor and the circular economic logic of "Paddy’s Dollars."
By utilizing legacy equity markets to issue high-yield corporate liabilities to purchase a volatile, non-yielding base asset (Bitcoin), management has built a multi-billion-dollar synthetic central bank. In an era of infinite liquidity, this mechanism functions as a money-printing machine.
However, this is not a novel invention; it is the exact structural loop that doomed the Dot-Com giants in 2000 (who used overvalued stock as collateral to buy competitor stock and traffic) and the global financial system in 2008 (where Commercial Mortgage-Backed Securities [CMBS] and CDOs used circular, synthetic credit tranches to engineer fake yield out of underlying toxic assets).
Under the weight of high-timeframe (HTF) macro shifts—sticky inflation, rising crude oil, tightening interest rates, and a structural rotation out of risk assets—the "self-sustaining corporate economy" begins to display the exact prompt-critical instabilities that doomed Chernobyl's Reactor #4.
Phase A: The Design — The Positive Void Coefficient of Paddy's Dollars
To understand why the reactor is inherently volatile, one must look at its core design. In a standard RBMK reactor, the fundamental design flaw was a positive void coefficient.
Usually, if a reactor loses its water coolant (forming steam "voids"), the nuclear reaction slows down. In an RBMK, steam voids accelerate the reaction.
In the financial architecture of MSTR, the Premium to Net Asset Value (mNAV) acts as the positive void coefficient.
When MSTR trades at a premium (e.g., 1.5x or 2.0x the value of its underlying Bitcoin), the operators print new shares via At-The-Market (ATM) offerings. They sell these overpriced shares to the market, take the hard cash, and dump it directly into the spot Bitcoin order books. This raises the "Bitcoin per share" value for existing holders.
This is the birth of the Paddy's Dollars Loop:
1. The company prints synthetic equity/credit instruments ("Paddy’s Dollars") to distribute to the market.
2. It takes the cash from those instruments and pumps it into the crypto ecosystem, artificially forcing the underlying asset (Bitcoin) upward.
3. Because Bitcoin goes up, the book value of MicroStrategy’s treasury skyrockets.
4: Traditional market participants see a growing treasury, buy more stock, and widen the mNAV premium.
5. Management prints more stock to buy more Bitcoin.
———
🧵7/12 $BTC #BTC $BTCUSD #BTCUSDT

LiquidityLogic™ retweeted
Phase 7: The Systemic Triggers and Catalysts
The financial structure is highly sensitive to price declines, with specific mathematical boundaries that turn operational pressure into an outright structural break.
The Sensitivity Boundary Thresholds
—The -20% Threshold (~$104.40): An immediate 20% drawdown from the current trading price ($130.51) pushes 100% of the company's $6.71B convertible debt stack completely "out-of-the-money". The lowest outstanding conversion strike sits at $183.19 (2028 notes), with later tranches extending up to $672.40. At this boundary, the embedded equity options drop to a delta of zero, and the entire stack reverts into straight corporate debt that must be repaid exclusively in cash.
—The -25% Threshold (~$97.88): A 25% drop forces the stock across a psychological and mathematical event horizon: breaking below a 1.0x mNAV ratio. The vehicle officially enters a structural discount to NAV. At this point, executing any further ATM common share offerings becomes actively value-destructive and dilutive to the underlying $BTC-per-share metric, permanently freezing the company's main financial engine.
—The -30% Threshold (~$91.36): A 30% drop triggers structural asset-maintenance and debt-service coverage covenants embedded in their senior notes. Once breached, the company's $5.07B USD cash reserve can be legally locked or restricted by bond trustees to protect creditors. The company instantly loses access to its primary rainy-day fund.
—The -35% Threshold (~$84.83): At a 35% decline, the stock drops below its implied debt floor, forcing convertible arbitrage hedge funds to systematically dump their long equity equity blocks under risk-management mandates, aggregating a non-fundamental cascading sell-off.
The Simultaneous #Bitcoin Retracement Trap
This equity sensitivity is compounded by the company's aggressive buying campaigns, which pushed its overall average Bitcoin purchase basis to approximately $75,446 per coin across its treasury.
If a broader macro-equity or AI bubble liquidation occurs simultaneously with a moderate 8% to 10% pullback in #BTC to ~$74,000, the entire treasury falls underwater.
Under fair-value rules, the company must mark this asset degradation to market, replacing billions in paper profits with massive, flashing quarterly operating losses on its GAAP income statement, completely locking up secondary institutional credit markets.
Phase 8: The Inevitable Mathematical Doom Loop
The structural unwind of the vehicle behaves as a deterministic chain reaction, mapping directly to historic financial collapses and physical engineering failures.
The November 11 MSCI Catalyst
On October 15, 2026, global index provider MSCI finalized its "Non-Operating Company" eligibility framework, explicitly targeting corporate shells whose operating assets comprise less than 50% of their balance sheet. Strategy, Inc. fails this core screen immediately.
On November 11, 2026, MSCI is scheduled to publish its official deletion list, with forced index rebalancing taking effect at the market close on November 30, 2026. This event will trigger an immediate, non-negotiable $2.8 billion to $8.8 billion structural capital flight from automated passive index funds.
The Capital Flight Unwind Sequence
A. The Passive De-Leveraging Wave: Passive index funds operating under a strict physical replication mandate are legally required to liquidate their holdings entirely by the close of November 30, 2026. This sudden influx of block market sell orders overwhelms existing market-maker bids, forcing the stock to drop sharply.
B. The Breaking of the Multiple: This structural selling breaks below the mNAV parity ceiling, driving the equity into a deep structural discount (< 1.0x NAV). The moment the market multiple slips below asset parity, the At-The-Market (ATM) issuance engine becomes value-destructive, completely cutting off the company's primary way to raise capital.
———
🧵6/12 $BTCUSD #BTCUSDT

LiquidityLogic™ retweeted
By scaling $MSTR Strategy, Inc. into a self-styled "Bitcoin Central Bank," Saylor has managed to invert the core philosophy of the asset class, introducing three direct structural ironies:
—Fractional-Reserve Crypto-Banking: Central banks inflate economic bubbles by issuing un-backed credit against thin collateral. Under its "Digital Credit" framework, Strategy issues billions of dollars in preferred stock ($STRC) and convertible notes, effectively printing synthetic dollar-denominated liabilities layered on top of its Bitcoin base. The company has re-introduced fractional, leveraged architecture to an asset designed strictly for absolute, transparent scarcity.
—The Quantitative Easing Loop: Saylor aggressively critiques the Federal Reserve for printing fiat currency to purchase government bonds and manipulate bond yields. Yet, the "Saylor Loop" is an identical mechanism. Strategy systematically uses its own printed equity and corporate paper to purchase spot #Bitcoin, artificially bidding up the price of its underlying collateral to inflate its own net worth. It is corporate Quantitative Easing in its purest form.
—Re-Introducing Systemic Counterparty Risk: Bitcoin's foundational promise is "not your keys, not your coins"—the complete elimination of counterparty risk. By aggregating nearly 1% of the total circulating Bitcoin supply inside a single corporate balance sheet wired to Wall Street credit covenants, Strategy has created a multi-billion-dollar point of failure. If the September 2027 put option wall triggers forced liquidations, traditional fiat debt rules will legally compel the company to dump its treasury, dragging the entire decentralized crypto ecosystem down with it.
Phase 6: The Philosophical Irony — The Hard Money Mirage
Beyond the systemic ironies of banking mechanics lies a glaring philosophical contradiction in Saylor’s foundational rhetoric.
In public keynote addresses and financial media appearances, Saylor routinely shits on “fiat” currency, describing the U.S. dollar as a melting ice cube, a dying economic system, and an inherently toxic web of unbacked government decrees. In its place, he champions Bitcoin as "sound money" and "digital energy"—a pristine, un-corruptible reality rooted in absolute cryptographic proof.
Yet, the actual execution of his corporate strategy reveals a hypocritical reliance on the very system he demeans:
—The Monopoly of an Imaginary Internet Algorithm: Saylor’s core objective is to use a legacy corporate wrapper to systematically monopolize an abstract ledger—an internet consensus algorithm. He attempts to reframe this concentration of digital lines of code as the ultimate expression of immutable property. However, the corporate vehicle he uses to corner this market does not run on Bitcoin. It is completely plugged into, and dependent on, the traditional fiat plumbing.
—The Fiat Lifeline: While praising Bitcoin as the only true store of value, Strategy, Inc. cannot survive on a digital-token standard. The company's massive $1.712B annual overhead and preferred dividend obligation must be settled exclusively in traditional, fiat U.S. Dollars. Bitcoin cannot be used to pay off Wall Street fixed-income creditors or satisfy Delaware corporate tax liabilities.
—The Synthetic Yield Illusion: Saylor boasts of generating an abstract, non-GAAP mathematical "Bitcoin Yield" to prove his company is building wealth. But this metric is an ideological mirage. By financing his operations through high-yield dollar preferred shares (STRC) and billions in dollar-denominated convertible notes, Saylor hasn't escaped the fiat matrix—he has hyper-financialized it. He is printing unbacked corporate paper to hoover up a decentralized token, guaranteeing that if the fiat liquidity taps ever dry up, his "sound money" fortress will be dismantled by the exact legacy legal codes and margin calculations he claims to have outsmarted.
———
🧵5/12 $BTC #BTC $BTCUSD #BTCUSDT
LiquidityLogic™ retweeted
The ultimate irony of the "Bitcoin Central Bank":
Satoshi embedded the 2009 bank bailout headline into the Genesis block to escape debt-based fractional banking.
Now, Strategy has recreated the exact same fiat apparatus on top of Bitcoin:
1. Fractional "Digital Credit": Layering billions in convertible debt and high-yield preferred shares ($STRC) over a single corporate vault.
2. Corporate Quantitative Easing: Printing corporate paper out of thin air to bid up the collateral backing that same paper.
3. Cantillon Hierarchy: Insiders cash out via 10b5-1 plans; bondholders get senior cash put rights; retail absorbs -617 sats/share in dilution to bail out the capital stack.
Saylor used maximalist sound-money rhetoric to absorb Bitcoiner retail capital, only to build an encumbered, centralized corporate bank at a state-regulated custodian.
Bitcoin was built to kill central banking, not become the collateral for a new one.
Hold your own keys.
By scaling $MSTR Strategy, Inc. into a self-styled "Bitcoin Central Bank," Saylor has managed to invert the core philosophy of the asset class, introducing three direct structural ironies:
—Fractional-Reserve Crypto-Banking: Central banks inflate economic bubbles by issuing un-backed credit against thin collateral. Under its "Digital Credit" framework, Strategy issues billions of dollars in preferred stock ($STRC) and convertible notes, effectively printing synthetic dollar-denominated liabilities layered on top of its Bitcoin base. The company has re-introduced fractional, leveraged architecture to an asset designed strictly for absolute, transparent scarcity.
—The Quantitative Easing Loop: Saylor aggressively critiques the Federal Reserve for printing fiat currency to purchase government bonds and manipulate bond yields. Yet, the "Saylor Loop" is an identical mechanism. Strategy systematically uses its own printed equity and corporate paper to purchase spot #Bitcoin, artificially bidding up the price of its underlying collateral to inflate its own net worth. It is corporate Quantitative Easing in its purest form.
—Re-Introducing Systemic Counterparty Risk: Bitcoin's foundational promise is "not your keys, not your coins"—the complete elimination of counterparty risk. By aggregating nearly 1% of the total circulating Bitcoin supply inside a single corporate balance sheet wired to Wall Street credit covenants, Strategy has created a multi-billion-dollar point of failure. If the September 2027 put option wall triggers forced liquidations, traditional fiat debt rules will legally compel the company to dump its treasury, dragging the entire decentralized crypto ecosystem down with it.
Phase 6: The Philosophical Irony — The Hard Money Mirage
Beyond the systemic ironies of banking mechanics lies a glaring philosophical contradiction in Saylor’s foundational rhetoric.
In public keynote addresses and financial media appearances, Saylor routinely shits on “fiat” currency, describing the U.S. dollar as a melting ice cube, a dying economic system, and an inherently toxic web of unbacked government decrees. In its place, he champions Bitcoin as "sound money" and "digital energy"—a pristine, un-corruptible reality rooted in absolute cryptographic proof.
Yet, the actual execution of his corporate strategy reveals a hypocritical reliance on the very system he demeans:
—The Monopoly of an Imaginary Internet Algorithm: Saylor’s core objective is to use a legacy corporate wrapper to systematically monopolize an abstract ledger—an internet consensus algorithm. He attempts to reframe this concentration of digital lines of code as the ultimate expression of immutable property. However, the corporate vehicle he uses to corner this market does not run on Bitcoin. It is completely plugged into, and dependent on, the traditional fiat plumbing.
—The Fiat Lifeline: While praising Bitcoin as the only true store of value, Strategy, Inc. cannot survive on a digital-token standard. The company's massive $1.712B annual overhead and preferred dividend obligation must be settled exclusively in traditional, fiat U.S. Dollars. Bitcoin cannot be used to pay off Wall Street fixed-income creditors or satisfy Delaware corporate tax liabilities.
—The Synthetic Yield Illusion: Saylor boasts of generating an abstract, non-GAAP mathematical "Bitcoin Yield" to prove his company is building wealth. But this metric is an ideological mirage. By financing his operations through high-yield dollar preferred shares (STRC) and billions in dollar-denominated convertible notes, Saylor hasn't escaped the fiat matrix—he has hyper-financialized it. He is printing unbacked corporate paper to hoover up a decentralized token, guaranteeing that if the fiat liquidity taps ever dry up, his "sound money" fortress will be dismantled by the exact legacy legal codes and margin calculations he claims to have outsmarted.
———
🧵5/12 $BTC #BTC $BTCUSD #BTCUSDT

Strategic Analysis of ($MSTR) Strategy’s Financial Reactor
Project "Paddy’s Dollars" — A Comprehensive Synthesis of Capital Stack Engineering, Accounting Reflexivity, and Systemic Failure Modes
1. Executive Summary
Originally an asset-light enterprise software utility, Strategy, Inc. (formerly MicroStrategy) engineered a dual-engine corporate architecture that acts as a hybrid leveraged #Bitcoin holding company and a digital asset central bank.
By exploiting a persistent market-to-net-asset-value (mNAV) premium via continuous At-The-Market (ATM) common equity issuance and low-coupon convertible notes, management built a reflexive wealth-creation engine known as the "Saylor Loop".
However, recent shifts in their capital structure—specifically an aggressive pivot into $13.5B of high-yielding Perpetual Preferred Stock ($STRC)—have stripped the vehicle of its traditional safety cushions. The company now carries an annualized fixed-income and dividend burden of $1.712B, vastly eclipsing its stagnating software revenue (~$500M annually).
With its market premium compressed to a razor-thin 1.14x, the vehicle has entered a phase of severe structural vulnerability analogous to nuclear "xenon poisoning." The adoption of ASU 2023-08 fair-value accounting amplifies this instability by tying the company's GAAP income statement and balance sheet tax shields directly to the volatile spot price of Bitcoin.
The system is now mathematically primed for a catastrophic, reflexive unwind. The primary trigger is a non-speculative, regulatory catalyst: the finalized MSCI "Non-Operating Company" index exclusion framework scheduled for November 11, 2026. This event threatens to trigger up to $8.8B in forced institutional divestment, breaking the equity printer and setting off a deterministic countdown to a catastrophic solvency event at the September 2027 convertible debt put option wall.
———
🧵1/12 $BTC #BTC $BTCUSD #BTCUSD

55
Based on the Strategic Analysis of $MSTR published by @mathovermyth under the #LiquidityLogic framework, a breakdown where #Bitcoin ($BTC) falls below $75,000 while #MSTR drops below $120 marks the complete inversion of @Saylor’s recursive capital flywheel.
In this specific threshold regime, the corporate structure transitions from an exponential value creator into an unstable, low-power state. The white paper outlines three critical systemic failure modes triggered by these price points:
1. Inversion of the "Saylor Loop" (Premium Compression)
The Premium Death Spiral: The primary mechanism driving MSTR's multi-billion dollar premium over its Net Asset Value (mNAV) is the market's expectation of infinite, accretive token purchases per share.
The Break-Even Threshold: As #BTC dips under $75K—sliding right against MSTR's aggregate historical cost baseline—and the equity drops below $120, the market rapidly begins stripping away this premium.
Asset Parity Repricing: Without the premium, MSTR loses its unique dual-engine capability to issue expensive stock to buy cheap Bitcoin, forcing the enterprise value to contract to match only its raw digital holdings.
2. Fiat Revenue Deficit vs. Debt Service
The Legacy Engine Math: The white paper highlights that MicroStrategy's legacy enterprise software utility generates roughly $500 million in total annual revenue.
The Unfunded Capital Stack: This native cash flow is mathematically incapable of covering the massive debt service required by the company's aggressive, low-coupon convertible notes and capital stack engineering.
Valuation Dependency: Below these key technical levels, the firm cannot rely on At-The-Market (ATM) equity issuance without punishing dilution, creating a structural cash-flow deficit that relies purely on expanding credit markets to roll over liabilities.
3. The Collapse of "Project Paddy's Dollars"
The Reflexive Illusion: The white paper mockingly categorizes the architecture as Project "Paddy's Dollars"—referencing a self-sustaining currency loop that only works as long as external participants keep injecting value into the ecosystem.
Systemic Failure Regime: Once both thresholds breach, reflexivity works in reverse. Lower stock prices stop the accretive buying machine; lack of buying pressure stalls Bitcoin; and a stalling Bitcoin further compresses the stock multiple. The financial reactor effectively running out of kinetic energy, locking shareholders into a vehicle holding highly volatile digital commodities encumbered by heavy senior claims.
LiquidityLogic™ retweeted
Based on the Strategic Analysis of $MSTR published by @mathovermyth under the #LiquidityLogic framework, a breakdown where #Bitcoin ($BTC) falls below $75,000 while #MSTR drops below $120 marks the complete inversion of @Saylor’s recursive capital flywheel.
In this specific threshold regime, the corporate structure transitions from an exponential value creator into an unstable, low-power state. The white paper outlines three critical systemic failure modes triggered by these price points:
1. Inversion of the "Saylor Loop" (Premium Compression)
The Premium Death Spiral: The primary mechanism driving MSTR's multi-billion dollar premium over its Net Asset Value (mNAV) is the market's expectation of infinite, accretive token purchases per share.
The Break-Even Threshold: As #BTC dips under $75K—sliding right against MSTR's aggregate historical cost baseline—and the equity drops below $120, the market rapidly begins stripping away this premium.
Asset Parity Repricing: Without the premium, MSTR loses its unique dual-engine capability to issue expensive stock to buy cheap Bitcoin, forcing the enterprise value to contract to match only its raw digital holdings.
2. Fiat Revenue Deficit vs. Debt Service
The Legacy Engine Math: The white paper highlights that MicroStrategy's legacy enterprise software utility generates roughly $500 million in total annual revenue.
The Unfunded Capital Stack: This native cash flow is mathematically incapable of covering the massive debt service required by the company's aggressive, low-coupon convertible notes and capital stack engineering.
Valuation Dependency: Below these key technical levels, the firm cannot rely on At-The-Market (ATM) equity issuance without punishing dilution, creating a structural cash-flow deficit that relies purely on expanding credit markets to roll over liabilities.
3. The Collapse of "Project Paddy's Dollars"
The Reflexive Illusion: The white paper mockingly categorizes the architecture as Project "Paddy's Dollars"—referencing a self-sustaining currency loop that only works as long as external participants keep injecting value into the ecosystem.
Systemic Failure Regime: Once both thresholds breach, reflexivity works in reverse. Lower stock prices stop the accretive buying machine; lack of buying pressure stalls Bitcoin; and a stalling Bitcoin further compresses the stock multiple. The financial reactor effectively running out of kinetic energy, locking shareholders into a vehicle holding highly volatile digital commodities encumbered by heavy senior claims.
Strategic Analysis of ($MSTR) Strategy’s Financial Reactor
Project "Paddy’s Dollars" — A Comprehensive Synthesis of Capital Stack Engineering, Accounting Reflexivity, and Systemic Failure Modes
1. Executive Summary
Originally an asset-light enterprise software utility, Strategy, Inc. (formerly MicroStrategy) engineered a dual-engine corporate architecture that acts as a hybrid leveraged #Bitcoin holding company and a digital asset central bank.
By exploiting a persistent market-to-net-asset-value (mNAV) premium via continuous At-The-Market (ATM) common equity issuance and low-coupon convertible notes, management built a reflexive wealth-creation engine known as the "Saylor Loop".
However, recent shifts in their capital structure—specifically an aggressive pivot into $13.5B of high-yielding Perpetual Preferred Stock ($STRC)—have stripped the vehicle of its traditional safety cushions. The company now carries an annualized fixed-income and dividend burden of $1.712B, vastly eclipsing its stagnating software revenue (~$500M annually).
With its market premium compressed to a razor-thin 1.14x, the vehicle has entered a phase of severe structural vulnerability analogous to nuclear "xenon poisoning." The adoption of ASU 2023-08 fair-value accounting amplifies this instability by tying the company's GAAP income statement and balance sheet tax shields directly to the volatile spot price of Bitcoin.
The system is now mathematically primed for a catastrophic, reflexive unwind. The primary trigger is a non-speculative, regulatory catalyst: the finalized MSCI "Non-Operating Company" index exclusion framework scheduled for November 11, 2026. This event threatens to trigger up to $8.8B in forced institutional divestment, breaking the equity printer and setting off a deterministic countdown to a catastrophic solvency event at the September 2027 convertible debt put option wall.
———
🧵1/12 $BTC #BTC $BTCUSD #BTCUSD

Strategic Analysis of ($MSTR) Strategy’s Financial Reactor
Project "Paddy’s Dollars" — A Comprehensive Synthesis of Capital Stack Engineering, Accounting Reflexivity, and Systemic Failure Modes
1. Executive Summary
Originally an asset-light enterprise software utility, Strategy, Inc. (formerly MicroStrategy) engineered a dual-engine corporate architecture that acts as a hybrid leveraged #Bitcoin holding company and a digital asset central bank.
By exploiting a persistent market-to-net-asset-value (mNAV) premium via continuous At-The-Market (ATM) common equity issuance and low-coupon convertible notes, management built a reflexive wealth-creation engine known as the "Saylor Loop".
However, recent shifts in their capital structure—specifically an aggressive pivot into $13.5B of high-yielding Perpetual Preferred Stock ($STRC)—have stripped the vehicle of its traditional safety cushions. The company now carries an annualized fixed-income and dividend burden of $1.712B, vastly eclipsing its stagnating software revenue (~$500M annually).
With its market premium compressed to a razor-thin 1.14x, the vehicle has entered a phase of severe structural vulnerability analogous to nuclear "xenon poisoning." The adoption of ASU 2023-08 fair-value accounting amplifies this instability by tying the company's GAAP income statement and balance sheet tax shields directly to the volatile spot price of Bitcoin.
The system is now mathematically primed for a catastrophic, reflexive unwind. The primary trigger is a non-speculative, regulatory catalyst: the finalized MSCI "Non-Operating Company" index exclusion framework scheduled for November 11, 2026. This event threatens to trigger up to $8.8B in forced institutional divestment, breaking the equity printer and setting off a deterministic countdown to a catastrophic solvency event at the September 2027 convertible debt put option wall.
———
🧵1/12 $BTC #BTC $BTCUSD #BTCUSD
₿itcoin’s penultimate “Winthorpe Sweep” is its 2024 Q3 Low of 49,365 for #BTC_F (futures) and approximately 49,050 for #BTC (spot prices can vary slightly from exchange to exchange). #LiquidityLogic founder @mathovermath identified the sequence in DEC 2025. Here’s his chart today and post from FEB.
#Bitcoin $BTC $ETH $XRP


LiquidityLogic™ retweeted

Strategic Analysis of ($MSTR) Strategy’s Financial Reactor
Project "Paddy’s Dollars" — A Comprehensive Synthesis of Capital Stack Engineering, Accounting Reflexivity, and Systemic Failure Modes
1. Executive Summary
Originally an asset-light enterprise software utility, Strategy, Inc. (formerly MicroStrategy) engineered a dual-engine corporate architecture that acts as a hybrid leveraged #Bitcoin holding company and a digital asset central bank.
By exploiting a persistent market-to-net-asset-value (mNAV) premium via continuous At-The-Market (ATM) common equity issuance and low-coupon convertible notes, management built a reflexive wealth-creation engine known as the "Saylor Loop".
However, recent shifts in their capital structure—specifically an aggressive pivot into $13.5B of high-yielding Perpetual Preferred Stock ($STRC)—have stripped the vehicle of its traditional safety cushions. The company now carries an annualized fixed-income and dividend burden of $1.712B, vastly eclipsing its stagnating software revenue (~$500M annually).
With its market premium compressed to a razor-thin 1.14x, the vehicle has entered a phase of severe structural vulnerability analogous to nuclear "xenon poisoning." The adoption of ASU 2023-08 fair-value accounting amplifies this instability by tying the company's GAAP income statement and balance sheet tax shields directly to the volatile spot price of Bitcoin.
The system is now mathematically primed for a catastrophic, reflexive unwind. The primary trigger is a non-speculative, regulatory catalyst: the finalized MSCI "Non-Operating Company" index exclusion framework scheduled for November 11, 2026. This event threatens to trigger up to $8.8B in forced institutional divestment, breaking the equity printer and setting off a deterministic countdown to a catastrophic solvency event at the September 2027 convertible debt put option wall.
———
🧵1/12 $BTC #BTC $BTCUSD #BTCUSD