

Follow for market edge | https://teapawt.net/t.co/gD5jgim7ty Research Analyst: William O'Neil India Private Limited. SEBI Regn. Nos: INH000015543 valid till 18 Mar 2029
Karnataka, India
Joined November 2016
- Tweets11.7K
- Following208
- Followers15.2K
- Likes1K





Pinned Tweet
Our Latest Weekly Report is out — read, reflect, and share your thoughts in the comments.
What’s Inside This Report?
· Market Outlook: Samvat 2083 Opens on a High
· Learning Article: Only 20 of 500: The Nifty Is Flying. Is Your Stock Leading or Lagging?
· Featured Article: The Midcap Crack: Big Companies Grew Profits 36%. Smaller Ones Managed 6%.
· Idea Lists: Five Stocks to Watch Right Now
This report highlights the key themes shaping markets and investment opportunities, with the Market Outlook: Samvat 2083 Opens on a High examining how sustained FII inflows, easing crude oil prices, and broad sectoral strength have supported the Nifty's rally toward eight-month highs, while emphasizing the importance of disciplined stock selection and waiting for healthier entry opportunities. Learning Article: Only 20 of 500: The Nifty Is Flying. Is Your Stock Leading or Lagging? explains how investors can distinguish genuine market leaders from laggards by analyzing Relative Strength Ratings, new highs, and industry group performance, highlighting why a rising index does not necessarily translate into broad-based stock gains. In the Featured Article: The Midcap Crack: Big Companies Grew Profits 36%. Smaller Ones Managed 6%., we analyze the widening earnings divergence between large-cap and mid- and small-cap companies, examining how profitability, operating costs, and company-specific fundamentals are shaping market performance. Finally, Idea Lists: Five Stocks to Watch Right Now features technically resilient companies exhibiting strong relative strength, healthy buyer demand, and promising breakout potential near key pivot levels.
Read the full report here: zurl.co/PLjb5
#MarketSmithIndia #WeeklyReport #ONeilMethodology #StockMarketIndia #Investing #Trading #GrowthStocks #PortfolioStrategy #IndianEquities #SmartInvesting

1
816
Steel went from about Rs 48-50 a kg to Rs 66-67 this year. Action Construction Equipment has raised its list prices about 8%, and says another round is coming.
Q2 FY27 earnings call transcript, filed today.
The cost side
— Steel: about Rs 48-50 a kg, up to Rs 63-64, below Rs 60 in between, now Rs 66-67
— Input costs last quarter: up "above 10%, 11%, 12%"
The price side
— Increases of up to 10% taken; about 8% realised, from mid to late September
— Realised across the first half: "a little over 3%"
— Next round: most likely January; December if steel climbs further in November
— Inventory cushion: about "till December"
The headroom
— Cranes and construction equipment utilisation: about 55% at end-September, "70-75%" now
— Existing plants: room for Rs 5,500-6,000 crore of revenue
— FY27 guide: 18-20% revenue growth, with 55-60% of revenue usually in the second half
The tension: rental operators are about half the market, and the company itself calls repeated increases "very unsettling for the customers".

1
1
642
Foreign investors have put Rs 89,856 crore into Indian equities in sixteen days of November. They are still net sellers for the year.
NSDL's calendar-year table, updated to 16 November:
— January to October: net outflow of about Rs 2.95 lakh crore
— Months of net buying in that stretch: three (February, July, August)
— Largest month out: March, Rs 1,17,775 crore
— November so far: Rs 89,856 crore in, the largest monthly figure in the 2026 table
— 16 November alone: Rs 5,565 crore
— Calendar year to date, even after November: net outflow of Rs 2,05,289 crore
The scale: sixteen days have offset about 30% of ten months of selling.
The tension: this is one strong fortnight inside a year of seven selling months, and a turn looks exactly like a rebound at this stage.
No call on what comes next. NSDL's fortnightly sector report for the first half of November will show where the money went. Save the chart for that comparison.

1
601
Tata Power is adding renewable capacity faster than the grid can take it. Curtailment went from about 8.8% to 11% in one quarter.
Q2 FY27 earnings call transcript, filed today.
The build
— Capex: about Rs 10,000 crore done in the first half, about Rs 25,000 crore planned for the year
— Renewable generation EBITDA: Rs 2,231 crore year to date; management puts the 7.1 GW run-rate at about Rs 4,500 crore a year
— Pumped hydro: Bhivpuri in the first half of 2029; Shirwata, 1,800 MW for Rs 11,871 crore, 75% debt, in 2031
The constraint
— Curtailment: about 8.8% in Q1, about 11% in Q2
— The fix named on the call: connectivity work and battery storage
— Ingot and wafer plant: no order placed yet; China's export controls under review, with clarity due by end-November
The tension: each new megawatt earns only when the grid takes it, and the largest storage asset arrives years after the capacity it is meant to firm up.
Reply: for India's renewable build, which clears curtailment first, transmission or storage?

603
Can a precision engineering company outgrow the wind industry?
Gala Precision delivered 31% revenue growth and 44% order-book growth despite a flat domestic wind market.
Explore its growth drivers, expansion plans, valuation and key risks.
Read the full analysis! medium.com/@socialmedia_9645…
#GalaPrecision #StockMarket #Investing #MarketSmithIndia
🤖 Made with AI

529
Sudarshan Chemical's acquired Heubach business brought in 72% of first-half pigment sales and about half the profit.
Q2 FY27 call transcript, filed 16 November. First half, by business:
— Legacy pigments: revenue Rs 1,551 crore, up 26%; business EBITDA Rs 255 crore, 16.5%
— Acquired Group: revenue Rs 3,935 crore; business EBITDA Rs 240 crore, 6.1%
— A year ago, Acquired Group: Rs 70 crore, 2%
— Net debt: Rs 580 crore at end-September, before the VP4 sale proceeds received in November
The acquisition is improving fast, and its full-year guide of a 5% margin is already beaten. Management kept it unchanged, citing caution in its first normal quarters with the business, the VP4 exit, and weak US housing and European construction.
Tension: RIECO, the engineering arm, posted negative EBITDA of Rs 13 crore in H1 after cost overruns on two late-stage projects.

612
Data Patterns booked Rs 249 crore of revenue in the first half. Its unchanged full-year guide needs about Rs 860–907 crore in the second.
Q2 FY27 results and call transcript, filed 16 November. The guidance arithmetic:
— FY26 revenue from operations: Rs 924.8 crore
— FY27 guide: 20% to 25% growth, or Rs 1,110–1,156 crore
— H1 FY27: Rs 249.3 crore, against Rs 406.8 crore a year ago
— H2 needed: Rs 860–907 crore, against Rs 518 crore in H2 FY26
— EBITDA margin guide: 35% to 40%; H1 was 25.2%
The order side has moved first. Fresh orders were Rs 1,046 crore in H1, Rs 929 crore of it in Q2. Orders on hand are Rs 1,742 crore, with Rs 956 crore more negotiated and awaiting formal receipt.
Tension: management says only a very little portion of the negotiated orders will be executed this year, so the second half rests on orders already in hand.
1
579
Bajaj Finance completed a Rs 11,700 crore share sale overnight. With promoter warrants the raise is Rs 17,500 crore, and management's own maths pointed to about Rs 20,000 crore.
QIP filing, 16 November, read with the Q2 call. The capital arithmetic:
— QIP: 11.41 crore new shares, Rs 11,700 crore
— Promoter warrants: Rs 5,800 crore to Bajaj Finserv; 25% paid on allotment, 75% on conversion
— New shares from the QIP: about 1.8% of the existing base
— Last raise: Rs 10,000 crore, three years ago; the balance sheet has doubled since
The stated purpose is growth. AUM rose 26.5% to Rs 5,84,624 crore, with close to Rs 38,500 crore added in the quarter, and the 23% to 25% growth guide is unchanged.
Tension: leverage is 5.1 times, already near the bottom of a new 5 to 5.5 corridor, so fresh equity weighs on return on equity until growth absorbs it. Selling down the 87% housing-finance stake to 75% stays deferred.
Which is the better source of growth capital for a lender this size: new shares now, or the housing-finance stake?

A portfolio holds decisions made on different dates. Review each one against the evidence available now, not only the story that explained its place at the start.
1
1
576
MarketSmith India's PortfolioSmith evaluates a portfolio against technical and fundamental characteristics. Use the review to organise questions, not to outsource judgment.
1
89
Log what changed and what would change your view. Update the reasoning; do not defend the original story.
Disclaimer: Information contained herein is not and should not be construed as an offer, solicitation, or recommendation to buy or sell securities. It is for educational purposes only.
Legal disclosures: marketsmithindia.com/legalAg…

88
Balu Forge's half-year review came with three auditor notes. One covers a subsidiary that made about 40% of last quarter's revenue.
Q2 FY27 results with limited review reports, filed 14 November. The opinion is unmodified; the "Other Matters" are not small:
The subsidiary
— Safa Otomotiv FZE-LLC was reviewed by another auditor, not the group's
— Its Q2: revenue Rs 129 crore and profit Rs 32.7 crore, against a consolidated Rs 324.3 crore and Rs 76.6 crore
The advances
— Rs 20.2 crore of machinery advances from that wholly owned subsidiary, with realisation beyond the RBI's export timelines
The tax search
— An Income Tax search in Q4 FY26; the block assessment's outcome "cannot presently be determined with reasonable certainty"
The headline numbers (H1 FY27, consolidated)
— Revenue: Rs 625.1 crore, from Rs 523.7 crore
— EBITDA margin: 28.6%
— Operating cash flow: Rs 245 crore, from Rs 35.8 crore
— Order book: Rs 2,400 crore, about half from defence, aerospace and railways
The tension: management guides to 25-30% revenue growth for FY27, which needs the second half to run faster than the first half's 19%, with the fastest-earning unit reviewed by a different auditor.

634
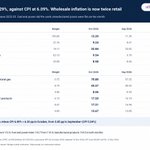
Wholesale inflation hit 12.29% in October, twice the retail rate. Almost all of the month's rise came from fuel and power.
Provisional WPI for October, released today. Year-on-year, against September:
— All commodities: 12.29%, from 11.39%
— Fuel and power: 32.84%, from 25.85% (mineral oils 45.57%; electricity 8.06%, from -0.43%)
— Primary articles: 9.24%, from 8.67%
— Manufactured products: 9.54%, from 9.76%
— Food index: 8.58%, from 8.66%
The wedge: WPI minus CPI (6.09%) is 6.20 points, wider than September's 5.85.
On the month, the all-commodities index rose 0.8 points. Fuel and power, 14% of the basket, supplied about 0.7 of it. The manufactured products index did not move.
The tension: input costs are rising faster than factories are raising prices, and faster than shoppers are paying. One of those gaps closes through margins or through the retail print.
Save the table: the November numbers arrive on 14 December.
🤖 Made with AI

Hindustan Zinc's board approved about Rs 80,000 crore to take metal capacity from 1.1 to 2.0 MTPA. This year's whole capex outlook is Rs 5,000 crore.
Board outcome and investor deck, filed today:
The plan (3 to 5 years)
— Metal capacity: 1.1 MTPA to about 2.0 MTPA (zinc 1.6, lead 0.4)
— Existing plants: about 92% utilised in FY26
— Silver refining: 800 to 1,500 tonnes a year
— Ore capacity: 19.3 to 35.0 MTPA
— Cost: about Rs 80,000 crore, including the Debari smelter approved earlier (now 265 KTPA)
— Funding: "Internal Accruals & Debt"
The cash engine
— H1 FY27 EBITDA: Rs 17,359 crore
— Q2 free cash flow before growth capex: Rs 6,389 crore
— Net cash on 30 September: Rs 11,268 crore
The sizing: spread over five years, the plan needs about Rs 16,000 crore a year; over three, about Rs 26,700 crore. Both are several times this year's spend.
The tension: silver contributed about 45% of first-half profitability, so a zinc-and-lead build is being funded partly by a different metal's price, alongside a dividend the shareholders are used to.
Reply: if silver softens, which gives first, the timetable or the dividend?

1
2
720
Raghav Productivity Enhancers (NSE: RPEL) is emerging as a specialty refractory growth story! 🚀
Revenue up 46% YoY and PAT up 56% in Q2 FY27.
Capacity expansion to 534,000 MTPA and an Odisha JV with TRL Krosaki add growth potential.
Explore its growth drivers, competitive moat and key risks.
Read here in detail : marketsmithin.substack.com/p…
#RPEL #StockMarket #IndianStocks #MarketSmithIndia

705
WABAG's Rs 2,332 crore Yanbu desalination award is gone. The Saudi customer cancelled the tender.
Exchange filing, 14 November:
— Project: 300 MLD seawater desalination plant, Yanbu
— Customer: Saudi Water Authority
— Award: July 2025, about Rs 2,332 crore
— Reason given: "internal reasons attributable to the Customer", notified to all bidders
Against the 30 September order book of Rs 20,207 crore, the award value is about 11.5% of the total and about a quarter of the Rs 8,950 crore international book.
Yanbu headed the company's key-projects list, and was not yet at site.
The company says it is approaching the customer.
The tension: the next order-book disclosure shows whether this is replaced, and how much of the Middle East share is left.

654
Manipal Hospitals grew revenue 37% last quarter. Revenue per occupied bed per day did not move: Rs 70,600.
Q2 FY27 press release, filed 13 November. The reason is Sahyadri, the Pune chain bought in October 2025:
— ARPOB, whole network: Rs 70,600 a day, flat
— ARPOB without Sahyadri: Rs 76,600, up 8.5%
— ARPOB at Sahyadri: Rs 44,100
— EBITDA margin: 26.0%, against 27.5%; 26.8% without Sahyadri
Volumes did the work. Inpatients rose 35% to about 1.69 lakh, outpatients 27% to about 17.4 lakh, occupancy 160 bps to 70.1%.
Profit has three versions:
— Reported: Rs 285 crore, against Rs 318 crore
— Before exceptional items: Rs 380 crore, up 21.6%
— Also before Rs 75 crore of interest on the acquisition debt: Rs 455 crore, up 45.6%
The tension: the acquired beds earn about 58% of the core network's rate, and the debt cost sits between the profit lines.

1
644