

Capital Markets Debt & Equity at Gantry. Commercial loans $2 to $100+ million. Tweets on loans, CRE investment. Dad of 2 girls.
San Francisco, CA
Joined May 2022
- Tweets928
- Following1.2K
- Followers1.7K
- Likes1.5K





A college sophomore emailed then cold called me looking for a summer internship in commercial real estate.
She’d already applied to some national companies. No luck. So she stopped waiting and started dialing.
She knows her superpower, she loves being a connector and meeting new people. I’m impressed that she wasn’t scared to make the call. She’s going for a job in sales and doing the job before she even has it.
I told her to keep going. The right person will say yes.
If a hungry sophomore cold called you about a CRE internship this summer, what would YOU say to her?
We took our 4 and 6 year old to
Disneyland for 3 days. The magic of
Disney is real, I highly recommend it!
The trend continues, big money is coming back (finally)
HSBC Life plans to return to real estate via value add funds.... HSBC is looking at real estate funds again after committing no new capital to the asset class for several years.
Loan Terms:
A+ Grocery Anchored retail center
10+ million loan amount
1.20% spread over US Treasuries
Life Co lender
Yield maintenance and open in final year.
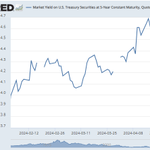
Everyone has a view that interest rates will come down. However, it isn't linear. People who didn't lock 2-3 weeks ago when the 5 year treasury was down to 3.6% are kicking themselves. Their wait may cost them something and playing with fire with their loan maturity or purchase timeline. No one is perfect. It is impossible to time the market but it is often better to take "good" rather than trying to be perfect. Here is the 5 year over the past month:

Industrial 4 Tenant Acquisition in a secondary market.
Purchase price: $8.4 million
NOI: $661,000
Loan: 5.4 million
Term: 5 years
Amortization: 25 years
Spread: 190
Rate Locked at 5.70%
LTV: 64.3%
DSCR 1.63x
Nonrecourse
No Convenats
No Reserves
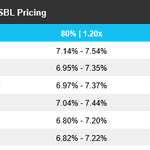
A Fixed Rate Bridge Program I like today for light value add deals:
Property Type: Mostly Apartments and Industrial, selective retail and self-storage, no office.
LTV: Up to 75%
Rate: ~ 6.75% (3 year Treasury + 300-325)
Roughly $10 to 30 million loan sizes
Interest Only Payments
Sized to an 8.5 exit debt yield
Above 1.05x DSCR


Jeff Matlock retweeted
Best opportunity in commercial real estate today?
San Francisco.
A friend/client is finding properties that stabilize to 8.5% Yield on Cost in less than 6 months at market cap rates of 5.5%.
Insurance company lenders are already locking deals forward to January... Some of them have as low as 1.20 spreads.
3 tenant industrial with a tenant rolling in less than a year.
Client: What are the reserves?
How much are they sweeping for TIs?
Me: zero and zero.
Life company loans typically don’t have structure like that. They also only test coverage at closing. There are no DSCR or other covenants. Just make your payment and you are good.
What they gave up:
Leverage went from 70% to 65%
Rate went from 6.5% to 6.0%
Obtained non-recourse
No ongoing covenants
Lender spreads are tightening in commercial real estate.
We were just quoted 125 spread on a
stabilized, very consistent, 50% leverage multi tenant industrial property with I/O.
Loan sizes $5-25 million for this lender.
Sellers and Buyers take note:
CMBS lenders are having a strong comeback in today's lending market however, re-trades seem to be common.
What seems like good negotiation on the front end can sting you. When a broker or a client pushes to get every last basis point out of the initial quote and goes with the very lowest bidder. The winning lender is often making this quote 40 basis points below break-even. Thus, when you get to closing have no time left on your transaction timeline, they re-trade to a profitable/break-even position. This is actually logical if everyone was honest with themselves going into the transaction, but this tactic is becoming far too commonplace and hurts buyers, sellers, and those trying to refinance because they suddenly have a far worse loan than they thought they were signing up for, completely changing the owner's return dynamics.
Solutions? Portfolio lenders are one, or just be honest and transparent going in, there is no such thing as a free lunch and the securitized market can be ruthless, work with people you trust.
“Jeff that sounds too finance bro for me, I’m a dumb real estate guy. I only look at numerator and denominator and Yield on Cost. If we get it above 9 let’s do it. I don’t want the other stuff.”
Said from a guy who is 40 and has built a $100 million net worth buying vacant real estate and filling it over the past 10 years.
How Do You Use AI?
After a month of truly trying different ways from corporate financial analysis, loan package making, email proof reading I even am asking for design ideas on how to redo my back yard. I have mixed results I feel like the quality back is the level of a summer intern that I get frustrated with and spend longer editing the product.
But the new best thing I heard was in brainstorming, negotiation, decision analysis. Prompt it with a book or author and craft 3 ways that (writer) would respond. It doesn’t give you the final answer but it helps you draw on information you read in the past but don’t remember the details.
How do you use AI?
It is amazing how many commercial real estate lending banks have fallen. The state of commercial real estate bank lending remains weak.
Prepandemic list of competitive bank lenders in my area:
First Republic - Gone, acquired by Chase
Silicon Valley Bank - Acquired by First Citizens Bank
Opus Bank -> Pacific Premier Bank -> Merging/acquired by Umpqua Bank
Homestreet Bank - being acquired by Mechanics Bank
Umpqua Bank - Open for business but shut down $1-10 million multi-family lending and SBA division
Pacific Western Bank - Acquired by Banc of California
Luther Burbank - Acquired by WaFd Bank
Bank of the West - Acquired by BMO
Union Bank - Acquired by US Bank
Banner Bank - Eliminated multi-family origination division
First Foundation - Trying to make a comeback
Chase, Wells, Bank of America, CIti, US Bank - Only getting bigger
Not to mention Signature Bank, New York Community Bank, and others that are not active in my area.
It's just interesting. New groups will rise, but what we had from 2015-2022, with very low rates and transactional bank lending, is mostly gone.
Best opportunity in commercial real estate today?
San Francisco.
A friend/client is finding properties that stabilize to 8.5% Yield on Cost in less than 6 months at market cap rates of 5.5%.
Thoughts and prayers to all of those investors who 1031 exchanged into low cap rate Dollar Generals in small markets with super low rate debt coming due in the next couple of years and store closures across the country.
Oh my, how the world has changed.
Client told me today that he built his house for $75 per foot in Atherton in the late 80s and they are now buying them for $8 million to tear them down and rebuild at $1,000 per foot.
It’s wild how much wealth there is out there.
After attending the MBA CREF conference in San Diego and meeting with 33 lenders, a few clear themes emerged regarding the state of the commercial mortgage market. Here are my main takeaways.
𝟭) 𝗡𝗼 𝗠𝗼𝗿𝗲 𝗘𝘅𝘁𝗲𝗻𝘀𝗶𝗼𝗻𝘀 – “𝗘𝘅𝘁𝗲𝗻𝗱 & 𝗣𝗿𝗲𝘁𝗲𝗻𝗱” 𝗶𝘀 𝗢𝘃𝗲𝗿
The number one thing I heard again and again: loans that were granted extensions will be forced to refinance elsewhere or sell this year; no more extensions will be granted. This will end the extend and pretend that has become common over the past 12 to 24 months. Many of these deals didn’t hit their projected numbers but have some equity remaining.
𝟮) 𝗟𝗲𝗻𝗱𝗲𝗿 𝗔𝗹𝗹𝗼𝗰𝗮𝘁𝗶𝗼𝗻𝘀 𝗕𝗮𝗰𝗸 𝘁𝗼 𝗡𝗼𝗿𝗺𝗮𝗹
Almost every lender expanded allocations and expectations in 2025, they roughly back to a normal level after all-time highs in 2021 and 2022 then down years in 2023 and 2024. Heard from one lender, “it is fun to be back in the market again”.
𝟯) 𝗦𝗽𝗿𝗲𝗮𝗱𝘀 𝗮𝗿𝗲 𝗖𝗼𝗺𝗽𝗿𝗲𝘀𝘀𝗶𝗻𝗴
Spreads are compressing, lenders notice the increased competition in the past few months and have to be competitive to win.
𝟰) 𝗢𝗳𝗳𝗶𝗰𝗲 𝗟𝗲𝗻𝗱𝗶𝗻𝗴 𝗶𝘀 𝗠𝗮𝗸𝗶𝗻𝗴 𝗮 𝗖𝗼𝗺𝗲𝗯𝗮𝗰𝗸 - 𝗦𝗲𝗹𝗲𝗰𝘁𝗶𝘃𝗲𝗹𝘆
Many more lenders, even life company lenders are willing to lend on quality office buildings again after being a hard NO for the past 2 years. It is still the least preferred property type and lenders want to obtain some additional yield.
𝟱) 𝗥𝗶𝘀𝗶𝗻𝗴 𝗗𝗲𝗺𝗮𝗻𝗱 𝗳𝗼𝗿 𝗙𝗹𝗼𝗮𝘁𝗶𝗻𝗴 𝗥𝗮𝘁𝗲 𝗗𝗲𝗯𝘁
There has been higher demand for shorter 5-year fixed rate loans for a few years now with everyone expecting rates to be lower in the future. Demand is rising for floating rate debt as it is pricing closer to perm debt with light prepay structures.
𝗟𝗲𝗻𝗱𝗶𝗻𝗴 𝗠𝗮𝗿𝗸𝗲𝘁 𝗥𝘂𝗻𝗱𝗼𝘄𝗻
𝗜𝗻𝘀𝘂𝗿𝗮𝗻𝗰𝗲 𝗖𝗼𝗺𝗽𝗮𝗻𝗶𝗲𝘀: Continue to win an outsized share of the market with lower rates and abundant capital.
𝗔𝗴𝗲𝗻𝗰𝘆: Eager and active, continues to price affordable deals extremely competitively.
𝗕𝗮𝗻𝗸𝘀: Still have higher rates; many have decreased deposit requirements down from 15-20% a year ago to 5-10% and are starting to lend again.
𝗗𝗲𝗯𝘁 𝗙𝘂𝗻𝗱𝘀: Have capital and are raising more, they are increasingly an alternative to banks with lower short term index rates, for higher leverage, value add business plans and those that just need 1-3 more years before selling or to complete their business plan. Many are comfortable with bridge-to-bridge lending, which has been challenging in the past.
R𝗲𝗰𝗮𝗽: The commercial mortgage market has stabilized after the volatility of the past four years. Following the low rates and high volumes of 2021-2022 and the high rates and low volumes of 2023-2024, 2025 is shaping up to be a more balanced and moderate year.