

Building a hiring platform for finding Salesforce Freelancers (https://teapawt.net/t.co/OdbddOHaOS)
NYC
Joined October 2012
- Tweets938
- Following678
- Followers9.4K
- Likes622




Pinned Tweet
LinkedIn will slowly unravel as each category gets carved into niches, rather than a single player taking the market:
Networking >> Communities
• @joinrevgenius, @IndieHackers
Job boards >> Niche aggregators
• @Pallet_HQ, @StartupJobs, @RemoteOK
1/2

The message from Salesforce on their earnings call this week is concerning if I’m a customer.
• Cut spend in R&D, Sales, and Marketing by $800m last year.
• Plan to spend $10 BILLION on a share buyback...
Investors have been pressuring Salesforce to focus on profitability recently.
They disbanded their Mergers & Acquisitions team as a result.
Many people were excited by that announcement.
“Salesforce needs to focus on improving the current Product suite!”
Fair.
Well, they spent $150m LESS on R&D last year than in the prior year.
No Acquisitions & No Innovation?
Meanwhile, Hubspot increased their investment in R&D by 40% last year.
(Even the sleepy ORACLE is increasing their spend on R&D.)
Salesforce also cut spend on Sales & Marketing last year.
Hubspot increased 20%.
I wasn’t overly concerned when Salesforce slowed in their M&A activity. They needed to appease investors and show profitability.
But cutting that type of spend is only part of the equation.
This earnings announcement shows they are planning to spend.
A LOT.
Just not in areas that benefits customers.
They are spending in ways that benefit investors.
• $10B share buyback program.
• Announcement of their first stock dividend.
This is cash that could be spent elsewhere.
👉 Investing back in R&D.
👉 Building a cash reserves to make moves in AI.
And they’re going to need it.
4 companies are positioned to dominate in AI.
Microsoft, Amazon, Nvidia, Google.
In 2023, they invested a combined $23B in AI Startups.
That was a stunning 30% of all venture deals around Data & AI.
I understand Benioff highlighted a bunch of positives on the call too.
• References to an increase in multi-Cloud deals
• Data on an increase in deals with $10m+ ACV
• Heavy talk around Einstein and AI
This is Marketing speak, though.
You simple CANNOT:
• Spend less on Research & Development
• Spend less on Sales & Marketing
• And stop pursuing the aggressive acquisition strategy that got you here
Don’t get me wrong, I’m rooting for Salesforce as much as anyone.
I run @found_hq, which does nothing but help companies hire Salesforce Freelancers.
But is this the best use of $10,000,000,000?
When people see the growth at a company like ServiceNow, they often forget what’s behind this type of go-to-market machine.
They have one of the biggest Rev Ops teams I’ve ever seen - 500+ people globally - dedicated to the science of Sales.
ServiceNow CEO said this growth is largely thanks to GenAI capabilities.
“The SKU outsold any other new introductions put into the marketplace.”
While the Product & Eng. teams are to thank for feature releases …
You can’t bring new products to market without a strategic backbone.
👉 Pricing Strategy
Macro Level Insights
• 17 people dedicated to it
👉 Deal Desk
Micro/Account Level Deal Strategy
• 65 people dedicated to it
👉 Partner & Channel Operations Strategy
Unlocking Network Effects
• 42 people dedicated to it
👉 Customer Outcomes
Translating measurable success to Sales & Pricing Strategy
• 7 people dedicated to it
At ServiceNow, they have entire teams focused on :
–– Market Segmentation & Analysis
(Led by a Director of GTM Customer Segmentation)
–– GTM Sales Analytics
(Led by a VP of GTM Analytics)
–– Regional Specific Pricing Strategy
–– Industry Specific Sales Enablement
–– GTM Product Analytics
–– Customer Outcomes
–– Field Operations
–– Support Operations
–– Sales Enablement
–– GTM Systems
Sure, most companies don't need a Rev Ops this size.
But there is a TON to gain from analyzing sophisticated orgs.
It uncovers areas that you aren’t currently focused on.

In November 2022, Bret Taylor stepped down as Salesforce Co-CEO.
Then, he joined the Board at OpenAI + Shopify, founded a $1B AI startup.
This may go down as the biggest loss Salesforce has ever seen.
Bret Taylor has become absolutely unstoppable.
A Quick Timeline of Events:
2016: Salesforce acquires Taylor's company, Quip, for $750m
2016: Taylor joins Twitter Board of Directors
2017: Taylor named Chief Product Officer at Salesforce
2019: Quip is re-launched as Salesforce Anywhere.
👉 This appeared to be Salesforce's answer to Microsoft Teams. (It was not.)
December 2020: Salesforce Acquires Slack.
• A massive bet in Salesforce's battle with Microsoft.
• Taylor was the chief architect behind this acquisition.
November 2021: Taylor named Co-CEO of Salesforce.
November 2022: Taylor leaves Salesforce.
Now, this is where things get interesting ...
March 2023: Taylor founds new AI Startup, Sierra.
June 2023: Sierra raises $20m, valued at $100m (after 3 months)
June 2023: Taylor joins Shopify Board of Directors
November 2023: Taylor becomes Chairman of the Board at OpenAI
January 2024: Sierra raises $85m, valued at $1B
WHOA 🤯
When Taylor left Salesforce, it was to "get back to his entrepreneurial roots".
I was skeptical.
A contributing factor seemed to be misalignment about Salesforce's future.
And while I don't know for sure, the ultimate question is:
What would Salesforce look like today with Bret Taylor as the lone CEO?
2
225
The future of Upwork and Fiverr will follow the same trajectory as Craig’s List.
It was ‘unbundled’ into niche, vertical specific marketplaces.
Freelancer’s Marketplaces were one of those offshoot categories. I believe the future of that space will be niched down versions - a Salesforce Freelancers Marketplace, for example.
You can’t accumulate a high enough concentration of high-skilled talent to serve every market as a generalist Marketplace attempting to do it all.

Fiver exists, but someone should make 'Grander' - a site where you can pay $1,000 or more for anyone to do a high-value task.
Where's the button you can press on the internet for a smart person to do a task for you in the next 24 hours?
Like a white collar Task Rabbit
2
252
Salesforce is killing a huge opportunity with a pricing mistake.
As more companies lean into Community-Led GTM motions, Salesforce is making it impossible to build Communities in Slack.
Slack charges per user regardless of use case.
A Slack Community like @relume_io (with 2,139 members) costs $139,569 per year.
The decision is sending Communities to Discord and other competitors.
This is an overlooked opportunity and fatal mistake.
In my opinion, this would be a simple marriage btwn Salesforce <> Slack.
It’s beneficial in a few ways:
1. Drives organic, bottom-up Slack adoption
2. NEW USE CASE provides insights to inform on new features/products
3. Communities play a big role in the Sales motion (Slack >> Sales & Marketing Clouds)
4. Access to vast conversational data for AI
Point 3 is likely the most important of all.
The way companies Go-to-Market is changing.
And Salesforce needs to be listening to the market.
It’s not just inbound (Marketing) vs. outbound (Sales) motions.
The new normal includes Community-led and Partner-led motions.
For years, Salesforce wanted to go after a social platform.
First, LinkedIn. Then, Twitter.
Slack provides the same opportunity.
TENS OF THOUSANDS of Communities could exist in Slack.
Each Community has a very specific topic and persona.
Layering conversational insights on top of pre-defined personas is gold.
Salesforce would benefit greatly from:
👉 Greater Product Innovation
👉 A Wedge into SMB
Slack gives them the opportunity for both.
But it doesn’t seem like they’re going to capture it.
—
#CRM #Salesforce #Slack #Communities

Hey @SlackHQ can we please introduce a ‘Community Plan’. I don’t think we can afford $140k for the @relume_io Slack Community.
Or do I just make the switch to @discord?

1
3
376
The Executive brain drain happening at Salesforce is very real.
At the end of Q4’23, they lost Slack CEO (now CEO of Bumble) and Salesforce CMO (now CEO at Lattice).
Something to watch 👀
1
172
2024 Prediction:
Salesforce will start acquiring again.
After 2 acquisitions in 2023 (@AirkitAI, @Spiff_Inc)…
Expect to see 5+ in 2024 👇
Investors loved Salesforce’s earnings throughout 2023.
The stock was up 91% last year.
Salesforce focused on profitability above all else.
• Investment in R&D was down YOY
• Investment in Sales & Marketing was down YOY
• Subsidized Professional Services was down YOY
But this won’t continue forever.
Otherwise, Salesforce quickly becomes ‘the new Oracle’.
A cash cow that doesn’t innovate.
And that will be the beginning of the end for them.
I believe they will continue innovating to remain dominant.
That needs to happen through acquisitions.
I always say it’s worth paying attention to Salesforce Ventures’ investments.
In 2023, Salesforce made 2 strategic acquisitions:
1. Airkit (Sept. 2023)
👉 Goal: Boost AI Competency
2. Spiff (Dec. 2023)
👉 Goal: Bolt-on for Sales Cloud , easy upsell to drive bottom line growth
Both of these were SFVC portfolio companies.
• SFVC invested in the Airkit Series A + B Rounds.
• SFVC invested in the Spiff Seres B + C Rounds.
Corporate Venture Arms are how market leaders keep tabs on innovation.
Acquisitions are how they bring that innovation into the fold.
This is a good thing.
Salesforce knows competition is heating up in the space.
We should expect them to stay in front of it.
1
180
In Oct 2020, Salesforce invested in @AirkitAI’s Series A.
In March 2021, Salesforce invested in Airkit’s Series B.
In September 2023, Salesforce acquired Airkit.
Corporate Venture arms should be how market leading incumbents stay on top of innovation and make moves to rapidly integrate it in their offering.
#AI #CRM #Salesforce
1
206
As many have been suggesting, Salesforce ($CRM) may quickly become the new Oracle.
Yesterday’s earnings show growth continues to slow (projecting 10% YOY) as the focus remains on profitability.
And the stock is up 8% today.
This would suggest it’s a decent stock to hold but not necessarily where I would place my focus as someone looking to develop a career in Technology…
Salesforce needs to make a move in AI.
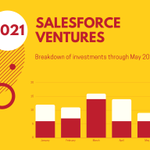
In 2023, @SalesforceVC invested in 13 AI Startups 👇
Prediction: Next year, they will acquire 1.
In September 2023, Salesforce acquired @AirkitAI.
It’s run by the Founders of RelateIQ, which Salesforce acquired in 2014.
Airkit is a low-code platform for organizations to build and deploy AI Agents for Commerce.
It’s a good start but won’t be enough to take on Microsoft.
Salesforce needs to develop an AI competency at the INFRASTRUCTURE level.
And I believe the only way to do it will be through acquisition.
These are the 13 AI Startups Salesforce Ventures invested in this year:
Jan 2023
1. @Faros_AI
$20m (Series A)
Total Funding: $36M
Connect the dots between Engineering data sources – ticketing, source control, CI/CD, and more.
Feb 2023
2. @FingerprintApp
$6.5m (Series A/Seed)
Total Funding: $9.2m
Develops personal development and AI coaching solutions.
March 2023
3. Hearth AI
Seed (undisclosed amount)
An AI platform designed to deliver semantic network searches.
May 2023
4. @cohere
$270m (Series C)
Total Funding: $435m
Provides access to advanced Large Language Models and NLP tools through one easy-to-use API.
5. @simpplr
$70m (Series D)
Total Funding: $131m
AI-powered employee experience platform.
6. @AnthropicAI
$450M (Series C)
Total funding $3.3B
AI research company and direct competitor to OpenAI.
Jun 2023
7. @Tribble_ai
Pre-Seed (Undisclosed Amount)
Autonomous agents that integrate with your systems, learn from your data, and take action in the tools you use.
8. @runwayml
$141m (Series C)
Total Funding: $236.5m
An applied AI research company that builds the next generation of creativity tools.
9. @typefaceai
$100m (Series B Lead)
Total Funding: $165m
Generative AI application that provides streamlined and personalized content creation for enterprises.
Jul 2023
10. @Pano_AI
$17m (Series A)
Total Funding: $45m
Deep learning AI and computer vision to automatically detect, verify and classify wildfire events in real time.
11. @SylveraCarbon
$55m (Series B) (Previously led Series A in 2022)
Total Funding: $95.3m
Machine learning-based tools to track the performance of carbon offsets.
12. Protect AI
$35m (Series A)
Total Funding: $48.5m
Cybersecurity platform specialized in protecting machine learning models and artificial intelligence systems.
Aug 2023
13. @huggingface
$235m (Series D Lead)
Total Funding: $395m
Open-source AI platform to build, train, and deploy art models.
What are the main reasons major SaaS vendors have Venture Capital arms?
Salesforce. Workday. Hubspot. ServiceNow. SAP.
275
If Microsoft becomes the de facto place for AI courses, upskilling, and training … it’s game over.
This was a huge part of Salesforce’s winning strategy as they cultivated a supply of talent and a community that evangelized their platform unlike anything we’ve seen in Enterprise SaaS.

Microsoft has released free courses on AI.
No payment is required!
Here are 6 FREE Microsoft courses to master AI in 2023 👇

1
387
Microsoft will now overtake Salesforce in the next 5 years.
1. They are about to hire most of the team at OpenAI
2. Dynamics revenue hit $5.4B - faster growth than SF
3. Microsoft is an ERP market leader, SF doesn’t touch it
4. Salesforce market cap ($218B) is 8% of MS ($2.7T)
5. Power BI has more market share than Tableau
6. Teams has ~300m users, Slack continues to struggle
7. Salesforce is under pressure to push to profitability
8. Salesforce relies on Azure and AWS for data centers
9. Salesforce is under attack in SMB from Hubspot
10. Salesforce isn’t shipping, acquired a low-code AI platform in Sept.
11. Outreach CEO noted a spike in Dynamics integrations over the last year
None of this is to say Salesforce doesn’t perform in other areas.
• Their ecosystem of 3rd Party Developers is massive
• The ability to build custom apps on Force[.] is second to none
• They continue push to industry-specific solutions
• Mulesoft is growing 26% YOY, AI will lift demand.
But these subtle (and not-so-subtle) trends could spell trouble.
For years, Salesforce was eating market share from legacy incumbents (SAP, Oracle).
It seemed their greatest threat would come from an upstart (Hubspot).
Microsoft has long been in the CRM mix but never made it a focus.
If that changes, it’s an unimaginably formidable competitor for Salesforce.
And if AI truly is the future, I don’t see how they keep pace.
2
467
And another C-level Exec is out at Salesforce.
Longtime Tableau Product Leader turned Chief Customer Officer departs.

It’s been the ride of a lifetime and I'm ready to take on my next big challenge. I've loved every moment of my 13 years at #Tableau and Salesforce. I’m glad that I got to play a part in this incredible community, and building this product. I am filled with gratitude. Thank you.

174
Genuinely curious what the hardest part - operationally - would be at a company like @deel.
Founded in 2019.
$4m ARR in 2020.
$50M ARR in 2021.
$400m ARR in 2023.
1
1
448
In 2016, a Salesforce Board Member’s e-mail was hacked.
It revealed 14 companies Salesforce was thinking of acquiring.
2 of those actually happened.
Which of these would have been the best acquisition for them 👇
The list of targets included 2 companies Salesforce went on to acquire:
✅ Demandware (2016, $2.8B)
✅ Tableau (2019, $15.7B)
12 Other Acquisition Targets:
• Adobe
• LinkedIn (Acquired by Microsoft in 2106, $26.2B)
• Workday
• ServiceNow
• Netsuite (Acquired by Oracle in 2016, $9.3B)
• Pegasystems
• Qlik (Acquired by PE in 2016, $3B)
• Veeva Systems
• Box
• Zendesk
• Marketo (Acquired by PE† in 2016 , $1.79B)
†Sold to Adobe in 2018, $4.75B
• Hubspot
The company Salesforce really wanted at the time:
❌ LinkedIn
In the years the followed, Salesforce indeed made some big acquisitions:
• Demandware (2016, $2.8B)
• Quip (2016, $750m)
• Krux (2016, $800m)
• Mulesoft† (2018, $6.5B)
• Datorama (2018, $800m)
• Tableau† (2019, $15.7B)
• ClickSoftware (2019, $1.4B)
• Vlocity ($2020, $1.3B)
• Slack (2020, $27.7B)
†Combined to generate $4.3B in FY23
You can’t help but wonder …
Would any of the 2016 acquisition targets been more impactful to Salesforce?
115
Slack's new CEO, Denise Dresser, comes from a background in Sales.
This is undoubtedly the right move for Salesforce.
Historically, Salesforce has elevated Product Leaders into top roles.
But the challenges ahead for Slack focus heavily around Go-to-Market alignment, figuring out how to succeed with a product that pioneered Product-Led growth and now exists as an upsell in the product arsenal of one of the largest Sales-Led cultures in history.
2
215
Klaviyo is on pace for revenue of $700m.
And ACV of just $5K.
But Customers generating $50K+ ARR jumped 89%.
All because of their investment in Rev Ops.
Insights on this powerhouse Rev Ops team👇
This is a company doing $700m in annual revenue.
A modest Sales org of ~575 Reps for this scale.
And ACV of just $5K.
But pricing is partially usage-based, so it’s a land and expand strategy.
A heavy emphasis on GTM Analytics is required to succeed in this model.
And we see it in their data-oriented Revenue Operations function.
You don’t often see a Rev Ops team of 40+ for only 575 Sellers.
(Plus, they have $1.3m+ earmarked for 7 open Rev Ops positions.)
A few roles that jumped out:
• Principal Data Scientist, GTM Programs (Open Role)
• Manager, Revenue Retention Analytics (Open Role)
• VP, Platform Expansion
• Director, Voice of the Customer
• (2x) Manager, Voice of the Customer
Nothing demonstrates the value of Rev Ops more than this function:
👉 Voice of the Customer
All 3 of these individuals come from a BI / Data Analytics background.
The function sits at the intersection of GTM and R&D.
By definition, it keeps the entire organization in alignment.
They collect and synthesize data to inform on GTM and Product strategy.
• (Quantitative Insights) Surveys & Primary Research
• (Quantitative) Analysis of Operational data
• (Qualitative) Pair it with customer-facing insights from Sales, Success, Support, Onboarding to identify, size & prioritize emerging opportunities.
• Own the CX measurement strategy for New Products
Layer that approach under strong Rev Ops Leadership:
• SVP, GTM Strategy & Ops
• VP, Revenue Ops & Field Enablement
• VP, Platform Expansion
• Head of Strategy & Operations (Support)
• VP, GTM Strategy & Programs
• Director, Sales Strategy and Planning
• Sr. Director, Sales Operations
• Sr. Director, GTM Enablement
And continue investing big to fill out the team.
$1.3m+ earmarked for 7 open Rev Ops positions.
Including:
• Partner Systems Manager (Salesforce)
• Sr. Manager, Sales Ops (EMEA)
• Principal Data Scientist (GTM Programs)
• Sr. Director, GTM Incentive Strategy
• Manager, Ops & Analytics (CX)
• Manager, Revenue Retention Analytics
What do you think of the team in place at Klaviyo?
In 2021, Udemy’s core (B2C) revenue stream peaked: $331m (+1% YOY)
A look at Udemy’s incredible pivot to B2B and why Enterprise SaaS lives and dies by how you invest in Rev Ops 👇
In 2021, total revenue at Udemy was $518m.
• B2C Revenue: $331m (+1% YOY)
• B2B Revenue: $187m (+81% YOY)
Imagine having to replace a $300m per year revenue stream.
Especially, when that is the MAJORITY of your business.
Udemy’s ability to take a Consumer Services offering, re-package it, price it, and distribute to an Enterprise B2B Segment is unreal.
The pivot from B2C to B2B started long before 2021.
But the last 2 years have shown us that it was a success.
Udemy in Q3 2023:
• B2C Revenue has continued to slide - on pace for $315m.
• Meanwhile, the B2B Segment is on pace for $406m.
• In 2 YEARS, B2B went from 36% of total revenue in 57%.
And it’s far from a massive Rev Ops team powering $400m per year:
• VP GTM Strategy & Operations
• Sr. Director, Sales Strategy & Operations
• Sr. Manager, GTM Strategy (EMEA)
• Sr. Manager, Sales Ops (APAC)
• (4x) Manager, Sales Ops
• (3x) Sr. Sales Ops Analyst
• Program Manager, GTM Strategy
Plus, virtually all of the GTM Systems team was built in the last 2 years.
A Salesforce team of 17 with a strong Product Manager layer.
Udemy’s structure shows they know how to bridge Business & Tech teams.
Invest in Rev Ops early and often.
It will accelerate growth.
Or prevent failure.