

Markets aren't always rational. Asking why is where curiosity meets opportunity.
Sarasota, FL
Joined April 2014
- Tweets1.4K
- Following120
- Followers8.7K
- Likes6





Pinned Tweet
How much of a “diversified” index is really just a handful of names?
Passive used to feel neutral. Concentration complicates that.
On Oct. 27, Bill Miller IV and Dan Lysik are LIVE on what that means for risk, opportunity + portfolio construction.
Register: events.zoom.us/ev/Albg0Trvol…
#investing

AI leaders command extraordinary valuations. Some perceived AI casualties trade at just 2x earnings.
The gap between market expectations and business fundamentals is widening.
Bill Miller IV and Dan Lysik will explore both sides of the AI trade on MVP LIVE. LIVEstreaming here at 4:15pm ET.

The 30 largest U.S. stocks now represent 50% of total market capitalization. Meanwhile, 83% of S&P 500 constituents finished Q3 at least 10% below their 52-week highs.
Is that a signal the opportunity set exists beyond the largest stocks?
Join us for MVP LIVE tomorrow, Oct 27 at 4:15pm ET: events.zoom.us/ev/Albg0Trvol…

The combined market capitalization of the five largest S&P 500 companies is approximately six times that of the entire Russell 2000.
And Small-cap equities experienced one of their weakest rolling 10-year periods of relative performance in the past century.
The resulting valuation disparities reflect prolonged underperformance and depressed expectations across significant portions of the small-cap universe.
Dan Lysik explores in his latest letter: millervalue.com/taking-advan…

Investing is all about probabilities, and just because there appears to be a strong consensus prices are going to keep going up, doesn’t mean that is wrong, or right. The consensus does tend to be wrong at the turning points, being invariably bullish at the top and bearish at the bottom. - Bill Miller Q1 2006 Investor letter
AI leaders among the 30 largest U.S. companies trade at an average of more than 15x sales. At the same time, companies perceived as vulnerable to AI disruption have experienced significant multiple compression.
We believe the market is differentiating too broadly between potential AI beneficiaries and businesses facing disruption. The economic effects of AI adoption will vary considerably across companies, including those capable of using the technology to improve productivity and margins
The 10-year Treasury yield rose from 4.47% to 5.28% in Q3, raising concerns about equity returns.
Yet higher yields improve prospective bond returns, while lower equity valuations can improve prospective stock returns.
Bill Miller IV examines both in his recent letter: millervalue.com/higher-rates…

The 30 largest U.S. stocks now represent 50% of total U.S. market capitalization, a record level of concentration. And this group trades near 7x sales, approximately 40% above the valuation peaks reached in 2000 and 2021.
10 of the 11 largest companies are AI leaders, reflecting the degree to which capital and investor expectations have converged around a relatively narrow group of businesses.
At these valuations, prospective returns are increasingly dependent on the ability of market leaders to sustain elevated growth and profitability expectations.
The S&P 500 gained 2.30% in Q3. Four stocks—AAPL, MSFT, NVDA and META—contributed 4.23 percentage points. The remaining 496 collectively detracted 1.92 points.
By QE, 83% of the S&P 500 was at least 10% below their 52-week highs, and more than 200 were down at least 20%.
The divergence between index-level performance and underlying market breadth reflects an increasingly narrow group of companies driving returns, while weakness persists across much of the broader market.

No 2027 S&P target. No 45-minute slide deck. No canned market outlook.
Instead:
→ Index Concentration
→ Value + small caps
→ Rates
→ Leverage
→ Stock picking
→ Your questions
Bill Miller IV + Dan Lysik LIVE.
Oct. 27 | 4:15 PM ET
Register → events.zoom.us/ev/Albg0Trvol…
#investing
“Count me somewhere between bullish and very bullish.” — Bill Miller, Q3 2006
Across 30+ years of managing money, Bill's view was grounded in a simple observation: markets have historically risen over time.
Congratulations to Bill on being named to the Forbes Optimism 250!
#Forbes250 @B3_MillerValue

Where are you struggling to get conviction?
Dan Lysik and Bill Miller IV are taking questions LIVE Oct. 27.
What should we talk about?
Register → events.zoom.us/ev/Albg0Trvol…


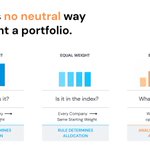
Index weights reflect market capitalization, not an independent assessment of value.
Our bottom-up process begins with the business: its fundamentals, future prospects, and expectations embedded in its stock price.
Opportunity emerges when price and our assessment of value materially diverge.
#investing
In 2006, Bill Miller described investing as an effort to "narrow the cone of uncertainty" as time horizons extend.
The objective is not to eliminate uncertainty, but to identify where an independent assessment of future outcomes differs materially from expectations embedded in market prices.
A company's fundamentals can improve without a corresponding increase in its stock price. Conversely, shares can appreciate without meaningful fundamental improvement.
Market prices reflect expectations of future performance, not simply current results. Those expectations can diverge from reality.
When future outcomes cannot be reliably calculated, investment decisions depend partly on convention, confidence, and prevailing market beliefs.
Keynes recognized that investors look to one another to form expectations.
Those behaviors influence market prices.
"No one has privileged access to the future, a future which involves what Keynes called irreducible uncertainty." — Bill Miller, March 2022
Keynes distinguished uncertainty from measurable risk. Some unknowns can't be resolved with better data or models. The future is genuinely unknowable.
Goldman Sachs CEO David Solomon recently cited "complexity and uncertainty in the world."
We looked back through decades of Bill Miller's letters and found nearly 500 passages discussing uncertainty, fear, complexity, etc.
Uncertainty isn't a new market condition. It's a persistent one.
Market leadership is broadening beyond mega-cap growth. Through 9/30, Russell Value beat Growth by ~1,200 bps on average across market caps. Cap-weighted and equal-weighted indexes allocate by rules, not valuations.
Broader leadership creates more room for individual stock selection.

We don't underwrite baskets. We underwrite businesses.
What does it earn? What is it worth? What expectations are already in the price? Where might the market be wrong?
And how much should we own given the opportunity + risk?
That's bottom-up investing.
#investing