

The adventure begins! 🚢 We are thrilled to officially launch Ourios Analytics (https://teapawt.net/t.co/KQSmRqTE7i). Financial models for Shipping Investors.
USA
Joined October 2026
- Tweets86
- Following249
- Followers237
- Likes713


Pinned Tweet
Investing in shipping without the right tools means spending dozens of hours buried in spreadsheets, manual NAV calculations, and fragmented data. Or, worse yet, investing blindly without testing scenarios.
Stop wasting time trying to build and update complex financial models from scratch. With Ourios Analytics, you have a Master Dashboard to see all valuations at a single glance, and individual company models to test any scenario you want. All inclusive!!!
Why is this a game-changer for your portfolio?
- Massive Time Savings: Eliminate hours of manual grunt work. All the heavy lifting is already done for you.
- Dynamic Updates: The models update automatically as market news, rates, and corporate actions evolve, keeping your data fresh.
- Total Customization: Best of all, you can easily adapt the individual models and easily run your own assumptions, see the exact metrics each company would hit, and stay one step ahead.
Making your investment decisions based on objective, modeled data isn't just practical and fun—it’s the ultimate edge. By anticipating market shifts and stress-testing your ideas, it can help you make money or save you from losing it.
Ready to upgrade your process? Get our models now at ouriosanalytics.com — special launch offer available.
#shipping #tankers #drybulk #Investing

4
512

Gibson Tanker Market Report
11.20.2026
Cracks are showing
#tankers
gibsons.co.uk/report/cracks-…

1
64
Star Bulk ($SBLK) updated financial model is already available.
You can download the Excel model and play around with it, adjusting your own assumptions to build your own scenarios and valuations whenever you want.
Your assumptions. Your valuation. Your investment decisions.
ouriosanalytics.com

Frontline (NYSE: $FRO) – Q3 2026 Results
Another very strong set of numbers from Frontline, with an increasingly attractive outlook heading into Q4.
A few highlights from our updated model:
FY 2026 Adjusted EPS: $13.90
NTM Adjusted EPS: $15.58
NTM Adjusted EBITDA: $3.9bn
NTM Levered FCF: $3.48bn
NTM Adjusted P/E: just 2.87x
NTM EV/Adjusted EBITDA: 3.22x
NTM Dividend Yield: 37.36%
In addition, Frontline is expected to take delivery of its final three VLCCs in Q4, completing the January 2026 order. These vessels are arriving at an exceptionally favourable point in the tanker cycle, with VLCC rates at very attractive levels. Frontline should be in an excellent position to capitalize on this additional capacity.
And the Q4 rate guidance is particularly encouraging, reinforcing the strong earnings potential ahead.
A fully updated financial model is available at ouriosanalytics.com; most importantly, you can easily input your own assumptions
#Tankers

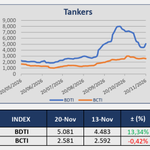
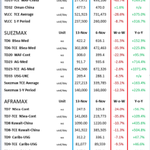
Looking at the WoW figures (red column), it's easy to get nervous about the recent correction in tanker rates.
But take a closer look at the actual earnings levels (blue column).
Even after the pullback, these are extraordinary TCE levels. The spot market is still generating remarkable cash flows across all three segments.
A correction in rates? Absolutely. A weak tanker market? Not even close
Got #tankers
Source: Banchero

United Maritime ($USEA), Seanergy Maritime's spin-off, has just released its Q3/26 results, and there is some very interesting news for shareholders!
The company has DOUBLED its quarterly dividend to $0.20/share.
If maintained at this level, this would translate into an annualized dividend yield of approximately 26% at current share prices. Quite remarkable!
Even more interesting is its strategic repositioning towards Capesize vessels. Its two operating Capesizes are already fixed for 2027 at rates exceeding $35,000/day and $29,100/day, respectively, providing substantial earnings visibility.
With a third Capesize expected to join the fleet in early 2027, the company is increasingly positioning itself to benefit from the positive outlook for the dry bulk sector.
A 26% potential dividend yield combined with growing Capesize exposure certainly makes United Maritime worth watching.
Our updated valuation model is now available on the Ourios Analytics platform.
Explore our financial projections, vessel valuations and different market scenarios by making your own assumptions.
ouriosanalytics.com
Seanergy Maritime ($SHIP) has released its Q3/26 results, delivering another very strong quarter.
Q3 fleetwide TCE reached $34,266/day, up 46% YoY, while adjusted EBITDA increased to $40.8M. Nine-month net income reached a record $61.9M.
One particularly positive development is the increase in the quarterly dividend from $0.35 to $0.40/share, bringing the annualized dividend yield to approximately 10% at current share prices.
Seanergy is also continuing its fleet renewal programme, with an ambitious investment plan involving 12 Capesize and Newcastlemax vessels, including nine newbuildings and three modern Japanese-built secondhand vessels.
Looking at our model, at a share price of $15.58:
Q4/26 NAV: $24.16/share (P/NAV 0.64x)
Q1/27 NAV: $25.19/share (P/NAV 0.61x)
NTM Adjusted P/E: 3.36x
NTM EV/Adjusted EBITDA: 2.91x
NTM P/FCF: 2.55x
NTM Dividend Yield: 10.27%
In our view, Seanergy offers an attractive combination of dividend income, a significant discount to NAV and exposure to the Capesize segment. If you like to invest in Capesize segment, this is certainly a company worth keeping an eye on.
Our updated valuation model is now available on the Ourios Analytics platform.
Today, we will also be updating our model for United Maritime ($USEA), Seanergy's spin-off, whose shares surged 22% yesterday. Quite a move!
Explore our models and make your own assumptions.
👉 ouriosanalytics.com

Teekay Tankers ($TNK) has just released its Q3/26 results, and the numbers are outstanding.
The company reported adjusted net income of $175.8M, adjusted EPS of $5.04 and adjusted EBITDA of $188.4M.
And the outlook is even more impressive. Q4 spot rates are already reaching extraordinary levels, with Suezmaxes averaging $272,000/day and Aframax/LR2s $208,300/day on booked days so far.
At current valuations, our model points to an Adjusted EV/EBITDA multiple practically close to zero, reflecting the company's enormous net cash position and strong earnings generation.
However, there is one aspect we find rather disappointing: shareholder remuneration.
With around $1.5 BILLION in cash, cash equivalents and short-term investments, we believe the current quarterly dividend of just $0.25/share is remarkably conservative.
Given the company's enormous liquidity position and the cash generation potential of the current tanker market, we would certainly like to see a much more aggressive approach to shareholder distributions.
Our updated Teekay Tankers valuation model is now available on the Ourios Analytics platform.
Explore our financial projections, vessel valuations and different market scenarios by making your own assumptions.
👉 ouriosanalytics.com

Okeanis Eco Tankers ($OET, $ECO) has released its Q3/26 results, and the TCE figures are simply insane!
VLCCs achieved an average TCE of $260,100/day in Q3, while Suezmaxes reached $166,600/day.
And Q4 looks wild, that is what we were expecting.
During Q3, the company also secured short-term employment for five VLCCs at an average rate of $449,200/day, for 100-150 days.
So, with Q4 potentially reaching unprecedented levels, the next question is: what can we expect for Q1/27?
Even assuming a significant moderation from Q4 levels, these would still represent exceptional earnings.
With rates you can see in the screenshot, at current valuations, our model indicates approximately 2.2x NTM Adjusted P/E, 2.4x EV/Adjusted EBITDA and 2.1x P/FCF, with a potential, great and amazing dividend yield approaching 50%... I’m not sure if we realize it, but we could be looking at a dividend of around $15 for the next quarter 🤪🔥🤑
Okeanis continues to demonstrate why it is one of the most impressive operators in the tanker industry.
Our updated valuation model is now available on the Ourios Analytics platform. You can acquire them and try to make your own assumptions to guess what Okeanis’s rates will be, but the only thing you can be sure of is that they will always be the best.
It´s funny to explore different scenarios and make your own assumptions.
👉 ouriosanalytics.com

Okeanis ($OET, $ECO) TCE Q4/26:
VLCC fleet 48% of the available spot days have been booked at an average TCE rate of $688,800 per day and 87% of operating days have been booked at an average TCE rate of $430,300; on the Suezmax fleet 60% of available spot and operating days have been booked at an average TCE rate of $410,900.
Eurodry ($EDRY) released its Q3/26 results.
We have just updated our valuation model, and it is now available on the Ourios Analytics platform.
Explore the company's valuation, financial projections and different market scenarios by making your own assumptions.
👉 ouriosanalytics.com
Himalaya Shipping ($HSHP) has just released its Q3/26 results, delivering another very strong quarter.
Average TCE earnings reached $58,400/day, with net income of $33.3M and EBITDA of $52.7M. October TCE earnings remained strong at approximately $50,900/day.
The company continues to demonstrate its ability to outperform the Capesize market, supported by its modern Newcastlemax fleet and long-term index-linked charters with significant premiums over the Baltic 5TC.
At current valuations, the stock trades at around 7.9x NTM Adjusted P/E, 7.9x EV/Adjusted EBITDA and 6.1x P/FCF, while offering a potential dividend yield of approximately 13.3%.
Himalaya also continues to reward shareholders through its monthly cash distributions, having declared $0.75/share for Q3 and another $0.20/share for October.
Our updated valuation model is now available on the Ourios Analytics platform.
Explore our financial projections, vessel valuations and different market scenarios by making your own assumptions.
👉 ouriosanalytics.com
#shipping #drybulk

DHT Holdings ($DHT) presented its Q3/26 results.
We have simulated a scenario in which we write down the valuation of the vessels each quarter and apply reductions to shipping rates: -30% for Q1, Q2 and Q3/27.
Even under these assumptions, more than $500m TCE revenues in Q4/27 and dividend can go over $3.
At the current valuation and taking into account those rates, the company trades NTM below 3x adjusted P/E and adjusted EV/EBITDA —while offering a wild dividend yield of almost a 40%.
With our excel models, you can simulate any scenario you like just by changing a few cells.
Get them in: ouriosanalytics.com
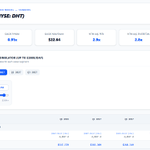
And, as something new, we have almost ready—will be available in a matter of days— our new platform (have a look to the screenshot), that will be included at no extra cost, for everyone who is already a user of our website through the launch offer that is still available, to reward them for their trust.
You will be able to adjust TCE using simple controls and see how the data —P&L, multiples, dividend yield...— adapts in real time to your scenarios.
And quite soon there will be more great news.
By the way, "launch offer" will finish quite soon— in a matter of days.
Web: ouriosanalytics.com
Questions? [email protected]


DHT Holdings, Inc. Third Quarter 2026 Results
$DHT
Q4 TCE outlook: 86% of the available VLCC days, combined spot and time charter days, have been booked at an average rate of $267,500 per day.

25
1,206
d’Amico International Shipping ($DIS.MI) released its Q3/26 results.
We have just updated our valuation model for d’Amico International Shipping, and it is now available on the Ourios Analytics platform.
Explore the company's valuation, financial projections and different market scenarios by making your own assumptions.
👉 ouriosanalytics.com
#shipping #tankers
International Seaways ($INSW) presented its Q3/26 results today.
We have simulated a scenario in which we write down the valuation of the vessels each quarter and apply reductions to shipping rates: 10% for Q4, 20% for Q1/27, and 50% for Q2 and Q3/27. Even under these assumptions, more than $800m TCE revenues in Q4/27 and dividend can go over $10.
At the current valuation and taking into account those rates, the company trades at a remarkably low multiple—NTM roughly 3x adjusted P/E and adjusted EV/EBITDA —while offering a dividend yield exceeding 30%.
I’m not sure what your take is, but the amount of cash they are generating is incredible; frankly, there is no easy way for this to end, regardless of who is in power in the U.S.
Reality is always stranger than fiction, but that’s the beauty of having financial models: you can simulate any scenario you like just by changing a few cells.
Do you want to make your own assumptions in an easy and confortable way?
ouriosanalytics.com
#tankers
