
Long Biased Biotech & M&A | tweets not investment advice | #PCManiacs
New York, NY
Joined May 2023
- Tweets3.6K
- Following817
- Followers3.4K
- Likes8.3K


Pinned Tweet
PCM's YE 2025 Investor Letter; key learnings and the path forward for the #PCManiacs $xbi $ibb
open.substack.com/pub/patien…
21
6,456
Please also refrain from using the ticker ABVX. Don’t mean to be a hypocrite with original post

If you think 🦂 report is absurd, please kindly refrain from yelling into the abyss on $abvx .. it will not help. I promise
12
1,252
If you think 🦂 report is absurd, please kindly refrain from yelling into the abyss on $abvx .. it will not help. I promise
Be relatable. Sometimes it’s that easy to win the crowd

Dave Ricks, the CEO of @EliLillyandCo is on X sharing unfiltered scientific nuance plus clinical research on glp1/gip data. This is refreshingly uncommon for a large global biopharma leader to do. Highly recommend following!
7
1,519

$CMPS
Daily short interest data from Markit suggests that on the Nov 2nd "Usona filed their NPV" rumor, triggered ~5M shares of incremental short positions.
My interpretation: The news came out earlier in the morning and the stock opened weak but not too bad. Then throughout the morning "someone/s" was leaning into the stock and just crushed it.
It could have been a holder (or multiple holders) selling, or it could be new people shorting.
This data from Markit suggests the latter.
(Note that this is based on settlement data, so short sales that happen on 11/2 don't show up until 11/4 and 11/5.)
I prefer to see people shorting versus longs selling, as it's more likely for the shorts to cover, versus a large long leaving the stock has a low chance of coming back.
If they're still short by the time of the approval announcement, hopefully they get squeezed. Maybe today's strength is them covering and moving on?
Disclosure: Creek Drive and its affiliated funds holds a long position in CMPS. Views expressed are current opinions for information only, subject to change and are not investment advice or a recommendation to buy or sell any security. Investing involves the risk of loss and past performance is not indicative of future performance. See the disclosures link in my bio for more important information.

1
1,110
Would give the #PCManiacs great joy to be vindicated with a $SNY debt re-rating and sustained move to the upside in their stock with $INSM (would be surprised if they won process given balance sheet / capacity of others this would make sense for, but never say never)
Has been a long road / round-trip in $INSM .. riding the rollercoaster at 15% of fund (prior to today) on a good ole disconnect between recent trading range and DCF valuation (running higher WACC and zero terminal value versus the analysts [many need to revisit their insane terminal value assumptions on zero revenue contribution from pipeline pre-Brinsupri LOE])
We'll see what happens. Price discovery across the commercial basket is inevitable, at some point? Isn't it? Isn't it?????? $XBI $IBB $bbc
An interesting idea would be for activist funds to build positions in a basket of BP whose stock Pxs are in the dumps. As opposed to taking tactic of highlighting all the bad BD / no BD these Cos have done and advocating for "change" (mgmt changes / pipeline prioritization -> note: most of these funds don't have the scientific chops to get in the weeds on existing clinical ops, etc), they could instead press them to do growth BD where the outcomes of said BD are not binary. Easy comps to reference below. Ofc, can't look at everything in a vacuum, but datapoints provide context
$jnj +96% since $ITCI (13-Jan-2025)
$MRK +81% since $VRNA (+ others)
$ABBV +34% since $APGE (22-Jun-2026)
$BIIB +35% since $apls
$GILD +116% since $CBAY (2024)
$NVO $SNY $bmy in particular should take note given their balance sheets
@Elliottmgmt @ Jeffrey Smith @BillAckman @DanielSLoeb1 @ Alex Denner @ Corvex
Don't need to campaign for BoD seats. Just need to own the stocks and publicly press for growth BD. Formula is pretty simple. Happy to collaborate
10
1,808
You can only make money on $vktx trading it between $30 and $35. Way too expensive at $26.70
5
1,406
$syre was speaking to us today, wonder what it was trying to say 🪿
$GSK 's Head of BD at Jeff: "I think one of the advantages of a Head of BD reporting to the Chief Scientific Officer... rather than the CFO is you park those conversations to the end of the line rather than prematurely discuss how you fund a deal... all great deals get funded"
Totally understandable posture, but all things are not equal / most BP are not $lly $jnj $vrtx with line of sight on 7-Yr+ growth. $GSK has been relatively aggressive on BD so they get a pass for time being... but other BP should NOT de-couple the growth mandate from the scientific mandate. The former enables the latter, and the early-stage BD chickens will continue to come home to roost unless they are de-risked by the top line.
Very puzzling to me how BD teams almost never mention stock price trajectory / implications of their deal mandates, and how they associate risk-aversion almost exclusively with early-stage, as if BP is categorically better than SMID at R&D (they aren't, save in massive / multi-indications that require significant P&L)
Hopefully $BMY $NVO $SNY $NVS figure this out in immediate term, with $AZN $AMGN $REGN $rhhby $MRK $pfe to follow ... $ABBV has some time / $lly $jnj $vrtx can be a bit more deliberate $XBI $IBB $bbc
All fair points raised on M&A dynamics, BUT the issue with going early / spraying bullets and hoping you get 1 or 2 wins is that most large caps need to confront their LOE lifecycle(s) as a first step. When we get an $rna failure for $nvs, there will inevitably be pipeline culling across other parts of the business as they stare down Entresto and then Jakavi, Cosentyx, Kesimpta, Kisqali thru 2031.. underrated aspect of $rna (and all large BD) is that funding other internal pipeline projects + step-wise licensing in ASO/RNA-adjacencies was contingent upon DM1 success. And because of their LOEs, failure here will have ripple effects beyond just neuromuscular. Financially untenable to do everything
Not every Pharma is $lly or $jnj right now. How do you think $bmy $sny $nvo $regn $nvs $azn $amgn stocks would respond if they did $cnta, $verv, $advm, etc right now? Or if $MRK did these deals in 2025? These companies need to be more *mathematically* / commercially / financially driven on BD in 2026 / 2027, until they can *afford* to look for high-risk science projects / synergies.
Artisan is on the right track here. Other BP should pay attention. Their M&A needs to de-risk upcoming binaries (large cap stocks should not swing 10 to 15% on data, that means they aren’t trading defensively)
Patients Capital Management LLC retweeted

You mean you don't appreciate when your biotech holding with fantastic data is up 40% in the premarket with 50% more upside to fair value, and then gets crushed to flat at open because risk at a large MM market sold a pod's holdings for blowing up on a MRNA short position, and then a quant momentum strategy shorts it because of the big pullback, and then a quant fund piles on the selling pressure by hedging their AI long trade by shorting interest rate risk out with a SMID cap biotech short, and then the stock is down 15% and no one knows why so an analyst publishes that obviously the stock is down because (pick random datapoint that doesn't matter) but in reality was just persuaded on a call with a pod PM to be bearish because they had a short position they needed to press and then that narrative gets entrenched and you're sitting here wondering why this company swung 60% down on great data and is financed through CF+ and trades at a big discount to some other biotech company and the world moves on to the next company with data tomorrow and no one cares to re-visit your company because it's a "catalyst desert" for 3 months? And pharma then passes over it and buys an undifferentiated pre-clinical private China asset instead of your company, which blows up on them a year later and they write it down but now your company needs to finance at a discount to the prior data?
How could you not love that?


The way the data are maturing, appears $elvn will be the winner in the post-Scemblix (2L) setting. So basically $MRK needs to go for 1L and 1L only? Is there even rationale to study in post-asciminib setting given the recent updates? Common sense would suggest you’d also switch from allosteric to active site in real world, no? Gets interesting if $elvn able to generate compelling 1L H2H data
Patients Capital Management LLC retweeted

Slide from @LifeSciVC, citing @DaphneKoller's work, estimating AI's prospective impact on drug development timelines. Bruce is the level-headed GOAT of biotech investing, and Daphne is among the smartest AI researchers. Make of this what you will...


It’s been a full year (that’s 365 days for the numbers guys) since the last announced competitive biotech M&A process with $mrk $cdtx
The fundamentals have not changed, even though BP has caught a rotational bid this year and perhaps BP mgmt have tricked themselves into thinking investors believe in their pipelines (wouldn’t call most BP defensive necessarily, but neither here nor there given the moves). At some point we will see mean reversion, if the big long onlies find themselves on the wrong side of some big upcoming binaries. Or maybe they finally transact on growth assets to support this window of multiple expansion (although some still in purgatory and it’s the only path to movement up the P/E to revenue growth curve, see image below from mid-Oct which is stale but consistent)
We’ll see. My gut says a wave of deals is coming. Disclaimer: my gut has been saying this for about 8 months. Tread carefully in the chase $xbi $ibb $bbc

8
1,232
It’s been a full year (that’s 365 days for the numbers guys) since the last announced competitive biotech M&A process with $mrk $cdtx
The fundamentals have not changed, even though BP has caught a rotational bid this year and perhaps BP mgmt have tricked themselves into thinking investors believe in their pipelines (wouldn’t call most BP defensive necessarily, but neither here nor there given the moves). At some point we will see mean reversion, if the big long onlies find themselves on the wrong side of some big upcoming binaries. Or maybe they finally transact on growth assets to support this window of multiple expansion (although some still in purgatory and it’s the only path to movement up the P/E to revenue growth curve, see image below from mid-Oct which is stale but consistent)
We’ll see. My gut says a wave of deals is coming. Disclaimer: my gut has been saying this for about 8 months. Tread carefully in the chase $xbi $ibb $bbc
2 friendly reminders:
1) the $xbi is just a number. Doesn’t have a multiple. Really just a gauge of momentum. So saying biotech is over or undervalued based on where $xbi is trading is somewhat lazy (even if directionally true)
2) there hasn’t been a truly competitive M&A process since $CDTX last year, especially for late-stage / commercial assets
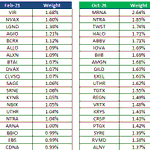
You want to see what true $xbi momentum looks like, let’s see what happens when the large cap bios (esp those in the index) that need to transact start to do so, and they inevitably buy names with somewhat high weightings. Double trouble

