
Semi analyst aiming for high yields and low defects
India
Joined June 2010
- Tweets3.5K
- Following2K
- Followers627
- Likes5.8K



$TSM 3Q26 beat expectations. Revenue $46.7B +16%QoQ 41% YoY. GM 66.4% dilution from the initial ramp of N2 . Growth driven by price and mix.
TSMC is evaluating a Texas fab. If it partners with Terafab, TSMC would run the fab. xitter.cf/Parv_S/status/21077528…

Parv sharma retweeted

🔦MicroLED takes shape in Silicon Photonics.
This is a snippet from @CounterPointTR team at #OCP26
@credosemi demonstrating 1.6T ALC (🟣purple cable) with MicroLEDs for long, efficient, and high bandwidth links
The commercial models coming next year will be compatible with MLED or MicroVCSELs.
Credo also is showing a static demo of MVCSELs used for near-packaged optics in a tray designed with @SenkoConnect
MLED & MVCSEL - coexistence or collision course-is one of the major issues for scale-up and scale-in as we highlighted in:
Counterpoint's Monthly Optical Interconnect & Networking Intelligence tacker
counterpointresearch.com/en/…
$CRDO $MSFT


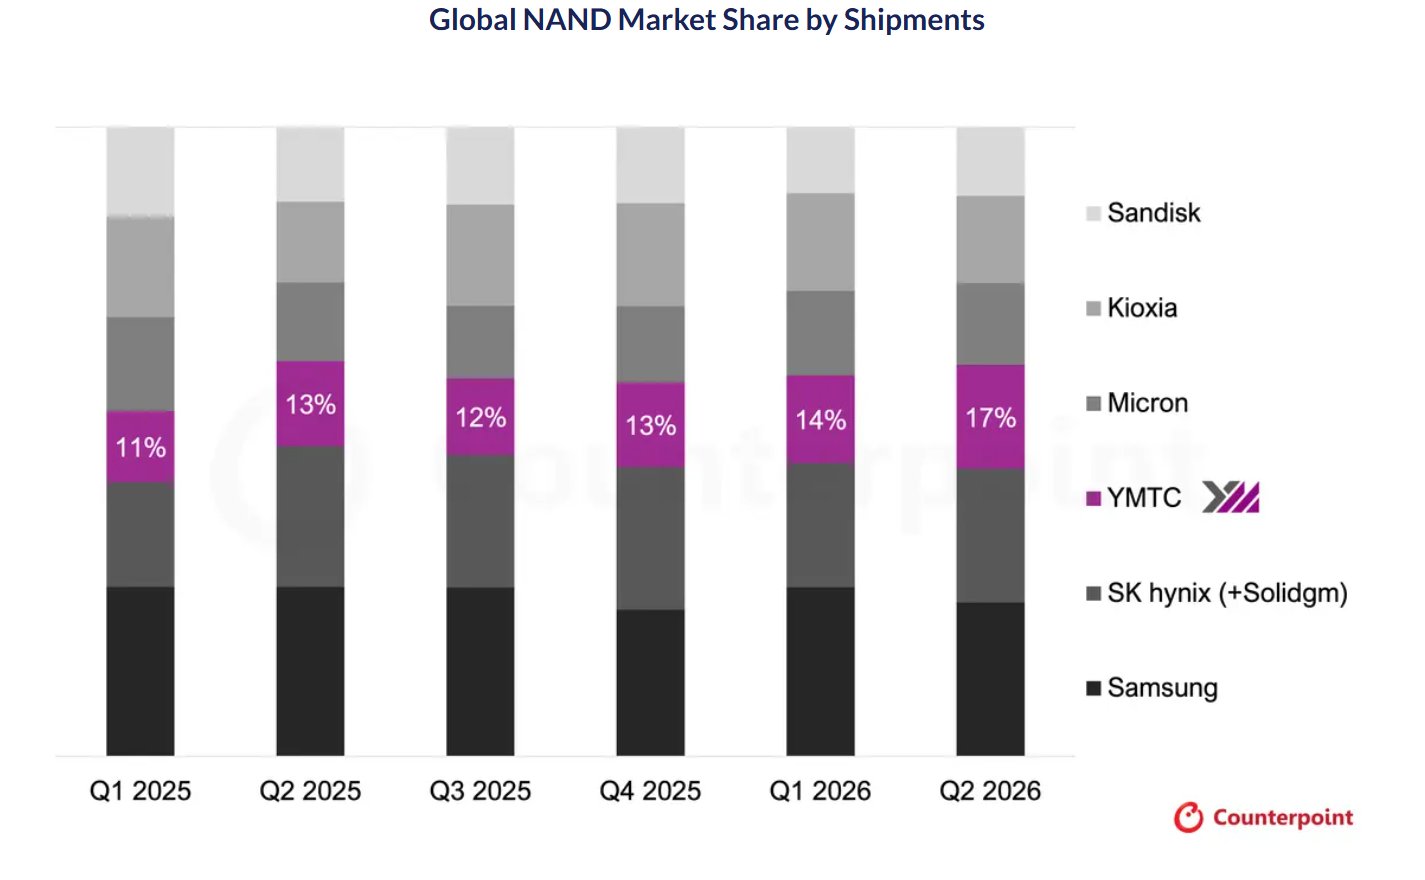
YMTC Files for Landmark IPO:
1. YMTC is leveraging its proprietary Xtacking wafer-bonding architecture to expand into DRAM production, running test runs of 16Gb LPDDR5 and planning faster designs for Fab 3.
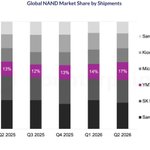
2. YMTC to 3rd place globally in NAND flash shipment volume in Q2 2026, trailing only @SamsungDSGlobal @SKhynix
3. Much of YMTC's momentum is tied to a segment it barely served two years ago: enterprise SSDs for AI data centers.
More here
counterpointresearch.com/en/…
Parv sharma retweeted

Even the co-passangers are also happy on Abhijit Dipke's arrest. ❤️
India is united against CJP 🇮🇳
$SWKS @QorvoInc merger strengthens BAW filters, antenna tuning and ET portfolio. Complete RFFE for PA modules and WiFi.
Also expansion to defense and aerospace with mobile about 2/3rds of total.
Missing links are modem, transceiver and end to end integration modem to RFFE which $QCOM has.
$AAPL remains the top customer, if @Apple acquires @skyworksinc it have same portfolio breadth as Qualcomm.


Skyworks and Qorvo are now one company – uniting deep expertise, talent and a commitment to innovation to better serve customers and accelerate technology leadership worldwide. Every step forward brings us closer to what’s possible. #FutureInFocus
investors.skyworksinc.com/ne…


Parv sharma retweeted
😅 Affordable High-Speed is no issue in India.
✅For $4/month Indians get high-speed 5G 28GB+ data
✅Coverage is not an issue. 99% coverage for 5G
Any operator looking to launch Sat Broadband need
✳️Opportunity for Satellite is only in very remote places and maybe some B2B scenarios.
✳️ Data, Space Sovereignty & Security is non-negotiable for any nation, especially India.
✳️ Can’t be used as “Surveillance” for other nations.

$CRWV planning to add 204MW with @adaniconnex
after hyperscalers, neo clouds are also coming in India.
Overall investment in DC to reach maybe ~$90B-$100B in India. xitter.cf/Parv_S/status/20705541…

We're coming to India. Home to some of the world's best tech companies and developers. Planning to add 240 MW with @AdaniConneX and building a local team. $CRWV
$TSM sublease part of terafab if they want :D
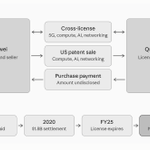
$QCOM added clarification that it buying some Huawei US patents and cross-licensing patents with Huawei. No other details.
1. QTL revenue uplift: $ started to flow other way, 2020 $QCOM @Huawei has cross licensing agreement which QCOM recognized under QTL and Huawei as net payee.
2. Patent purchase in compute AI, AI and networking not cellular. This is important as QCOM gears towards the Datacenter with custom ASIC, CPU and rackscale.
Bloomberg Law, says the agreement also touches near- and co-packaged optics and Huawei's LogicFolding chipmaking technique.
3. Huawei IP monetization: Selling licence to US based companies as it cannot directly do busniess.
4. China Market access: Qualcomm has significant exposure to Chinese handset marker, Deal with Huawei makes sense. There are also talks of DC client in China for Qualcomm so second part makes more sense.
More clarity will be available on next earning call.

$SNPS Investor Day laid out a new business model which is $ARM like royalty and a revenue base that scales with compute.
Its a hedge against AI shrinking engineer head count. Synopsys's answer is that agents call its tools more often. Models explore, but sign-off engines remain the physics ground truth.
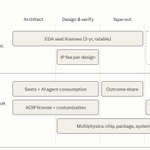
Old model billed engineers and design. New model is based on 3 revenue streams
1. Custom IP ("Factory 2")
co-design IP around one customer's workload, then get paid three ways: license + customization + royalties on every unit shipped. $AMZN $1B+ in license fees across Graviton, Trainium and Nitro (royalties excluded). Target: $1B of this revenue by 2030. Royalties to eventually exceed license fees, but none from Amazon in FY27.
2. AI-driven EDA
subscription + consumption + outcome-based revenue share, starting with GPT-Synopsys built with @OpenAI . 50+ customer engagements incl. @intel @nvidia , @MediaTek Samsung Memory
3. Silicon tosystems
Custom chips need packaging, thermal and stress analysis. One design win now pulls through IP + EDA + Ansys multiphysics. Target: $400M in revenue synergies by FY29.

In July, I told @Analyticsindiam that EDA companies are deploying AI agents to run more compute cycles per design, enabling better outcomes for chip designers and more revenue per customer. At yesterdays Synopsys Investor Day, that became a business model.
The result is revenue that scales with compute consumed and silicon shipped, not just engineer seats. Its a step toward an Arm-like model, though royalties will lag and stay concentrated for now.
It also closes a loop. In July, @OpenAI used Codex alongside @Broadcom 's stack to take Jalapeño to tape-out in nine months, and I argued Codex was a productivity layer, not a replacement. Two months later, OpenAI chose to productize chip-design AI with Synopsys, not around it.
My framing stays the same: AI accelerates the rule-based loop of checks, timing closure, simulation and verification. Deterministic engines still sign off. Humans own the judgement calls: what to build, chiplet versus monolith, memory topology, analog and post-silicon.
analyticsindiamag.com/ai-fea…

1. Alibaba's Zhenwu V900 isn't just a chip story. My take,
2. Alibaba is China's biggest listed capex spender: record RMB 67.7B (~$10B) in the June quarter, ~25% of revenue. Half of the RMB 380B 3-year plan is spent already, ~3 quarters left at this run rate. A 20GW-by-2032 target means a much bigger envelope is coming.
3. In-house silicon is the lever. Self-designed chips cut AI infra payback to ~2.5 yrs from ~3 on a 5-yr server life. ~500k T-Head chips shipped; V900 is 3x the last gen. Every gigawatt gets cheaper.
4. Cadence matters: annual roadmap, launches pulled forward. Design isn't the bottleneck anymore. Leading-edge nodes, HBM and advanced packaging are.
5. V900 is H100/H200 class on the chip. Alibaba closes the gap at system level: interconnect, power, Qwen, software, and clusters of up to 500k chips.
6. Different risk profile: the US asks whether ~$750B of hyperscaler capex outruns demand. China treats AI infra as strategic, so it's supply-constrained, not demand-sensitive. 20GW is big, but each US hyperscaler is already multi-GW.
Takeaway: not China overtaking the US, but two separate AI stacks, US global, China at home. The gap narrows on foundries and HBM supply, not chip design.
Quoted by @AP, @FortuneMagazine, @barronsonline, @NBCNews and @ABC.
fortune.com/2026/09/22/aliba…
barrons.com/articles/alibaba…

