

ENTJ | Analyst @TheSpartanGroup | ex-Risk @HSBC 💬 Everything expressed here is solely my own opinion.
Joined June 2021
- Tweets2.1K
- Following104
- Followers30
- Likes1.3K
One thing i might say, i was correct when Hype was $21, and right now spot another undervalued token - METUSDT.
Everyday, i track revenue generating tokens, and i think Meteora is the next token that need to put an eye on. I think questions related to technology, or what the project is doing, you guys can chatgpt them easily.
In this post, just want to highlight 2 key fundamental/valuation metrics:
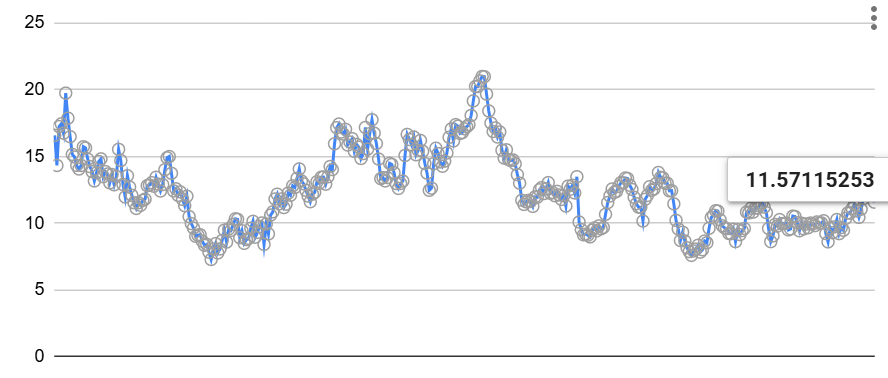
1. Currently, FDV/Rev of Meteora is lower than the median of the most current 50 days, specifically, -16.32% lower. This is the highest mispricing among the tokens i track. But this alone cannot say anything.
2. Peers multiple analysis (See image 2):
Comparing it with peers in the market, the minimum implied valuation for Meteora is around $0.29 (which is even higher than the curent $0.25 price). I will take median of FDV/Rev as a benchmark (it has always been my favorite metric), the upside is 3x from here.


Damn, i did not think i am so good at predicting


Rain definitely raise at a good premium.
17x increase in 10 months. 30x card growth. 38x payment volume growth.
Visa-based issuers and cards from @raincards ,@RedotPay are also showing significant growth in deposit volumes. At the beginning of the year, the total volume was around $61M, and by December 2025, it had surged to $364M - a remarkable 496% increase. This trend highlights not only the growing adoption of crypto-linked @Visa cards but also the expanding role of these platforms in everyday digital finance.
Valuation approach:
with 1.95B and assume $30M annual revenue (3B TPV with assumed take rate of 1%). -> 65x multiple
while for Redotpay (a similar competitor): 1B valuation with 100M (10B Volume with 1% assume take rate) -> 10x multiple.
Clearly, Rain considered as the fastest growth in the sector create a good premium for the company.


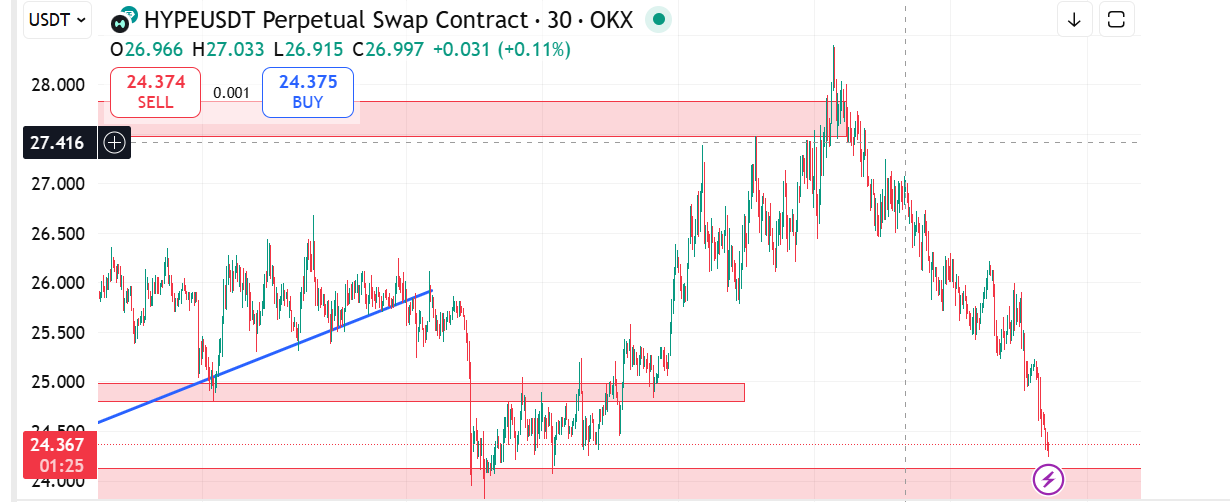
Predict the correct top of $Hype, the current price movement reflect how it's not a sustainable price growth (due to high OI - as i discussed in the post before).
Next important price target would be $24, current multiple is 11x. A safe trade would be around $21 since:
- In the last 30d, most perp projects have difficulties in revenue and fees. Hyperliquid 30d annualized rev goes down to around $500-600M, while before is $800-900M. Historically, a safe MC/annualized Revenue is 9x-10x. With 10x, $HYPE would fall to $21
Im a pro-hyperliquid guy, but to be honest, will be cautious with buying $Hype, at least it around $21-22, that would be a safe bet for me
My short trade on Lighter was actually supported by the fact that tvl and revenue generated by them declined significantly.
For me, that's a show of lack of strong fundamentals.
With the current Annualized Revenue, I believe the fair valuation could fall down to 1.7B - 2.3B

Lighter TGE: What FDV should we expect? (Independent Personal Research)
The DEX and Perp DEX sectors have seen a massive surge in attention lately. With the launch of Hyperliquid and then Aster (backed by CZ), market participants are looking closer at the major players. Lighter is the next big TGE, and finding its fair value is key for anyone looking at launchpads, Polymarket bets, or potential positions post-listing.
I’ve seen many analysts on X focusing on FDV/TVL, but I personally lean toward FDV/Revenue. But to be fair, I conducted a valuation analysis comparing Lighter against peers like Hyperliquid (HYPE), Aster, and Avantis, etc. using three core approaches:
- FDV / TVL
- FDV / 30d Volume
- FDV / Revenue (My preferred benchmark)
Why I prefer FDV / Revenue? In a mature or risk-off environment, this is the cleanest business-like metric. If you have a look at the image attached, this approach provides the tightest implied valuation range compared to TVL or Volume, making it more reliable. While:
- FDV/TVL is often a "noisy" metric for DEXs because TVL isn't the product, execution is.
- 30d Volume is highly regime-dependent (bull vs. bear) and can be easily distorted by short-term incentives.
Therefore, based on the median FDV/Rev of its peers, a reasonable range for Lighter would be around $2B – $3B FDV (in my opinion, this is my safe zone).
At the current pre-market price of ~$3.46, it carries a slight premium. However, looking at the MEXC Launchpad prices ($1.6 for new users / $2.0 for existing), it looks like a safe bet relative to the fundamentals. Personally, it would be interesting to look for speculation positions based on the analysis and how scenarios play out.
At the bottom line, as the market is getting more mature, you will see investors or traders will go with bets that are backed by logics and fundamentals.
Disclaimer: Again, this is for insight and research purposes only, not investment advice. And this post is also not related to any parties, it's a personal opinion.


As expected

Lighter TGE: What FDV should we expect? (Independent Personal Research)
The DEX and Perp DEX sectors have seen a massive surge in attention lately. With the launch of Hyperliquid and then Aster (backed by CZ), market participants are looking closer at the major players. Lighter is the next big TGE, and finding its fair value is key for anyone looking at launchpads, Polymarket bets, or potential positions post-listing.
I’ve seen many analysts on X focusing on FDV/TVL, but I personally lean toward FDV/Revenue. But to be fair, I conducted a valuation analysis comparing Lighter against peers like Hyperliquid (HYPE), Aster, and Avantis, etc. using three core approaches:
- FDV / TVL
- FDV / 30d Volume
- FDV / Revenue (My preferred benchmark)
Why I prefer FDV / Revenue? In a mature or risk-off environment, this is the cleanest business-like metric. If you have a look at the image attached, this approach provides the tightest implied valuation range compared to TVL or Volume, making it more reliable. While:
- FDV/TVL is often a "noisy" metric for DEXs because TVL isn't the product, execution is.
- 30d Volume is highly regime-dependent (bull vs. bear) and can be easily distorted by short-term incentives.
Therefore, based on the median FDV/Rev of its peers, a reasonable range for Lighter would be around $2B – $3B FDV (in my opinion, this is my safe zone).
At the current pre-market price of ~$3.46, it carries a slight premium. However, looking at the MEXC Launchpad prices ($1.6 for new users / $2.0 for existing), it looks like a safe bet relative to the fundamentals. Personally, it would be interesting to look for speculation positions based on the analysis and how scenarios play out.
At the bottom line, as the market is getting more mature, you will see investors or traders will go with bets that are backed by logics and fundamentals.
Disclaimer: Again, this is for insight and research purposes only, not investment advice. And this post is also not related to any parties, it's a personal opinion.