





prefshares retweeted

Excited about our new Bee devices launching today. They turn your conversations into summaries, to-dos, and reminders, so the details are there when you need them.
Bee Frontier goes on your wrist or clips to your clothing, and Bee Eclipse snaps to the back of your phone to catch what you'd otherwise forget throughout your day, whether it's notes from a class you're taking, the details of a trip you're planning, or an idea that comes to you in the car.
They connect to Alexa+ and Amazon.com, so the things you mention are easy to find later. And you're always in control…one button turns it on or off, a light shows when it's on, audio is never stored, and only you can see your data.
Think folks are gonna find this really handy. aboutamazon.com/news/devices…
prefshares retweeted

Thank you @PrefShares for engaging with a constructive and thoughtful response. (anyone curious to read my original piece, go here: mbi-deepdives.com/aws-vibes/)
Let me take your points in turn.
Retail. I like Amazon’s retail business too, and I agree there are losses buried in ex-AWS. But the profit engine in core retail today is advertising, and I think it’s fair to say ads carries a question mark right now. Consumer agents on one side, the FTC case, the auction-mechanics issues or the bid shading possibilities I’ve written about on the other (see here: mbi-deepdives.com/amzn_ads/)
My base case is still that Amazon figures it out, but it’s not unreasonable to wonder that there is a legitimate fat tail risk to Amazon’s ability to COMPOUND core retail profits which can (should?) weigh on the multiple we may want to put on these profits. Also on $WMT, I haven’t met an $AMZN shareholder yet who thinks WMT is attractive at ~28x LTM EBIT.
Okay, let me now get to AWS.
Cost curve. On the $NVDA discount, I think the argument runs into NVIDIA itself. The hyperscalers are the only customers also building chips to displace it, so NVIDIA has every reason not to hand them a structural cost advantage, and it hasn’t: equity in the neoclouds, capacity backstop, or direct financing for OpenAI to buy gigawatts with no hyperscaler in between…Jensen has made it abundantly clear he doesn’t want to operate in a world where Hyperscalers call the shot. Whatever discount the hyperscalers get, NVIDIA likely hands back to the marginal producer in cheaper capital and risk sharing.
Power is a few percent of a gigawatt-year’s revenue, so cheaper PPAs are worth maybe a point or two, and unlikely to be a needle mover for overall economics. And cost of capital advantage is shared by all Hyperscalers, and also an advantage that is directly being largely negated by NVIDIA with their balance sheet support to neoclouds.
I do agree it’s not obvious to me either why neoclouds have a DURABLE advantage over hyperscalers. But the capacity they’ve bult and are building is pretty real. If AI demand disappoints or we hit a digestion period, the neocloud equities will get obliterated but the gigawatts stay, get repriced, and pressure everyone, hyperscalers included. The concern again is that NVIDIA has an obvious interest in keeping its buyer side VERY fragmented.
Short-term margins. No argument there. Everyone selling compute today is making money hand over fist. The question is whether 2026 is representative of medium and long-term economics. If it is, AWS isn’t $1.3T; it’s comfortably over $2T.
Bedrock as a capital-light royalty. Not sure I agree with your framing, and I think the simplest way is to follow the token. When an enterprise buys a Claude token on Bedrock, it’s generated on a Trainium chip, in an AWS data center, that AWS paid for. That chip is already in my gigawatt count. So whatever AWS keeps on that token I don't see it as a royalty on someone else’s capital, it’s just a markup on its own. Capital-light royalties do exist in AI, but they accrue to whoever owns the weights: Anthropic earns one when $GOOGL sells Claude through Vertex or $MSFT sells it through Foundry (their chips, their utilization risk, Anthropic’s cut). More importantly, let’s notice who will set the royalty rate. The enterprise pays roughly Anthropic’s list price on Bedrock, so AWS’s cut comes out of Anthropic’s margin and Anthropic, which can serve the identical token through its own API, Vertex or Foundry, decides how big that cut is (if not today, they will over time). A royalty where the payer sets both the product price and the royalty rate SHOULD/WILL be a thin one.
Enterprise / other AI. I agree with all six of your points. Those points are why that bucket earns ~2 points over its cost of capital in my model rather than zero. I know 2 points may seem a little low, but the invested capital in that bucket is $468B in 2035, so that’s ~$10B a year of economic profit. I’m hesitant to extrapolate to much more. All six advantages are more or less shared by AWS, Azure and GCP, so they’re a moat against neoclouds and the labs’ direct APIs, but probably not much against each other. The neoclouds know serving hyperscalers and labs isn’t durable, which is precisely why they’re trying to move into this segment as well. And the labs themselves are building first-party products for the same customers. Five to ten points of excess return on a ~$500B base would be $25–50B a year of rent on an input with growing number of alternatives. I’ll admit I am far from certain where that shakes out (could be anywhere between 1 and 5 points IMO).
Core cloud. Fair it’s hard to separate from AI, and AI is clearly helping it. That’s why core grows ~21% in 2026 in my model, well above the ~13% it had slowed to before AI, when optimization was the story. My model still triples the core to ~$360B by 2035. But yes, reasonable people can land above me here.
The key point I was trying to drive home is the exercise actually helped me tone DOWN my own bearish “vibes” on AWS a bit once I realized market is actually fairly skeptical about AWS capex being value additive. The objective of making the assumptions explicit is to see if I perceive any vehement disagreement with what the market is underwriting. Following the exercise, I just realized I do not have such strong disagreement. Market and I are more or less likely on the same boat in evaluating AWS long-term future.
Thanks again. Always a pleasure to have diligent readers.

Some thoughts on $AMZN/AWS –
Enjoyed @borrowed_ideas recent AWS piece, and a lot of respect for publishing the model. I think he's a good analyst, which is why it makes my disagreement with him on AWS even more fun.
His base case is that AWS is worth ~$1.3T and AWS's AI capex earns roughly its cost of capital.
I shake out pretty differently... a few thoughts:
First, let’s get Amazon Retail out of the way. 2027 consensus retail EBIT (North America + International) is ~$56B. Walmart trades at ~25x CY27 EV/EBIT. Put Walmart’s multiple on Amazon’s retail earnings and retail is worth somewhere around ~$1.4T.
I’d personally take the over on that. Retail is materially under-earning... burdened by Alexa, supply chain services, the grocery push, Kuiper/Leo (LEO satellites), and an international business that’s still early on its margin trajectory. But for the sake of argument, call it fair.
Back that out of Amazon’s ~$2.9T EV and...
~$1.5T is left for two things: AWS and the frontier lab stakes.
Mark the stakes below current headlines (so let's say Anthropic at $1.5T, OpenAI at $1.0T) and Amazon's stakes are worth ~$350B.
That leaves ~$1.15T for AWS, or ~12.5x 2027E consensus AWS EBIT.
That’s below his $1.3T base case... which already assumes AI CapEx is value-neutral. Put simply, the market is already assuming AWS's AI CapEx creates virtually no value.
MBI's model splits AWS into three demand buckets: (1) the frontier labs, (2) enterprise / “other AI”, and (3) the core non-AI cloud – and I address each below.
(1) Frontier labs. His model has Anthropic and OpenAI paying ~$8B per GW-year for Trainium and ~$11B for NVIDIA, with lab capacity flat after 2029. At those prices the bucket earns exactly its ~9.6% cost of capital. Trainium sold to labs actually earns a bit less.
I’ll concede that renting GPUs to frontier labs is the lowest-return business of the bunch, with two customers each with enough bargaining power to negotiate hard on price / threaten to insource evenually. However, the hyperscalers are, long term, likely to be the low on the cost curve, for three reasons...
(i) They’re the largest NVIDIA buyers in the world, so they get a discount on the most expensive part of the stack
(ii) They have the cheapest power: long-running, pre-existing PPAs, and utilities are inclined to give them the best pricing
(iii) They have a far lower cost of capital than anyone else renting out compute
Some neoclouds have done a better job architecting efficient token-serving systems... But I haven’t heard a compelling argument for why that’s a durable advantage.
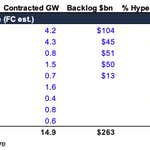
Also... power is a binding constraint, and the hyperscalers are locking up the land, power and shell (look at the backlogs & build plans as % of total incremental capacit...). If we stay supply constrained, they’re incredibly well positioned. And there are plenty of worlds where regulatory pushback limits how much supply comes online, which rewards whoever already owns the supply.
Shorter term... At ~$5.00/hr for B200s and ~$2.50/hr for H200s, my math has GPU rentals earning well north of 50% EBIT margins and ~50% cash-on-cash returns. For now, at least, the most commoditized version of this business isn’t earning anywhere near commodity returns.
And AWS doesn’t just rent compute to the labs. Bedrock (like Foundry at Azure and Google’s "enterprise agent platform") takes a cut of the lab tokens it distributes. It's a capital-light royalty. These are holistic relationships. The hyperscalers lend the labs their balance sheets because they know they can distribute those tokens through the greatest enterprise distribution platform of all time.
Enterprise / “other AI”. MBI prices it off what customers can theoretically afford to pay (less than the frontier labs): "~$20B per GW-year today, falling to ~$14B by 2030 (arguing Azure, GCP, OCI and the neoclouds compete on price). Tis bucket ends up earning ~2pts over its cost of capital.
That framing treats enterprise AI as simply renting raw compute capacity. Some enterprises rent GPUs directly, but most enterprise demand will be inference, and inference is far more likely to be bought as a managed service vs. GPU hours. There are numerous reasons that these business should earn excess returns:
(i) Security, identity and governance are already in place. Who can see what, where, when, and what did they see? That’s the bedrock (no pun intended) of identity and access management. Most orgs already run it in AWS or Azure... and it’s quite painful to rebuild.
(ii) The model weights are hosted inside the hyperscaler, so your data isn’t sent to OpenAI or Anthropic. Plenty of companies still aren’t comfortable with that.
(iii) You burn down existing spend commits instead of onboarding a new vendor, which is a big lift in a large org (people like one throat to choke).
(iv) It fits natively with the rest of your IT environment.
(v) Model-neutral orchestration: routing the right job to the right model at the right time, mix open-weight and frontier models, and avoid going all in on one lab that might fall behind or adopt policies you don’t agree with
(vi) The largest SIs and their quasi-FDEs are building on these platforms.
And the data we have suggests Bedrock, Foundry and Vertex are outgrowing direct lab spend. Starting from first principles (switching costs, barriers to entry, real managed-service benefits), I'd have a hard time arguing this "segment" barely out-earns its cost of capital over time.
Core non-AI cloud. MBI's model takes it from ~$120B of revenue in 2025 to ~$360B in 2035, a ~11-12% CAGR from 2025 (~10.5% from 2026), with growth fading to 7% by the end. This is where almost all of his value sits, because it's the only segment where ROIC materially exceeds WACC.
For starters, I’m not sure you can cleanly separate core cloud from AI anymore.
An agent is simply a model working in a computer/terminal-like environment... therefore it needs a CPU, databases, file systems and storage (read: agent memory), and access to other apps for tool calling. Those are all traditional cloud workloads.
Agentic AI pulls a tremendous amount of traditional infrastructure along with it. It’s why we’re seeing CPU shortages and an acceleration in "non-AI" compute/storage/networking spend.
I’ll cede the point that you can separate the two. But even if you can, that ~10% CAGR number looks quite low.
Last, the frontier lab stakes. The bear world where compute is a commodity and the labs scale so fast they buy their own compute is also a world where the labs are enormous businesses. In that world, the ~$350B worth of stakes should probably double or triple.
Add it all up: lab dedicated compute + Bedrock that earn more than Amazon's cost of capital, enterprise AI that earns a managed-service/PaaS return, a core cloud that grows faster than 10%, and if not... lab stakes worth multiples of today... and I have a hard time seeing $1.3T being a justifiable valuation.
I appreciate the work by MBI. And it’s great because it makes the assumptions explicit. I just happen to disagree with several of them.
Thanks for posting @borrowed_ideas.
This is so dumb.
Does she also want to go ahead and capitalize the value of the earnings they’re going to generate from that compute?
Thought not.

We’re moving towards a scaling method where we don’t even understand the model’s internal thoughts.
Literally speed running Tower of Babel.

Some architectures could weaken CoT monitorability, or remove the CoT altogether.
We've written a proposal for how companies could be transparent about no-CoT reasoning abilities, other monitorability evidence, and policies for preserving monitorability. redwoodresearch.org/blog/pro…

What’s funny is this is wayyy below semicap comsensus.

Microsoft reportedly plans to grow its data center capacity from ~12 GW today to 38+ GW by 2032. More than +26 GW added by one company!
Capacity centered on AI-specific chips rises from ~2 GW to ~13 GW, a 6x, yet still only a third of the planned fleet!
That remaining two-thirds also matters for AI: newer tools need more CPU capacity alongside GPUs. The infrastructure buildout extends well beyond accelerator clusters, with Microsoft already turning away some AI and cloud business because of capacity shortages.
Figures from Bloomberg’s reporting on internal plans.


Top.

Pokémon cards would be global currency during apocalypse, venture capitalist predicts trib.al/ls6ZaZL


Instinct, GrokBot, Muse.
I think we’re on the cusp of a new AI “scaling era.”
Era 1: Chat: AI becomes a useful conversational tool.
Era 2: Reasoning: Models spend more time working through harder problems as chain-of-thought reasoning is introduced.
Era 3: Local agentic: AI starts doing work on your behalf, primarily for white-collar “power users” willing to set up the tools.
Era 4: Seamless agentic: Agents operate in the cloud, behind a simple interface. Put more plainly… agents for normal people.
Giving agents serverless virtual machines & models adept at computer use, all in an intuitive UI... is a new unlock.
Probably good for another leg up in compute demand.
Possibly the most powerful moral choice in all of the Lord of The Rings comes from Galadriel at the end of The Fellowship of The Rings, when Frodo offers her the ring.
The crux of Tolkien’s moral philosophy compressed into one line: “I pass the test. I will diminish.”
—
“And now at last it comes. You will give me the Ring freely! In place of the Dark Lord you will set up a Queen. And I shall not be dark, but beautiful and terrible as the Morning and the Night! Fair as the Sea and the Sun and the Snow upon the Mountain! Dreadful as the Storm and the Lightning! Stronger than the foundations of the earth. All shall love me and despair!”
She lifted up her hand and from the ring that she wore there issued a great light that illuminated her alone and left all else dark. She stood before Frodo seeming now tall beyond measurement, and beautiful beyond enduring, terrible and worshipful.
Then she let her hand fall, and the light faded, and suddenly she laughed again, and lo! she was shrunken: a slender elf-woman, clad in simple white, whose gentle voice was soft and sad.
“I pass the test”, she said. “I will diminish, and go into the West and remain Galadriel.”

The lore behind this is if you're powerful enough you don't just attract the wraiths, you actually can command them, & use the Ring to bend others to your will.
The Ring has the effect it does on Hobbits because they are naturally of the hiding & running away sort, not the powerful, willful sort.
You know how Saruman was able to build & command a huge army of Orcs, humans, & half-Orc-half-humans? Well it's not because he was paying them, it was because his will was in their minds, pushing them to follow his commands. With the Ring, he would be the single greatest power in Middle-Earth, & be able to wrest control of Sauron's own armies from him & use them against him.
Even someone like Boromir, who was a great captain of Men, could potentially actually wield the Ring to this purpose. The armies of Gondor would fight not just because they wanted to save their homes, but because the will of Boromir, amplified by the Ring, drove them forward. And he could potentially bring others to his side by force of will as well.
But the Ring is more powerful than anyone who would use it against Sauron. It's actually more powerful than the part of his will/spirit that was left outside of it. If they used it against him, it would corrupt them. Sauron would win in the end, even if the other portion of his spirit was defeated, because the Ring would take over the wielder & effectively Sauron would rule through the body of that wielder, be it Boromir or Galadriel or even Gandalf.
This week provided a Rorschach test for your views of the AI Value chain.
Frontier Labs pulling away? Fable 5.1 and Astra w/ both having more advanced models internally.
Others catching up? Muse 1.3, Meta hyping Watermelon. Grok bot scaling. Gemini 3.8 efficient. Positive Gemini 4.0 rumors.
Catnip for both “labs pulling away” and “frontier getting more crowded” crowds.
People hoping that ACIE overtakes hyperscalers as a % of NVDA revenues.
Honestly, probably a bad outcome for $NVDA — because the hyperscalers have secured so much of the LPS supply, that if ACIE is a larger percent of revenue in 2028, it probably means the hyperscalers deployed ASICs at a faster rate than is currently in consensus numbers.

Depending on how you model the two-quarter lumpiness, Nvidia's $NVDA ACIE can conservatively overtake hyperscalers in 5-6 quarters at a 14% QoQ growth rate versus 10% QoQ growth rate for hyperscalers, or as soon as 2 quarters if the Q2 pace continues.
io-fund.com/ai-stocks/nvidia…

I’ve been hearing the analogy between $NVDA and $AAPL — the argument effectively is that Apple reshaped the supply chain in its own image and this served as a sustainable competitive advantage. And that $NVDA is currently doing the same. I think it’s an interesting concept.
However, the core of Apple’s moat is/was that switching costs are high for the users. iOS, Photos, App Store, iMessages, Settings, etc. The lock in is at the software layer, not the device layer. The supply chain is additive, but it isn’t the core of the moat.
Right now the largest consumers of compute are frontier labs and hyperscalers, who all have the resources to develop custom ASICs and build towards a future of heterogeneous compute.
$NVDA’s “extreme co-design” is effectively an argument that “we will persistently outrun everyone.” Higher fungibility and financiability are also nice to have — but neither of these provide the same degree of ecosystem lock-in as CUDA or iOS. Especially not in a world where your primary “users” are willing to throw inordinate amounts of capital and resources at eroding your economics. And particularly not in a world where the “shape” of future workloads is constantly changing to a degree that advantages experimentation in chip design.


