

Long-term investor. Fundamentals only. Thinking out loud on stocks, earnings & valuation. Checkout socials below Insta and YT👇 NFA. DYOR.
Toronto, Ontario
Joined December 2009
- Tweets1.6K
- Following382
- Followers1.1K
- Likes533


Pinned Tweet
Valuation is the only edge I trust.
$ELF +114.77%. $NOW +61.23%. Both called in May as significantly undervalued.
I show exactly how I value companies on YouTube + Instagram, for free.
New episodes Thursday to Sunday at 8pm ET. Link in bio.
Follow along and learn to value companies the way I do.


1
2
285
Sold $HD for +16.6%: The Thesis Broke
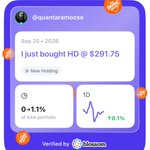
I sold my entire $HD position today at $341.36 for a gain of about 16.6%. It was a relatively small position, about 1% of my portfolio, and I started it a month ago.
I bought $HD because I thought it was undervalued, and I knew what would have to go wrong for me to sell. Today the data started showing exactly that.
Here's what I didn't like:
• The NAHB Housing Market Index data came in weak.
• Margins are shrinking while sales grow.
• They raised sales guidance but cut margin guidance.
• Full-year EPS guidance is below the Street.
• SRS is weaker. They cut SRS organic growth guidance to low single digits from mid single digits.
• Comp growth is coming from higher prices, not more customers.
• The CEO is stepping down.
Any one of these I could live with. Together they break my thesis, at least for now. Growth that comes from price while margins fall isn't the quality I was paying for.
I'm happy to take a gain, but the gain isn't the lesson. The lesson is that I made the call based on facts, not on how I felt about the company. It would have been easy to hold on and hope. But if the reason I bought is gone, the right move is to sell, not to look for new reasons to stay.
I might get back in. If the data improves and the price is undervalued again with a good margin of safety, I'll look at it again, probably after next quarter.
NFA. DYOR.
2
1
71
Trimming $ELF: Up 113%, Still Undervalued
I sold 50% of my $ELF position today. The gain was about 113% over the last 6 months.
I want to be clear about what this is and isn't. I'm not calling a top. I still believe $ELF is undervalued, and I think there is major upside left, which is why I kept the other half.
So why sell at all?
Because the best use of a dollar isn't always the stock that already worked. When a position runs this far, I ask a simple question. Is there somewhere else that same capital has a better risk to reward setup right now? Today the answer was yes.
I'm moving that cash into $NFLX and $BKNG . These are the opportunities where I see the more asymmetric payoff, meaning a downside I can live with against upside that is meaningfully bigger.
Trimming is also how I keep a concentrated portfolio honest. I don't want one winner quietly growing into a bigger part of my portfolio than my conviction justifies. Selling half locks in a real gain, and keeping half means I'm still in the trade if the valuation gap keeps closing.
I could be wrong on any of this. The market can ignore a good valuation for a long time, and $ELF can drop from here. But I'd rather size my positions deliberately than hold everything and hope.
What do you do when a winner runs: hold it all, trim, or sell?
NFA. DYOR.
67
Nvidia used to keep 16 cents of every sales dollar as profit. Now it keeps about 64. That's the number to watch.
Episode 20 of 25 of my Valuation Series. The rest of the series is on YouTube and Instagram, link below.
NFA. DYOR. $NVDA
150
$NVDA
How to project revenue growth without fooling yourself.
Copy Nvidia's latest growth forward for ten years and its sales would pass $300 trillion, about two and a half times the entire world economy. So start with what analysts expect, then fade growth each year toward the economy's pace.
Episode 17 of 25: how to project revenue growth for a DCF, with Nvidia.
What yearly growth rate would you use for Nvidia over the next 5 years?
Follow for Episode 18 tomorrow: what is a discount rate. All 25 episodes in order on YouTube: Moose | Stocks in 90 Sec. Every link: linktr.ee/quantaramoose and Follow on Instagram for more exclusive content!
Nvidia sales, StockAnalysis, Oct 2026; world economy, IMF, April 2026. Not financial advice.
#investing #stockmarket #valueinvesting #stocks
A lot of new investors on social media have never lived through a true sell-off. After 20 years in these markets, I’ve seen far worse. That’s why experience is the best teacher for emotional resilience.
2
147
$ELF Q2 FY27 (ended Sep 30 2026) great report in general and will continue to hold as I view this undervalued in my opinion. This is currently the 2nd biggest position in my portfolio.
Three Statement Grading:
• Income statement: A-. Exceptional top-line (51% with broad brand strength and pipeline), solid underlying GM expansion ex-refunds, but heavy reliance on one-time tariff benefit in H1 and marketing reinvestment timing creates H2 noise.
• Balance sheet: B. Strong liquidity and low leverage; contingent earnout liability rising with Rhode success is a real cash claim; goodwill + intangibles still > equity.
• Cash flow: B-. H1 OCF/FCF healthy and up sharply YoY, but Q2 standalone was soft on working capital (growth + pipeline). Conversion looks better on a trailing basis once WC normalizes.
Top 3 things to watch in Q3
1. Sustainability of organic/unit growth and international (esp. post-Rhode Europe pipeline normalization) vs the 7–10% H2 guide.
2. Gross margin trajectory as Rhode retail mix expands and tariff-refund benefit fades, plus marketing spend at the high end of 23–25%.
3. Working capital normalization (AR/inventory) and cash conversion; size/timing of further Rhode earnout payments.
2
2
256
One of these stocks looks almost three times more expensive than the other. It's actually the cheaper one.
Episode 11 of 25 of my Valuation Series. The rest of the series is on YouTube and Instagram, link below.
NFA. DYOR.
1
88
All 25 episodes, in order, on YouTube: youtube.com/playlist?list=PL…
Also on Instagram and TikTok: @quantaramoose

69
The S&P 500 is only about 3% off its record. So why does your portfolio feel so red? Here is my take
Follow @quantaramoose for a weekly market recap, plus lessons on how to value stocks, read earnings and think long term.
Not financial advice. For education only.
#stockmarket #investing #investingforbeginners #stockmarketnews #longterminvesting
1
3
112
$NOW getting lower than $110 again is a bargain! Still haven’t sold a single share! Think in years not months! Valuation is your edge, Short term price action is just noise!
1
129
$NOW
• Slight $NOW Q3 EPS miss ($1.00 vs $1.02) attributed by CFO to lower interest income and higher interest expense from Armis acquisition financing.
• Revenue already a clear beat at $4.106 B.
• Interest drag sat below operating income. Non-GAAP already excludes amortization, deal costs and related items.
• Without the Armis-related interest impact, EPS would have been at least in-line to a beat. Core business remained solid.
Remains undervalued $NOW
1
133
Nvidia's P/E is about 27. It's also about 18. Both are right, and the difference matters.
Episode 7 of 25 of my Valuation Series. The rest of the series is on YouTube and Instagram, link below.
NFA. DYOR. $NVDA
1
80
All 25 episodes, in order, on YouTube: youtube.com/playlist?list=PL…
Also on Instagram and TikTok: @quantaramoose
63
All 25 episodes, in order, on YouTube: youtube.com/playlist?list=PL…
Also on Instagram and TikTok: @quantaramoose
58
$EOSE was a favorite of financial Twitter/YouTube promoters when it was ~$6. Twelve months later it’s trading near $1.70. The people who treated those posts as research instead of entertainment just learned an expensive lesson in how not to value a company. I can teach you how.
1
1
266
Adobe trades at about 14 times earnings. For the last five years, it averaged about 35. Bargain, or trap?
Episode 5 of 25 of my Valuation Series. The rest of the series is on YouTube and Instagram, link below.
NFA. DYOR. $ADBE
2
1
156
All 25 episodes, in order, on YouTube: youtube.com/playlist?list=PL…
Also on Instagram and TikTok: @quantaramoose
72