

RWA Holder & Educator #RWA | Not financial advice | DM Always Open
Joined February 2025
- Tweets1K
- Following1.1K
- Followers2.3K
- Likes5.7K





📈 Tokenized stocks are where stablecoins were in 2020.
Tokenized stocks have reached $4.63B in market cap, the same level stablecoins passed in March 2020.
Since then, stablecoins have grown 64x to $297B.
Three issuers account for 81.4% of the tokenized stock market today:
→ Binance bStocks: $1.39B
→ Ondo: $1.32B
→ xStocks: $1.06B
The comparison is an analogy, not a forecast. Stablecoins had a very specific growth driver (crypto trading and dollar demand outside the US), and tokenized stocks may not follow the same path. But it’s a useful reminder of how early this market is, and how concentrated it already is.
📍 Source: Token Terminal

DTCC Joins the Tokenization Race – Ondo Loses Market Share
- The wave of asset tokenization continues to gain momentum with the official entry of the DTCC (Depository Trust & Clearing Corporation). However, while this expands the market, it also brings intensifying competition.
- A prime example is Ondo, which held over 61% of the tokenized equity market share in May 2024, but saw that figure drop to 28.4% by September.
- The arrival of the DTCC may accelerate the growth of the entire industry, yet it simultaneously challenges the competitive advantages currently held by existing projects.
➡️ Now is the time for investors to re-evaluate the true strengths of the RWA (Real-World Asset) projects they hold.

So, who stands to benefit, and who will face pressure from this race?
+ Chainlink: Well-positioned to expand its role in providing data, connectivity, and automation between traditional financial systems and blockchain.
+ Canton, Stellar: Benefit from being selected or integrated by the DTCC, opening doors to attract asset inflows and on-chain trading activity.
+ Aave, Morpho: Poised to expand their lending markets as tokenized equities and other assets are increasingly used as collateral.
+ Robinhood, Kraken, Binance: Have the opportunity to attract more users by leveraging their capacity to distribute and provide 24/7 trading services for tokenized assets.
Ondo, bStocks, xStocks: Face mounting competitive pressure regarding market share, liquidity, user base, and product distribution capabilities.
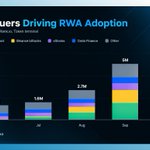
📈 6.4 million RWA holders.
Not market cap. People.
Jun: 1.4M
Jul: 1.6M
Aug: 2.7M
Sep: 5.0M
Oct: 6.4M (and the month isn’t over)
That’s 4.6x in four months.
Robinhood and Binance bStocks lead the named issuers, with xStocks and Ondo Finance behind them. These are products people can already reach inside apps they use every day.
Tokenization is getting distribution, not just assets.
📍 Source: CryptoRank, Token Terminal

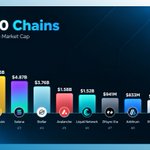
🏆 Top 10 Chains by RWA Active Market Cap (Oct 27, 2026)
🥇 Ethereum: $15.9B
🥈 BNB Chain: $6.26B
🥉 Solana: $4.87B
Stellar: $3.76B
Avalanche: $1.58B
Liquid Network: $1.52B
ZKsync Era: $941M
Arbitrum: $833M
XRP Ledger: $642M
Polygon: $489M
Ethereum still holds about 43% of the top-10 total, more than 2.5x BNB Chain in second place. The top four chains account for roughly 84% of the combined ~$36.8B.
Two names stand out: Stellar sits ahead of Avalanche by more than 2x, and Liquid Network (a Bitcoin sidechain) lands at #6, ahead of ZKsync Era, Arbitrum and XRP Ledger.

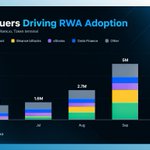
📈 Top Issuers Driving RWA Adoption
RWA holders by month (as of Oct 26, 2026):
Jun: 1.4M
Jul: 1.6M
Aug: 2.7M
Sep: 5.0M
Oct: 6.4M
That’s about 4.6x growth in just four months, and the pace is accelerating: +0.2M from Jun to Jul, then +1.1M, +2.3M, and +1.4M so far in October (the month isn’t over yet).
Who’s driving it? The chart tracks Robinhood, Binance bStocks, xStocks, and Ondo Finance. Robinhood and Binance bStocks barely registered in June and July, yet together they now make up the biggest slices of the stack. In other words, the growth is coming from consumer platforms bringing tokenized assets to their existing users, not from crypto-native products.
📍 Source: CryptoRank, Token Terminal

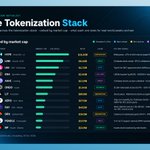
🧱 The Tokenization Stack: 12 tokens across the stack, ranked by market cap
What each one does for real-world assets onchain:
Derivatives
→ HYPE ($16.80B): RWA perps are ~27% of 30d volume (peak 51% in July)
→ LIT ($805M): stock perps, with Robinhood stocks accepted as collateral
→ DRV ($363M): options on tokenized gold (XAUT)
Infra
→ LINK ($8.68B): Coinbase stock oracle, DTCC collateral chain (Q4 ‘26)
Spot venues
→ UNI ($4.22B): top fit for SEC-approved stock AMM pools
→ AERO ($575M): day-one liquidity for Coinbase stocks, Base’s lead AMM
→ RAY ($482M): main xStocks venue (~$2.3B in Q3), Solana’s lead AMM
Dollars / Credit
→ ENA ($2.60B): USDtb backed by BUIDL, $250M in tokenized credit
→ AAVE ($2.09B): Coinbase stocks as loan collateral, Horizon at ~$390M
Issuance
→ ONDO ($1.94B): $1.3B+ in tokenized stocks and ETFs, ~26% market share (Oct)
→ BP ($249M): issues stocks backed by real shares
Yield
→ PENDLE ($337M): 9 of its 11 largest markets are RWA-backed (H1 ‘26)
Combined, the 12 tokens are worth about $38.4B, and the top three (HYPE, LINK, UNI) make up roughly 75% of that.
The pattern is the interesting part: the biggest market caps sit in derivatives and infrastructure, not in issuance. Tokenization is creating value across the whole stack, but so far the market rewards the layers that trade and route RWAs more than the ones that issue them.


It comes as no surprise that this is the fastest-growing sector this year.
RWA perpetuals - which allow for long and short positions on stocks, gold, and stock indices - have seen their total open interest nearly triple since June, reaching a peak of $20 billion.
This $20 billion figure includes leverage; much like crypto perpetuals, users trade based solely on price movements without directly owning the underlying assets.
• Centralized exchanges (CEXs) account for 71%, leading in the categories of stocks, gold, and silver.
• Decentralized exchanges (DEXs) make up the remaining 29%, leading in the stock market segment.

📊 Euro Stablecoin Market Cap Growth by Chain (Past 7 Days)
🟢 Growth
🥇 Solana: +$22.0M
🥈 Arbitrum One: +$643.5K
🥉 Arc: +$14.2K
🔴 Decline
BNB Chain: -$11.3K
Celo: -$31.4K
Stellar: -$65.2K
XRP Ledger: -$80.7K
Avalanche: -$155.8K
Algorand: -$227.5K
Polygon: -$264.9K
Solana accounts for about 97% of all euro stablecoin growth this week, roughly 34x more than #2 Arbitrum One. Seven of the ten chains shrank, but the losses were small, totaling under $0.9M.
The takeaway: euro stablecoin demand is concentrating on one chain, while older euro-stablecoin venues like Polygon, Algorand and Avalanche are slowly bleeding supply.
📍 Source: Token Terminal


💥Chainlink has signed a strategic partnership agreement with LG CNS - the technology arm of the LG Group - to build infrastructure for South Korea’s digital asset market, which is valued at approximately $68 billion.
This agreement builds upon a prior memorandum of understanding (MOU). Chainlink will integrate its full suite of cross-chain tools, data, and orchestration capabilities into LG CNS’s "Digital Asset Platform Solution," targeting financial institutions in South Korea. Key focus areas include won-pegged stablecoins, asset tokenization, and bridging traditional finance with blockchain technology. The two parties will also collaborate on establishing technical standards for South Korea’s digital asset economy.
Why LG CNS is significant:
→ It serves as the primary contractor for "Project Hangang," an initiative by the Bank of Korea focused on digital currency (the initial phase involves approximately 80,000 users across seven banks).
→ It is part of the LG Group, a conglomerate with roughly 186 trillion won in assets and 63 member companies.
Market Context: South Korea has over 11 million eligible crypto users, and the country is currently preparing regulatory frameworks for won-pegged stablecoins.
A key distinction: The agreement is limited to LG CNS’s commercial solutions; it has not been confirmed whether Chainlink will be directly implemented within the infrastructure of Project Hangang or the Bank of Korea’s systems. While LG CNS is a contractor for Project Hangang, these represent two separate areas of engagement.
📍 Sources: Chainlink, LG CNS, The Block

🃏 Onchain TCG (trading card games) has proven product-market fit, but it hasn't proven that it serves collectors.
According to Nick Research, this is currently primarily an onchain wagering market backed by physical cards.
The scale already shows real demand:
→ Collector Crypt: $1.6B+ cumulative volume
→ Phygitals: $250M+
→ Renaiss: 260K+ users
→ Jupiter TCG Gacha: $9M volume in 5 days
The infrastructure also solves real problems: ownership can be tracked, pack results can be verified, vault inventory is auditable, and users can exit through instant buybacks. That's a clear upgrade from trusting a single shop owner.
But user behavior tells a different story. Bitquery tracked Collector Crypt Gacha from Dec 2025 to July 2026:
→ $622.6M wagered, 17,544 wallets participated
→ Only 22% of players recovered more than they spent
→ The median player lost $50
→ 68% immediately sold their cards back for USDC
→ Only 5.9% kept the cards
If nearly 7 in 10 users convert the card back into USDC right away, collecting is clearly not the main activity.
The economics confirm it. A $50 Elite pack showed a 110.7% expected value, but the instant buyback only pays 85% of the card's value. The buyback solves liquidity, but the discount also creates the house edge, bringing the effective expected return to roughly 94.2%.
An underappreciated risk: custody has not become trustless. The NFT may be onchain, but the physical card still sits inside a centralized vault. If that vault suffers fraud, insolvency, theft, or poor management, the ownership record cannot recover the asset.
The author is bullish on the infrastructure but cautious about the current product model. Onchain TCG makes an existing speculative market more transparent, liquid, and efficient, but it doesn't turn speculation into collecting. It's not yet a collector economy until retention is driven by card ownership rather than immediate USDC exits.

🚨 BREAKING: J.P. Morgan Asset Management has expanded two of its tokenized money market funds - MONY and JLTXX - to the Solana blockchain (October 22, 2026). Both funds were previously available on Ethereum.
The two products differ in their structure:
MONY: A private fund operating under Rule 506(c), launched in December 2025.
JLTXX: A U.S.-registered government money market fund, designed specifically to serve stablecoin issuers in accordance with the GENIUS Act.
Eligible U.S. investors can handle subscriptions, redemptions, and token balance management through a single platform: Morgan Money.
Paul Przybylski of J.P. Morgan Asset Management stated: “Our clients operate across multiple networks, and their liquidity should be able to do the same.”
JLTXX directly addresses the challenge of stablecoin reserves. Stablecoin issuers operating on Solana can now hold their reserves in a J.P. Morgan fund directly on the same blockchain they use, eliminating the need to move assets between different networks.

📊 Tokenized stocks: market cap by chain
Total: $4.4B, up 886.1% over the period shown
🥇 BNB Chain: $1.6B
🥈 Solana: $1.1B
🥉 Ethereum: $841.3M
X Layer: $286.0M
Avalanche: $239.7M
Arbitrum One: $194.5M
Robinhood Chain: $148.6M
Base: $48.3M
Ink: $21.5M
Stellar: $17.1M
BNB Chain now leads with about 36% of the market, and the top three chains hold roughly 80% of the total.
The big shift is Ethereum. It dominated at the start of the year, but BNB Chain barely registered back then and has since climbed to #1, with Solana also passing Ethereum.
Also notable: X Layer in 4th, ahead of Avalanche, Arbitrum and Robinhood Chain.

The $39.3B RWA market figure is notable, but the more interesting signal is the $237.5M in disclosed venture funding across 26 rounds so far in 2026.
Superstate’s $82.5M Series B alone accounts for roughly 35% of that total, which highlights where capital is actually concentrating - in the infrastructure layer (issuance systems, ownership records, and distribution rails) rather than pure product plays.
This distinction matters. Venture funding builds the companies that operate the market, while actual AUM is determined separately by investor subscriptions into the products.
Right now, most tokenized assets still face limited usable collateral status on-chain, so the real test over the next 12–18 months will be whether this infrastructure capital translates into sticky, scalable demand or remains mostly narrative-driven.
The research from CryptoRank is a useful snapshot of where the money is flowing.


📊 Tokenized stocks tracking MSTR and STRC: market cap by chain
Total: $473.4M
🥇 Ethereum: $210.9M
🥈 BNB Chain: $115.7M
🥉 Solana: $78.5M
X Layer: $40.4M
Arbitrum One: $17.1M
Robinhood Chain: $6.8M
Base: $2.1M
Ink: $1.7M
Polygon: $195.9K
Tron: $82.7K
Ethereum holds about 45% of the total, and the top three chains (Ethereum, BNB Chain, Solana) account for roughly 86%.
The +25,158,724% growth figure is just what happens when you start from near zero in 2024, so the shape of the curve matters more than the percentage: almost all of this value was added in 2026.
Also worth noting: X Layer at #4, ahead of Arbitrum, Robinhood Chain and Base.
📍 Source: Token Terminal

🗺️ Canton Network ecosystem map: 10 categories, one institution-first chain.
🏛️ Institutional rails: DTCC, Broadridge, HSBC Orion, Tradeweb
🔄 Spot/exchanges: Temple, Cantex, Kairo, Helvet Swap, OneSwap
📈 Derivatives: Titan, Eiden, Raven Market
💰 Lending/credit: ACME, Alpend, Cashen, Realworld, Edel
💵 Stablecoins/payments: USDCx, Brale, HIFI, Minted, Send
👛 Wallets: Loop, Bron, Console
🤖 Agentic execution: Silvana
🛠️ EVM/builder access: Zenith (public testnet)
Plus SocialFi (The Hub) and yield/private markets (AllDeFi, Hecta).
What stands out is the first row. Most ecosystem maps lead with DeFi apps, but Canton’s starts with market infrastructure names like DTCC, Broadridge and Tradeweb. The thesis is to build for regulated institutions first, then layer DeFi on top.
