

News, analysis, research and events on pricing, structuring and market infrastructure developments across all OTC and listed derivatives asset classes.
Joined February 2009
- Tweets4.6K
- Following22
- Followers2.2K
- Likes13




Risk.Net Markets retweeted

Some interesting data out from the BIS on credit default swaps. Notionals for uncleared contracts referencing debt with no credit rating rose 21% in the first half of last year.
risk.net/risk-quantum/795568…

Risk.Net Markets retweeted

So it turns out that even crypto firms do better when they run with proper documentation. Who knew? risk.net/derivatives/7955141…

Risk.Net Markets retweeted

Top banks’ trading books dwindled in 2018
risk.net/risk-quantum/720431…
Risk.Net Markets retweeted
Required client margin held by Morgan Stanley’s #swaps clearing unit jumped up by $4.8 billion in Q3 – the most of the 17 reporting US futures commission merchants.
risk.net/risk-quantum/716232… $MS
Risk.Net Markets retweeted
Traders piled into exchange-traded interest rate #derivatives in Q2, sending open interest up 14%. Most of this growth was in short-term #options. Open interest in these contracts jumped $12.7trn to $79.7 trillion notional in the three months to end-June.
risk.net/risk-quantum/702472…
Risk.Net Markets retweeted

The 30th anniversary edition of the @CentralBanking_ journal is now available online and in the app via the @AppStore and @GooglePlay centralbanking.com/central-b…

Risk.Net Markets retweeted
US bank holding companies and foreign intermediate holding companies over $100 billion in size held $1.2 trillion of borrowed fed funds and cash obtained through #repo as of end-June.
risk.net/risk-quantum/701179…
Risk.Net Markets retweeted
NEW: #Cleared swaps held by the eight systemically important US banks increased 5% in notional terms in Q2, while #bilateral notionals edged down 1%.
risk.net/risk-quantum/693087… #derivatives
Risk.Net Markets retweeted
NEW: JP Morgan and Bank of America saw the risk density of their OTC #derivatives, repo and margin loan portfolios inch up over the first half of the year, as those for Citi and Wells Fargo edged lower.
risk.net/risk-quantum/691268… $JPM $BAC $C $WFC
Risk.Net Markets retweeted
NEW: OTC #derivatives portfolios expanded at big UK #banks and shrank at the largest continental European firms in 2018.
Data from the systemic risk reports of 36 EU lenders shows aggregate notional exposure to OTC #swaps increased by 3% to €221.7trn.
risk.net/risk-quantum/690346…
Risk.Net Markets retweeted

Free to read: Deep hedging feels like the start of something big in quantitative finance on.risk.net/cMFp30pjjao #Quants #MachineLearning
Risk.Net Markets retweeted
NEW: #HSBC’s derivatives book expanded 15% in the first six months of 2019, with interest rate swaps leading the charge. Gross derivatives notionals stood at $39trn, up $4.9trn compared with end-December. Notionals increased 25% YoY, or $7.8trn.
risk.net/risk-quantum/688277…
Risk.Net Markets retweeted
Greeks tragedy – How deep hedging using neural networks could spell the end of the Black-Scholes era on.risk.net/z3k730piN3a #AI #Quants
Risk.Net Markets retweeted
Interested in speaking at our upcoming events?
Fill in the survey and let us know which topics you want to cover: bit.ly/2ZsjxfS
#AsiaRiskTraining #APAC #RiskTraining

Risk.Net Markets retweeted
✏📖From #ALM to #MachineLearning, Risk Training is offering more courses across Asia than ever before in the second half of this year. Learn more about each event here: training.risk.net/public-cou…

Risk.Net Markets retweeted
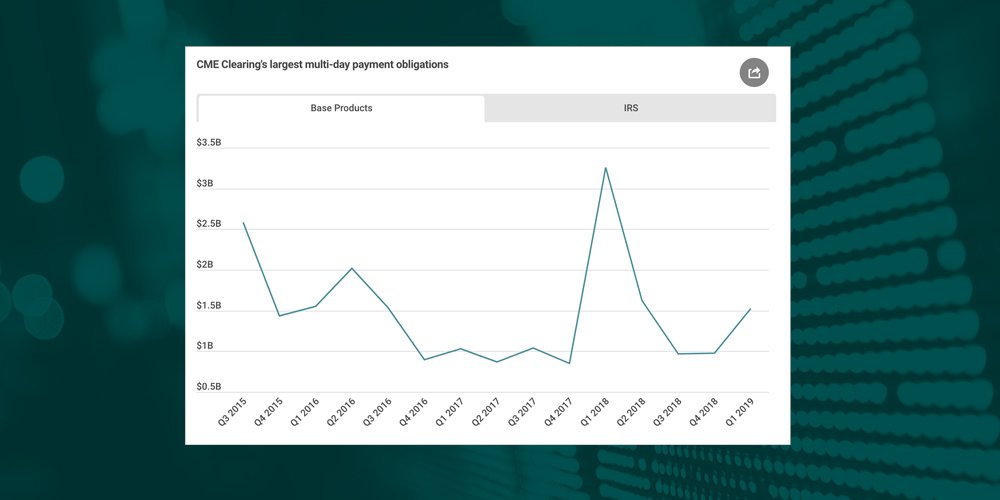
The Big Figure: CME Clearing’s futures and options clearing service issued a variation margin payment call of $1.5 billion to one member in Q1 this year on.risk.net/MVQh30p6ZUt #CME #options
Risk.Net Markets retweeted
NEW: #Eurozone hedge funds saw #derivatives asset holdings spike by almost 28% to €91.9 billion in Q1. It’s the largest amount they have reported since August 2016, when derivatives asset values hit €95.6 billion.
risk.net/risk-quantum/680799…
Risk.Net Markets retweeted
Our current most-read article tells how a popular quant model could help replace forward-looking Libor on.risk.net/CGiJ30p5Kkt #Libor #Quants