

Head of Aussie Equities & Portfolio Manager of TAMIM All Cap/Small Cap Funds. 21 yrs experience in ASX small caps. Investing is my passion. Views are my own.
Sydney, New South Wales
Joined February 2018
- Tweets31.4K
- Following823
- Followers11.7K
- Likes55.8K




Ron Shamgar retweeted

Had a look at Pureprofile $PPL after its record quarter.
DYOR - Just started checking it out.
Revenue $18.3m (+14%), earnings $2.4m (+27%), & platform now about half of sales. Some good, some things to watch. Not sure it’s a 10-bagger, but the numbers are interesting. Full write-up on my Substack
8020invest.substack.com/p/sp…
👇 Not financial advice. I don’t hold PPL.


Ron Shamgar retweeted
Elon’s tweet on neoclouds got me thinking about Megaport. @elonmusk $MP1.ax
He says debt markets have almost shut for anyone who doesn’t have real revenue outside AI data centres. SpaceX got US$40b for GPUs, but it’s investment grade & has Starlink behind it. His view is most of the 200+ neoclouds won’t make it.
Megaport is a neocloud now. It bought Latitude.sh, which rents out GPUs. I hold it, so I went back through the numbers.
The good bits first. It’s signed about $2.3b of contracts since April. Customers sign take-or-pay contracts, so they pay whether they use the capacity or not. On the September deals they’re paying $322.6m upfront. One customer alone is paying $281.5m. Power & space are already secured, which is exactly what just tripped up NextDC. And network recurring revenue is still growing, up 29% in constant currency.
Now the bits that make me pause.
Spending this year is $1.78b to $1.88b. Revenue guidance is $720m to $810m. After all that, spare funding is about $362m. The $845m bank loan is signed, but more of it only opens up as revenue targets are hit.
2 of the 3 September customers are US tech companies backed by investors. My guess is they’re AI businesses that need outside money too. A take-or-pay contract is only as good as the customer paying it.
There’s also $360m going on GPUs with no contract behind them yet.
Then on Sunday the AFR’s Street Talk said banks have been sounding out investors for a raise of $700m to $1b. Megaport hasn’t confirmed anything & the report says there’s no firm plan. It was only 4 months ago they raised $827m at $14.30. In September they said they were fully funded. So if a raise comes, I’d want to know what it’s for. New contracts? Acquisitions? A buffer?
Someone’s clearly keen. Pinnacle’s managers went from 6.18% to 8.22%. On 21 October, the day NextDC fell 42%, they bought 3.1m shares for $49.2m. That’s about $15.91 a share, which is pretty much where it is today at around $16. Director Jon Gidney also bought his first shares on 1 October, about $100k at $20.06.
So is Megaport one of the few neoclouds that gets through? Maybe. It looks better placed than many, with prepaid contracts & power already sorted. But it’s spending a lot, it may need more money, & some of its customers are in the same boat Elon’s talking about. I don’t think it’s settled yet.
I’m holding for now & waiting to see the next update & any raise terms before I decide whether to add or trim.

Ron Shamgar retweeted

This part of October is historically one of the worst of the year.
The good news is late October lows are quite normal and with sentiment getting extreme, we could be looking at another late October buying period.

Ron Shamgar retweeted
The shareholders of this high growth and profitable medical device company have endured more pain last few years than the patients it treats !!
But that’s about to change 👀
We think there’s a potential 6x bagger for the picking 💰💰💰
Read more here 👇👇👇
tamim.com.au/stock-insight/a…

Ron Shamgar retweeted

Looking ahead to $ZIP’s 1Q27 update tomorrow.
Expecting another positive quarter, although tough comps (US TTV +50% in 1Q26) may push a potential FY27 TTV guidance upgrade into Q2 or Q3.
Biggest watch for us will be bad debts and whether credit quality remains resilient.
No doubt it will be a volatile day. 🤞
Ron Shamgar retweeted

The initial response to this article has been incredible.
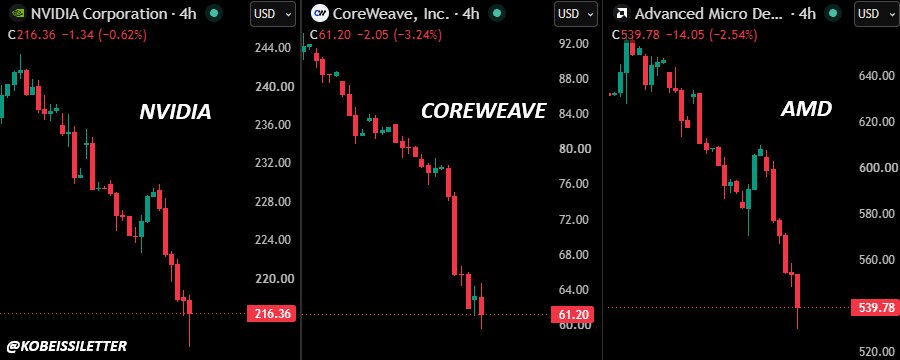
The S&P 500 is now <1% away from a record high but 206 of its components are down over -30%.
Never in history has this happened before.
It's the "Bear-Bull Market Paradox." Bookmark this.

Ron Shamgar retweeted

"Baby Bunting’s AGM update largely ticked the financial performance boxes against a challenging consumer environment, but is the stock’s valuation disconnected from its growth outlook?"
A staunch favourite but so unloved #BabyBunting
@FNArena
The Disconnect In Baby Bunting's De-Rating fnarena.com/2026/10/16/the-d…

Ron Shamgar retweeted
BREAKING: Tesla’s new Roadster: 0–60 in under a second.
It also flies, does barrel rolls, and drives upside down.
xitter.cf/KanekoaTheGreat/status…


Ron Shamgar retweeted

The Ode to the Vanished Surcharge😂😂
“No surcharge!” cried the grateful nation, “A win for every generation!” The RBA had drawn a line: the fee must vanish, by design.
Then up spoke Rob from the ATO, who did the sums and muttered, “No. Two hundred million, every year? I’d rather cards just disappear.”
From December, pay your BAS by BPAY, debit, or bank deposit. Reward points? A cashflow float? The Tax Office has cut your throat.
Small business howled. The ministers flapped. One said wait, one said adapt. Angus Taylor asked, with perfect timing, “Where’s Jimmy? Is the Treasurer hiding?”
And lo, this Friday, Jim appeared, the Charmers of the fiscal sphere, and said, “Relax, we’ll foot the fee. The taxpayer can pay for me.”
So surcharges are banned at the till, except, it seems, on the nation’s bill. You cannot charge them at the shop. You can, however, charge the lot.
The card still works. The points still land. The merchant fee is now a grant. And somewhere in a Treasury drawer a surcharge lives forever more. @JEChalmers @AlboMP

Another cleanup on aisle 2
theguardian.com/australia-ne…

Ron Shamgar retweeted
Spending on AI infrastructure is projected to average 3.6% of US GDP in the coming years.
That would represent a higher share of the economy than the investment in Canals (1836-41), Railroads (1870-90) and Electrification (1905-25) ... Combined.

Ron Shamgar retweeted
$MP1.ax
Megaport is up 8% to $22 today. A lot of people are linking it to the Firmus float. The link is real, & closer than most think.
3 connections:
1. Firmus is a partner. In Oct '25 it picked Megaport as a key network partner for its Australian AI factories.
2. There's a board link. Firmus chair Grant Dempsey left Megaport's board in May to focus on Firmus. New director Jon Gidney took his place.
3. Both rent out AI computing power. Megaport does it through Latitude.sh, which it bought in 2025.
Megaport's own news is strong too. On Tuesday it announced nearly $1b of new AI deals. It lifted its FY27 revenue guide to $720m–$810m. Recurring revenue from AI computing is up 90% since June. Total yearly recurring revenue is now over $500m.
The director trades are worth a look. The CEO sold $6.9m of shares on 30 Sep. That was to cover tax on his share awards, & the company says more sales may follow. New director Jon Gidney bought $100k in his super fund on 1 Oct, after the upgrade. I always like a director buying in their super fund. It's long-term money.
Firmus is pricing at $11 a share, valuing it at $43.7b. Bids open Tuesday & it lists on 23 Oct. Fundies are split. Some call it the BHP of AI. Others say they'd short it.
What it means for Megaport:
If Firmus grows, more traffic runs on Megaport's network. That part wins either way.
The bear case on Firmus also applies to Megaport's computing side. Big tech may build its own chips & hand the capacity back.
Watch next week. Funds raising cash for a $7b float may sell other ASX tech names.
At $22, Megaport is worth about $5.3b. That's still a fraction of Firmus, with a real track record behind it.
I hold MP1. Not financial advice. Do your own research. Just my notes.


Ron Shamgar retweeted
BREAKING: US August PCE inflation, the Fed's preferred inflation metric, falls to 3.4%, below expectations of 3.7%.
Core PCE inflation fell to 3.0%, below expectations of 3.3%.
July headline and core PCE inflation were also revised down by 30 basis points each.
October rate hike odds are falling again.
Ron Shamgar retweeted

$SCX - 22% since entry. Sovereign AI infrastructure! Australia Government needs to control our data, does SCX.ai come into play? Time will tell.


Ron Shamgar retweeted
I've been reviewing @alcidion $ALC.ax for a while. Today's NHS contract sent me back to the numbers, so I wrote it up.
Alcidion is a Melbourne health software company. Its screens replace ward whiteboards, so hospitals can see beds, discharges & delays in real time.
The Alfred uses Alcidion's screens & a Monash University study there found patients went home sooner, with average stays down 12%.
FY26 in brief:
Revenue $51.6m, up 27%
Contracted recurring revenue $38.3m
Operating earnings $6.2m
Cash $20.6m, no debt
Wages up just 3%
Management guided conservatively & beat all 3 of its targets.
Today it signed Northern Care Alliance in north-west England. That's $7.5m over 3 years, with about $4.5m expected this financial year.
$44.9m of FY27 revenue was already contracted at 30 June. FY27 guidance is to beat FY26.
I rate CEO Kate Quirke. She under-promises & delivers.
In the piece I also look at:
Who else is in the market (Epic, Oracle, Nervecentre & more)
Whether any competitors are listed
Why customers tend to stay for years
Whether hospitals could build their own software with AI
What a 10-bagger would actually need from 11c
It's a profitable, debt-free business with loyal customers. A 10-bagger would need a lot to go right, but it stays on my watchlist.
I don't hold $ALC. Not financial advice, just my own research.
Full piece here: 8020invest.substack.com/p/al…