

Ex Co-Head of Macro at Bridgewater (joined in 1998, left 2023) Cyclical macro. Very interested in random micro. Investor. Brazilian-ish. Introvert/lurker.
Ridgefield, CT
Joined November 2014
- Tweets172
- Following926
- Followers9.9K
- Likes215





Bad trades. 6 years ago, I bet my 10-year-old nephew a Tesla if $TSLA traded higher on his 16th birthday. I was spiritually right but lost handily. My sister vetoed the payout, so we parlayed the loss: if SpaceX is up when he turns 22, I’ll buy him a used Russian rocket.
1
31
3,728
Jason Rotenberg retweeted

I guess the question is. If your goal was to durably bring inflation back to target and you were able to use all of the Fed tools with no restraint or oversight how would you accomplish your goal.
Here's what I would do.
I would sell 50bn of Treasuries and 50BN of MBS monthly and use the proceeds to purchase bills. If the Treasury cut 10's -30's issuance or increased buybacks I would increase my selling bond for bond. My goal would be to crush the asset market and increase the cost of corporate funding.
I would maintain short rates at about current levels because they are less effective to achieve my goal.
Updated deep-dive on US inflation. Wage growth has been somewhat tame, but that is probably a lagging measure of the recent cyclical upswing. Inflation looks more of a problem now late last year. 3% inflation isn’t an emergency, but a monetary diet is long overdue. Policy is too easy, contributing to an acceleration that makes it more likely that inflation stays sticky or rises from here.
Core services: Demand has increased, employment has accelerated, and businesses have successfully passed price increases to consumers. The primary disinflationary factor is the surprising upside in AI capabilities, but it is far from clear that significant disinflationary effects are imminent.
Core goods: While recent inceases are partly a function of last year’s tariff increases, more importantly, the inflation dynamics of hyper-globalization were, at a minimum, undergoing a reversal. China’s industrial policy push, is if anything likely to consolidate a developed world backlash. These secular forces remain unchanged; in fact, global supply chains have experienced, and continue to experience, another major disruption, further underscoring the need to rethink trade routes and supply chains. This points to an inflationary environment.
Housing: It is currently at 3.2%, representing the sole area that has seen some cooling. On the rental side, higher wage growth compared to the COVID period and less negative supply-demand dynamics should support solid increases. We are a bit further along in the rental supply rebalancing. Home prices, though not part of measured inflation, are also buoyed by rising wages, increasing wealth (supporting down payments), and mortgage rates that have remained relatively stable over the past five years. Affordability is a constraint, and home prices may face pressure if rates rise and equity prices fall. But that is not where we are. For now the direction of travel looks to be for stabilization.

Jason Rotenberg retweeted

Darren McLean reckons if you'd described today's market to him three years ago, he'd have fallen off his chair begging you to fast-forward him to it.
Development-stage miners, he says, are the cheapest he's seen in his entire career.
He joins us to explain why so many projects suddenly "just work on paper" and why he thinks the real money is in a construction cycle, not the M&A everyone's waiting for.
YT → youtu.be/QKEaeG454dA
Spotify → open.spotify.com/episode/67d…
Focus → focus.marketech.com.au/#/

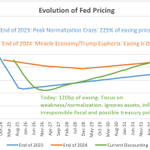
A synthesis (my read of macro conditions, market pricing, macro market views), then a lot of charts with hopefully fewer words.
Growth is strong (upper end of the COVID expansion) and likely to remain strong. A very strong wealth effect is the main driver, which should continue to push savings rates lower. Rates that have been range-bound for five years are not big drivers. Strong CapEx from the AI build continues to add to growth. Weaker immigration lowers potential growth but not the trajectory of growth versus potential. The energy shock so far is modest (maybe a third as big as the support from rising equity prices). The “K”-shaped economy may have political effects, but a dollar of spending is a dollar of spending, so it doesn’t matter all that much for cyclical macro or what the Fed should do.
Unemployment is low and likely headed lower. Mostly a function of the above. The acceleration in growth after the “uncertainty” shock of last year and a fast equity market rebound has led to the pick-up in employment growth in recent months. The swing from strong illegal immigration to a fascist crackdown leading to an exodus means that the supply of workers is flat. So rising demand into weak supply results in falling unemployment. AI adoption, productivity gains, and the likely economic impairment of the bottom third of white-collar workers are slower-moving (i.e., it will likely happen over 0.5–3 years versus 0–3 months).
Underlying inflation has stabilized somewhat above target; it is more likely to rise than fall. Inflation has been more subdued than I would have expected. Wage inflation has continued to moderate, but I suspect that cyclical strength will pause or reverse that slowdown as it usually lags growth/employment. AI adoption may lead to some hiring at first (I am certainly getting a lot more out of a small team using those tools, and others will feel the same). Goods inflation is moderate and has the flow-through from tariffs fading but will experience another negative shock from energy and supply disruptions. Chinese exported deflation remains strong. Rent disinflation will reverse due to a lack of supply of apartments. Ultimately, rising incomes and wealth support home prices and rents. Five years of inflation overshoot and new shocks have changed inflation psychology (prices and wages can be adjusted), and I think the risks are still to the upside. A full revisit of inflation dynamics is overdue and is for another day. I may learn that I am missing something on why it has been more subdued than I expected.

Full piece here (ask to Subscribe for free). Including current macro views. 60+ long-form articles on macro and micro over the last 2 years. jasonrotenberg.substack.com/…
2
10
3,437
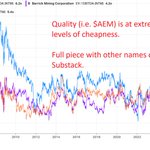
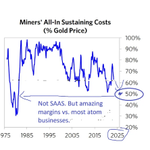
The best-in-class, safest, most anti-fragile gold mining names have never been of higher quality. Unlike most of their history, production profiles are very diversified, margins are high, debt is negligible or negative, and no exposure to riskier jurisdictions is needed. You can buy the companies with the strongest management teams and impressive track records. In a few cases, they have had very minor operational hiccups recently, adding to the opportunity. But nothing on the quality side appears broken. They also have solid organic growth prospects and the ability to expand through M&A by rolling up the sector (smaller names are even cheaper).
These companies are also at extreme levels of cheapness. When I say cheap, I mean the cheapness at current gold prices - I am not making a gold price forecast or making a case for gold. These stocks are low beta and produce something that isn’t cyclical. They don’t add a lot of risk to most long portfolios.

Full piece here (ask to Subscribe for free). Micro pieces like this plus macro. jasonrotenberg.substack.com/…
2
1,514
Jason Rotenberg retweeted

Lots of (downward) volatility in share prices.
Longer term freight forwards (FFA's) meanwhile...
Smells like opportunity $CMBT $BULK
Calender 2026 Capesize contract at @braemarscreen below.

See my bio for link to charts and full video of a broader discussion of how I am reading the charts.
1
2
2,879
Jason Rotenberg retweeted

I intend to be a shipping investor as long as I invest.. as it is underfollowed and hence easier to make great returns. Which VIE consistently does.
I intend to be a VIE member as long as I invest as well.
There is no better place than VIE when it comes to learning about shipping. But there is also an interesting more general chat with lots of investors I have great respect for, and learn from.
Very much recommended if you have the portfolio size to afford it.

Exciting times in #shipping:
-Ripping #tanker rates 🚀
-Phenomenal #drybulk setup 🧐
-Port fees eliminated 🎉
-US/China deal soon 🤔
-Record value discount vs. $SPY ✅
Try our updated @Shipping_VIE #research platform for just $199 + 20% off 1st year:
seekingalpha.com/affiliate_l…
