

📈 Institutional Activity Scanner for Indian Stocks 🧠 Data-Driven Research & Smart Money Insights 🚀 Helping Traders Make Better Decisions
SMF DATA DETAILS 👉
Joined February 2025
- Tweets5.1K
- Following122
- Followers7.9K
- Likes6.3K




Pinned Tweet
#GMBREW
Smart Money Footprints don’t lie 📊
After this signal, the move was 🔥 I track real data-driven footprints that show where Smart Money is flowing, and it works.
If you want To Know such stocks before Repost + comment “SMF,” I’ll DM you the full details.
#smartmoney #smartmoneyfootprint #smfdata #smf #StockMarket #gmbrew #GMBreweries

Jio listed at ₹1,358
21% premium over the issue price.
Most people are asking, “Should I buy now?”
Better question:
After the listing hype fades, are institutions still holding or booking profit?
What’s your move?
A) Buy on dips
B) Wait and watch
C) Stay out
Comment A, B or C and why?
#jioipolisting #JioIPO
A fund manager once told me something I never forgot.
He said most retail traders don’t lose because they pick bad stocks.
They lose because they never decide in advance when they are wrong.
He showed me two portfolios.
Both had the same stocks.
Both entered around the same time.
One was up 180% in three years.
The other was barely above break-even.
The difference was not the stocks.
It was one decision rule.
What was the rule?
↓↓↓↓↓
The winning portfolio had a clear exit rule based on ownership data.
If institutional holding stopped rising for two consecutive quarters, or if delivery percentage collapsed on up-moves, he reduced the position even if the chart still looked strong.
The other portfolio had no such rule.
The investor held everything until the stock looked “weak” on the chart, by which time institutions had already started distributing.
By the time the price confirmed the exit, a large part of the gain was gone.
Most traders wait for the chart to tell them the story is over.
Smart Money often leaves before the chart confirms it.
That single difference exiting when the data changes, not when the price looks bad decided the result.
You don’t need to predict the top.
You need a rule that tells you when the reason to hold is no longer valid.
Have you ever held a stock long after institutions started selling, just because the chart had not broken yet?
Comment below.
#SmartMoney #SMFdata #IndianStockMarket
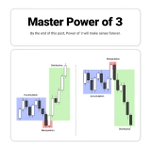
Power of Three
1. Accumulation
2. Manipulation
3. Distribution
#StockMarket #StockMarketIndia #stockmarketcrash


His father died when he was nineteen.
He had no degree.
No connections.
No starting capital.
He started working as a security guard in a Mumbai office park.
Twelve-hour shifts.
₹12,000 a month.
One day he noticed something.
The office workers were always stressed about money — but the ones who owned shares in the company they worked for were calm.
Not rich. Calm.
He asked one of them how to start.
The man laughed and said, “You can’t. You need lakhs.”
That sentence stayed with him for three years.
↓↓↓↓↓
He saved every rupee.
Skipped weddings.
Skipped movies.
Lived on one meal a day for months.
By 2014 he had ₹1.2 lakh.
He didn’t buy a bike.
He didn’t buy gold.
He opened a demat account and bought one stock — a boring PSU that nobody talked about.
He put in ₹40,000.
His friends called him stupid.
His mother cried.
She said he was wasting money that should go toward marriage.
He didn’t sell.
Over the next six years, that one position turned into over ₹18 lakh.
He never added another rupee.
He never traded.
He just held.
When people asked him his secret, he said one line:
“I didn’t invest in the stock.
I invested in the fact that I would not sell.”
Today he runs a small advisory for young investors from small towns.
His first rule is not about charts.
It is:
Before you buy anything, make sure you can survive being wrong for five years without selling.
Most people cannot.
That is why most people never make it.
Have you ever had money you refused to touch no matter what the market did?
Comment below.
#SmartMoney #SMFdata #IndianStockMarket
Recently, I travelled Delhi to Mumbai for a traders & manufacturers event.
There, I met a guy who supplies cosmetic chemicals to big companies.
I asked him: “If companies can buy directly from manufacturers at cheaper prices, why do they buy from you?”
He smiled and said: ↓↓↓
He smiled and said: “Because manufacturers make only specific chemicals.
We deal with multiple manufacturers and supply everything a company needs.”
Basically, one supplier instead of dealing with 10–20 manufacturers.
Then he dropped the number: ₹32 crore earned in the last 3 years.
I asked, “What does it take?” “₹15–20 lakh capital.
Because this business runs heavily on credit.”
And his target?
Big companies that manufacture their own products — because they constantly need raw materials.
That conversation taught me something: You don’t always need to make the product. Sometimes, being the bridge is the business.
What's your take?

#CYIENT
Data + Chart 🔥🔥🔥
How many of you are tracking? #stockmarket

The market gives you two choices every day:
Follow the price. Or follow the money.
Most people choose the first one because it is visible. The second one is quieter, but it usually moves first.
If you want to start seeing the second one clearly,
Comment “SMF”.
#SmartMoney #SMFdata
In 2008, a young investor watched the market crash 60%.
Everyone around him was selling.
His father told him one thing:
The market is not dying. The people who bought it are dying.
He did not understand it then.
He understood it 15 years later.
What did his father actually mean?
↓↓↓↓↓
He meant that a crash does not destroy companies. It destroys the people who cannot hold them.
In 2008, the same banks, the same cement companies, the same pharma businesses were still operating.
The factories were still running. The customers were still buying.
Only the owners changed.
The people who sold at the bottom handed their shares to the people who stayed.
That is how wealth transfers in every crash: not from rich to poor, but from impatient to patient.
The 2008 crash is the best example.
Nifty fell from 6,300 to 2,500.
Retail investors who had entered in 2007–08 sold in panic. The ones who held through 2009–2010 saw the market double from the bottom.
The lesson is not to buy every crash.
The lesson is: know why you bought before the crash starts.
If your reason is still valid when the price is down 40%, you hold.
If your reason was only that it was going up, you were never an investor; you were a passenger.
Most people who lost in 2008 did not lose because they picked bad stocks.
They lost because they had no reason to stay when the reason to buy disappeared.
Have you ever sold in a crash and later regretted it?
Comment below.
#SmartMoney #SMFdata #IndianStockMarket
A trader saw the higher open and bought immediately.
He said the market had turned.
He did not check Friday’s flows.
He did not check whether institutions were still selling.
By afternoon the early gains were gone.
He was already in a small loss and confused.
The open creates emotion.
The data creates the plan.
Have you ever bought a higher open and watched it fade?
Comment Yes or No.
#SMFdata #IndianStockMarket
A trader in 2022 had one rule.
If a stock fell 15%, he would buy more.
He called it courage.
Friends called him a long-term investor.
He never checked who was selling.
In one mid-cap, the fall started slowly. First 12%. Then 20%. Then 35%.
Every drop looked like a bargain. So he added. Then added again. His average improved on paper. His capital did not.
For six months the stock stayed weak. No news. No recovery. Just lower lows.
He kept telling himself, “Quality always comes back.”
What he missed was simple.
While he was buying every dip, institutions were reducing.
Delivery was rising on down days because retail was absorbing the supply.
The chart looked cheap. The ownership data did not.
By the time he stopped averaging, the stock was down another 40% from his last buy.
He finally exited with close to a 70% loss on that position.
The painful part was not the loss.
Three quarters later, the same stock started a real move.
This time the data had changed.
Institutional holding was rising.
Down days were being absorbed by stronger hands, not by trapped retail.
He was no longer in it.
He had used all his patience in the wrong phase.
That is the expensive lesson.
Averaging down is not a strategy. It is a habit.
It works only when the people on the other side are accumulating. It destroys capital when they are leaving and you are the exit.
Cheap price is not the same as Smart Money buying.
Before you add to a falling stock, check one thing: who is still willing to own it?
Have you ever averaged down and later realised institutions were selling the whole time?
Comment yes or no.
#SmartMoney #SMFdata #IndianStockMarket
Every few months, a stock "gets added to Nifty Smallcap 250."
Retail reaction: "Index inclusion! Buy karo!"
Here's what actually happens 👇
The mechanism nobody explains:
1️⃣ Nifty rebalances twice a year (March & September).
Based on 6-month average market cap + liquidity.
2️⃣ When a stock enters an index, PASSIVE funds that track that index MUST buy it.
Not optional. Not based on fundamentals. Just mandatory rebalancing.
3️⃣ For Nifty Smallcap 250, the forced buying flow is typically $5-15 million per stock (depending on weight).
4️⃣ This happens on ONE specific day — the rebalance effective date.
Not before. Not after.
What retail keeps misreading:
⚠️ Lesson 1: Inclusion ≠ Business improved
Zero change in revenue, margins, orders, or management.
Just a technical index tweak based on past market cap.
⚠️ Lesson 2: The rally is FRONT-LOADED
Smart money starts buying 4-6 WEEKS before inclusion (anticipating passive flow).
By the time news hits headlines, 60-70% of the move is DONE.
⚠️ Lesson 3: The post-inclusion drift
Many stocks that enter an index UNDERPERFORM 3-6 months later.
Why? The passive buy is one-time. No fresh demand after.
Fundamentals have to carry the stock from there.
⚠️ Lesson 4: Removal is the opposite
When a stock EXITS an index, passive funds must SELL.
Equally mandatory. Equally mechanical.
This is why some stocks crash 20-30% in a week around removal dates.
What to actually watch:
📍 Rebalance pre-announcement date (not the effective date)
📍 Weight of stock in index (bigger weight = bigger flow)
📍 Delivery % trend 4-6 weeks pre-inclusion (smart money footprint)
📍 Business fundamentals (will they justify the new valuation?)
📍 Post-inclusion 90-day price action (the real test)
The lesson:
Index inclusion is a PLUMBING event.
Not a fundamental event.
Trade it with that lens.
Save this for the next inclusion story 📌
(Educational only. Not investment advice. DYOR.)
#Nifty #StockMarket #SmallCap #smfdata
A trader had a stock that was up 40%.
Friends told him to book profit.
Twitter said the stock looked expensive.
He sold.
Three months later, the same stock was up another 80%.
Data later showed institutions were still buying when he exited.
He did not lose because the stock was bad.
He lost because he followed noise instead of the footprints.
Have you ever sold a winner too early just because people around you were booking profit?
Comment Yes or No with stock name
#SmartMoney #SMFdata #IndianStockMarket
New Website and Screener for SMF data are almost ready
By this weekend will share access with all existing members
You will get all videos linked in the format within your dashboard, with all tool indicators and everything

Something historic is happening in Indian markets 📊
FPIs just set a RECORD.
The number nobody's framing properly 👇
2026 YTD FPI outflows: ₹3+ LAKH CRORE
2025 full-year FPI outflows: ₹1.66 LAKH CRORE
That's +57% MORE outflow in 9 months than ALL of last year.
The breakdown:
📊 September alone: ₹35,860 CR sold (highest since April)
📊 Oct 1 alone: ₹9,232 CR out
📊 Oct so far: ₹18,513 CR out
📊 Nifty YTD: -14% (worst since 2011)
📊 Sensex YTD: -15.5%
Why FPIs are running:
✅ US 10-year yield at 5.29% (risk-free money)
✅ Dollar strength crushing EM returns
✅ Crude pressure on India's current account
✅ Weak rupee eating foreign returns
✅ US-Iran geopolitical stalemate
What retail keeps missing 👇
⚠️ Point 1: FPI outflow ≠ Indian market collapse
Despite ₹3 lakh crore outflow, Nifty only down 14%.
Historically that scale of FPI exit = 25-30% crash.
Why hasn't it happened?
Point 2: DIIs are the invisible army
SIP flows: ~₹25,000 Cr/MONTH
Domestic insurance + MF inflows absorbing the sell pressure
This is a structural shift most retail still hasn't registered
Point 3: FPIs don't exit India permanently
Look at Oct 2022-March 2023: ₹1.17 lakh Cr OUT
Then April 2023-Jan 2024: ₹2.5 lakh Cr IN
When the US yield cycle cools, flows reverse FAST
What to actually watch next:
📍 US 10-year yield — if it cracks below 5%, flows return
📍 Rupee stability (needs to hold 85-86 zone)
📍 Crude trajectory (below $90 = relief)
📍 Q2 FY27 results (fundamentals vs sentiment gap)
📍 DII absorption capacity (SIPs stay sticky or wobble?)
The lesson:
Panic headlines sell newspapers.
Pattern recognition builds portfolios.
FPI exits are a CYCLE, not an ending.
Save this 📌
(Educational only. Not investment advice. DYOR.)
#FPI #Nifty #StockMarket #Sensex #smfdata