

With over 20 years of experience in wealth management and the stock market, I specialize in identifying high-growth opportunities while maintaining strict risk
Joined March 2020
- Tweets2.9K
- Following6.2K
- Followers8.4K
- Likes1.4K





Pinned Tweet
The market is full of opportunities every single day—but the real question is, can you spot them early enough? Reach out via WhatsApp:
wa.me/16463232174
Or click on my profile to connect. I’ve set up a free stock discussion group where I share U.S. stock investment opportunities worth keeping a close eye on. Whether it’s day trading, high-growth stocks, long-term plays, or trending market themes—I focus on stocks with an upside potential of over 30%. If you’d rather not spend your whole day glued to the market, come join us! Once you’ve added me, just send the number "9" to receive an invitation to the group. The next big opportunity might just come along right after you join.
#NVDA #TSLA #AMD #PLTR #CRM #MSFT #HOOD

$AAON: The AI Boom Is Creating a Massive Opportunity in Data Center Cooling
Most investors are focused on AI chips, GPUs, and semiconductor companies. But there is another critical part of the AI infrastructure market that deserves attention: cooling.
And $AAON is positioning itself right in the middle of this opportunity.
Key Highlights
AAON closed November 9 at approximately $62.87.
Its Q3 2026 results were impressive:
Revenue reached a record $707.4 million, up 84.1% year over year.
Operating income increased 129.3% to $100 million.
Diluted EPS climbed 124.3% to $0.83.
Total backlog increased 40.5% to approximately $1.9 billion.
Year-to-date operating cash flow reached $146.9 million.
Even more importantly, management raised its full-year 2026 revenue growth outlook to 72%–75%.
Why the Macro Environment Matters
AI data centers require increasingly sophisticated thermal management systems.
As GPU computing density rises, traditional air-cooling solutions become less sufficient. Liquid cooling, precision airflow management, and customized cooling infrastructure are becoming increasingly important.
This creates a long-term demand opportunity for companies capable of delivering advanced thermal solutions.
Investment Logic
AAON benefits from two complementary growth engines:
Its traditional HVAC business provides an established customer base.
Its BASX business targets high-performance computing and data center cooling.
BASX revenue has been expanding rapidly, supported by increased manufacturing capacity and strong demand.
The company's approximately $1.4 billion BASX backlog provides meaningful visibility into future project conversions.
Geopolitical and Supply Chain Risks
Tariffs, international trade restrictions, component shortages, and geopolitical disruptions could increase manufacturing costs or delay deliveries.
However, expanding domestic manufacturing capabilities and diversified project locations could help improve operational resilience.
What I Am Watching
Whether the company can convert its $1.9 billion backlog into revenue.
Whether gross margins continue improving.
Whether BASX demand remains strong.
Whether management successfully addresses its disclosed material weakness in financial reporting controls.
The latest restatement and internal-control weakness are important risks that investors should not ignore.
Investment Outlook: Bullish
Short-term price target: $70–$78
Reference price: $62.87.
My view is that the market may be underestimating how important cooling infrastructure will become as AI computing expands.
I am particularly interested in the company's ability to turn its growing backlog into sustainable earnings and free cash flow.
Are you watching the cooling side of the AI revolution, or are you still focused entirely on chipmakers?
Follow my profile for more overlooked AI infrastructure opportunities. I also share additional stock research, entry levels, and market discussions in my investment group. Check my profile if you want to join.
#AAON #AIInfrastructure #DataCenter #LiquidCooling #AIGrowth #SmallCapStocks #StockMarket

49
Broadcom (AVGO) is pulling back after yesterday’s strong rally on the Nvidia leadership shift. The custom AI chip thesis remains intact, but elevated wholesale inflation (PPI) is weighing on high-multiple tech. Cisco (CSCO) is also digesting its strong earnings and raised AI guidance; the beat was solid, yet the stock faces profit-taking. Amazon (AMZN) looks more resilient on AWS growth near 40%, with the large backlog supporting cloud strength even if the broader tape stays soft. Into today’s close, AVGO and CSCO may struggle to reclaim early gains, while AMZN has a better chance of holding flat to modestly green if buyers step in on AI cloud names. Watch volume and the 10-year yield for confirmation.
Drop your close prediction for AVGO, CSCO or AMZN in the comments — I’ll reply with my levels. Join the group for daily open-to-close updates and real-time notes.
#AVGO #CSCO #AMZN #AIChips #CloudComputing #TechPullback #PPIData
1
78
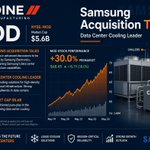
$MOD – Modine Manufacturing: Artificial Intelligence Cooling Technology Acquisition Strategy Key Points:
Modine, a pure-play thermal management company focused on data center cooling, previously spun off its automotive business. Bloomberg reports that Samsung is in advanced talks to acquire the company (which could be completed within weeks). Thanks to a multi-billion-dollar supply agreement with Google, its data center business revenue increased by approximately 95% year-on-year. The stock price surged by more than 25-30% before the market opened, reflecting market expectations for acquisition premiums.
Given the critical role of cooling in AI infrastructure and Samsung's Korean ownership, the Committee on National Security Review (CFIUS) may delay or change any deal with Samsung. Export controls or tariff adjustments on high-end cooling components will exacerbate supply chain frictions. This impact is mitigated to some extent by domestic capacity expansion, such as a new plant in Texas.
The density of artificial intelligence racks has exploded; heat dissipation has become a bottleneck. Samsung has acquired Fläkt Group and hopes to gain access to North American production capacity and partnerships with hyperscale data center operators. Modine's more than $4 billion in signed orders and capacity increases give it scarcity value. Acquisitions provide exit security; even if negotiations fail, standalone growth remains strong.
Key points:
Deal confirmation timeline, shareholder vote threshold (two thirds required), capacity utilization, and any competing offers from Vertiv/LG/Daikin.
Outlook: Bullish. Near-term target price: US$145-160 (already includes part of the transaction premium; if there is a formal acquisition offer, the target price will be higher).
If you are following Samsung’s transaction progress, please leave a message to share your views and follow us for real-time M&A updates. Join our private group (link in bio) to get exclusive investment strategy updates and alerts.
#NVDA #AMD #AIChips #datacentercooling #MOD #SamsungAcquisition #Cerebras

70
Modine Manufacturing (NYSE: MOD) shares jumped sharply in pre-market trading on November 13, 2026, as investors focused on the company’s thermal management solutions critical for AI data centers. With Nvidia CEO Jensen Huang’s recent resignation creating uncertainty in the AI chip sector, hyperscalers are accelerating infrastructure builds, boosting demand for efficient cooling systems like those from Modine.
The broader U.S. stock market showed caution, with futures steady ahead of key inflation data. S&P 500 and Nasdaq futures edged higher slightly as traders weighed rising Fed rate-hike bets and the Nvidia leadership change, which has driven rotation into alternative tech suppliers. Modine’s expertise in heat transfer for high-performance computing positions it well in this environment, especially after strong recent revenue growth in industrial and climate solutions.
Analysts note the company’s dual segments—Climate Solutions and Performance Technologies—support both traditional and emerging AI applications. As data center power and cooling needs expand rapidly, MOD’s role in enabling reliable AI infrastructure gains attention from institutional investors seeking stable industrial exposure amid tech turbulence.
#AIDataCenters #ThermalManagement #ModineStock #USStockNews #DataCenterCooling #IndustrialTech #AIInfrastructure
39
Still time in today’s session! These names are showing strength right now:
$LUNR — space/industrials name posting solid percentage gains with elevated volume and earnings-related interest.
$AVEX — industrial name leading some gainers lists with strong relative performance.
$MBGL — consumer discretionary name catching a bid on positive updates. Advantage: Early session leadership + volume. Can they still push into the close? Possible if buyers defend levels and broader risk appetite holds, but stay alert for fades. Don’t watch from the sidelines — follow my profile for live updates and join the group for instant alerts!
#SpaceStocks #Industrials #StockGainers #LiveTrading #MarketMovers #BullishFlow #DayTrading
99
$MMSI: (Merit Medical Systems) Stock Recommendation: Merit Medical Systems (MMSI) is a company specializing in interventional medical devices, with core businesses covering cardiovascular, peripheral vascular, endoscopy, and fluid management. The company's products directly serve minimally invasive surgery scenarios, benefiting from the long-term trends of global population aging, increased chronic diseases, and the continued increase in the penetration rate of minimally invasive surgery. Key Points:
MMSI has recently shown solid performance. Third-quarter revenue was approximately $416 million, a year-over-year increase of 8.4%, with organic constant currency growth of approximately 9%, and the company raised its full-year guidance. Market capitalization is approximately $5.2-5.3 billion, and the current valuation is within a reasonable range compared to its medical device peers. The analyst consensus rating is Buy, with an average target price of approximately $107, representing an upside of over 20% from the current price. The company has stable gross margins and healthy free cash flow, and has achieved better-than-expected earnings for several consecutive quarters. Geopolitical Risks Affecting Supply:
The medical device supply chain is highly sensitive to geopolitics. US-China trade frictions, changes in tariff policies, and restrictions on the export of key raw materials may drive up production costs and extend delivery cycles. MMSI relies heavily on the Asian supply chain for some core components and raw materials, particularly China and Southeast Asia. Further geopolitical tensions could lead to short-term cost pressures. However, the company is actively pursuing supply diversification and partial localization of production to reduce dependence on a single region. Investors should continuously monitor tariff policies and key supplier dynamics, as these are crucial variables for short-term stock price fluctuations. Investment Logic: The core investment logic lies in: Long-term growth in demand for minimally invasive surgery and interventional treatments; continued hospital demand for high-quality, cost-effective medical devices; the company's product line covers multiple high-value clinical scenarios, resulting in strong customer loyalty; the upward revision of full-year guidance reflects management's confidence in order visibility and execution capabilities; and the valuation remains attractive relative to growth potential, with a reasonable PEG ratio.
Key Focus Areas: Supply chain resilience and cost transmission capabilities; new product approval progress and market share changes; hospital capital expenditure cycles and the recovery of elective surgeries; currency fluctuations and potential tariff impacts.
Investment Recommendations: Suitable for conservative investors with a medium-term investment horizon. It is recommended to gradually build positions during pullbacks and set reasonable stop-loss orders. Short-term opportunities may arise after earnings reports, while the company's continued expansion capabilities in the interventional medical field are more promising in the medium term. Outlook: Bullish
Near-term target price: $100-$110. If the full-year guidance is successfully delivered and supply chain risks are manageable, the price is expected to move closer to the high target price range set by analysts. Attractive wording:
Reply with "MMSI" or "healthcare stocks" in the comments section, and I will send you the latest supply chain risk tracking table and position recommendations! Reply with "Join Group" via private message to join our US healthcare + AI rotation discussion group, where we share hot stocks and trading plans daily before the market opens.
#AIStocks #Semiconductors #PremarketTrading #EarningsReports #DataCenter #GLP1 #Healthcare

82
Merit Medical Systems (MMSI) reported third-quarter 2026 revenue of $416.2 million, up 8.4% year-over-year, with organic constant-currency growth of 9%. GAAP EPS reached $0.70 (up 51%), and non-GAAP EPS hit $1.12, beating estimates. Operating margins expanded significantly, and management raised full-year 2026 revenue guidance to approximately $1.635–$1.642 billion while lifting non-GAAP EPS expectations. The company also highlighted real-world data from the AVF cohort of the WRAP Global Registry and the recent ~$45 million acquisition of Solo Pace to expand its structural heart the broader U.S. equity market, healthcare and medical-device names have shown resilience amid mixed macro data, while AI-related semiconductor stocks (including AMD and AVGO) continue to drive major index moves. Investors are closely watching data-center power demand and related infrastructure spending.
#AIinfrastructure #Semiconductors #DataCenterPower #HealthcareGrowth #EarningsBeat #GLP1 #MarketVolatility
59
$CRWV: CoreWeave shares surged 21.71% to $59.31 following a third-quarter earnings report that significantly beat expectations! Revenue jumped 168% to approximately $3.7 billion, with upward-revised guidance and a massive order backlog exceeding $132 billion—allaying concerns about a potential slowdown in AI growth.
Strengths: A pure-play AI cloud specialist, boasting top-tier GPU performance, massive scale (hundreds of thousands of GPUs), priority access to NVIDIA’s latest technology, and the trust of leading AI labs. The company also demonstrates strong pricing power and a growing volume of customer prepayments.
Closing Outlook: Strong upward momentum and a broader sector recovery should help the stock retain most of its gains—or even climb higher—by the close, though expect continued volatility following such a sharp move.
Drop your target price in the comments—what’s your next AI investment target?
Follow us for daily top-performer picks! If you’re bullish on this trend, give us a like! Join our group for real-time alerts and in-depth analysis.
#AIStocks #CoreWeave #Neocloud #EarningsBeat #GPUCloud #AIInfrastructure #TechStockRally

CoreWeave (CRWV) is the purest public new cloud platform, providing dedicated GPU capacity for AI training and inference. After a deep pullback, Q3 results exceeded expectations, leading to an upward revision of guidance and reigniting the stock price.
Geopolitical risks and supply impacts: Export controls and power restrictions remain real risks to the overall AI deployment landscape. CoreWeave is mitigating these risks through customer-supported financing and approximately $9 billion in upfront payments/deposits expected to be received in the next three months. Current utilization exceeds 1.7 GW, with a year-end target of 1.85 GW. A $132.5 billion revenue reserve provides excellent visibility.
Q3 revenue grew 168% year-over-year to $3.66 billion, exceeding expectations. Full-year 2026 guidance was revised upward to $13 billion to $13.3 billion, with adjusted operating income of $1.275 billion to $1.375 billion. Customers prepaid most of the construction costs, reducing reliance on unsecured debt. Adjusted operating margin reached double digits ahead of schedule. Profitability is expected in the first half of 2028.
Capital expenditures (currently projected at $37 billion to $39 billion), power delivery schedules, and potential equity dilution from convertible bond or equity financing are concerns. High leverage and a high beta mean volatility will remain high.
Near-term target price: $75-$90
Leave your target price for CRWV in the comments—are you planning to buy on dips or continue to wait and see? Follow me and join the private group in my profile to get daily exclusive AI infrastructure maps, power dynamic updates, and unannounced real-time trading strategies.
#AIInfrastructure #CoreWeave #Neocloud #Backlog #CustomerPrepayments #GPUCloud #ComputingCapacity

1
83
CoreWeave (CRWV) is the purest public new cloud platform, providing dedicated GPU capacity for AI training and inference. After a deep pullback, Q3 results exceeded expectations, leading to an upward revision of guidance and reigniting the stock price.
Geopolitical risks and supply impacts: Export controls and power restrictions remain real risks to the overall AI deployment landscape. CoreWeave is mitigating these risks through customer-supported financing and approximately $9 billion in upfront payments/deposits expected to be received in the next three months. Current utilization exceeds 1.7 GW, with a year-end target of 1.85 GW. A $132.5 billion revenue reserve provides excellent visibility.
Q3 revenue grew 168% year-over-year to $3.66 billion, exceeding expectations. Full-year 2026 guidance was revised upward to $13 billion to $13.3 billion, with adjusted operating income of $1.275 billion to $1.375 billion. Customers prepaid most of the construction costs, reducing reliance on unsecured debt. Adjusted operating margin reached double digits ahead of schedule. Profitability is expected in the first half of 2028.
Capital expenditures (currently projected at $37 billion to $39 billion), power delivery schedules, and potential equity dilution from convertible bond or equity financing are concerns. High leverage and a high beta mean volatility will remain high.
Near-term target price: $75-$90
Leave your target price for CRWV in the comments—are you planning to buy on dips or continue to wait and see? Follow me and join the private group in my profile to get daily exclusive AI infrastructure maps, power dynamic updates, and unannounced real-time trading strategies.
#AIInfrastructure #CoreWeave #Neocloud #Backlog #CustomerPrepayments #GPUCloud #ComputingCapacity
CoreWeave shares jumped more than 10% in premarket trading after reporting Q3 revenue of $3.66 billion, up 168% year-over-year and ahead of estimates. The company raised full-year 2026 revenue guidance to $13–$13.3 billion and pointed to roughly $9 billion in upcoming customer prepayments and deposits. Management highlighted a $132.5 billion contracted backlog and said demand continues to outstrip capacity. The results helped calm recent concerns about the sustainability of AI infrastructure spending and heavy debt-fueled buildouts across neoclouds. Broader US markets remained cautious after hotter-than-expected inflation data reinforced expectations of higher-for-longer interest rates, which has pressured high-capex AI names.
#CoreWeaveEarnings #AIInfrastructure #NeocloudRebound
44
Why these could move tomorrow:
$TTWO surged on strong GTA VI preorder commentary despite mixed earnings — momentum may continue.
$CHTR jumped double-digits on tender offer news and relative strength.
$AAON crushed it after raising full-year guidance on record Q3 sales (HVAC/energy efficiency play).
Watching these for potential follow-through.
Follow me for daily structured analysis + join my group for exclusive watchlists and deeper breakdowns.
#GTA6 #HVAC #MomentumTrading #EarningsReaction #Communications #StockAnalysis #TomorrowSetup
96
$STAK +36% Missed this move? Don't chase yesterday's winner. Keep an eye out for tomorrow's setup. Every day, I curate a list of stocks to watch, key catalysts, and market trends. Want to join my WhatsApp group? Profile → WhatsApp → Send "3" Let's find the next opportunity worth watching together.
#NVIDIA #MU #SNDK #AMD #AI #Semiconductors #Memory

Some opportunities are better discussed in a focused environment rather than posted publicly. Today’s private watchlist includes:
$S
*** I’m sharing the full analysis with my private group members first. The setup includes: Entry → Risk → Momentum → Exit Members will have access to a reference entry range, defined risk level, intraday updates and potential exit signals. The stock could experience 10%–40% intraday movement under the right market conditions, which also means elevated risk. If you want access to the same stock information: Add my WhatsApp through the number on my profile. Send me a message after adding me. I’ll share the information that was posted in the group. Private research. Clear levels. Your decision.
#Stock #StockMarket #NVDA #MSFT #MU #AVGO #TSLA
113
$AAON: This performance surge was primarily driven by a strong third-quarter result: record revenue of $707 million (84% year-over-year growth), adjusted earnings per share of $0.83 (far exceeding market expectations), and a significant upward revision of 2026 sales growth guidance to 72% to 75% (previously 55% to 60%). BASX brand sales soared 218%, primarily driven by increased demand for hyperscale data center cooling and a robust order backlog.
Advantages: Direct access to the hottest components of AI infrastructure (liquid cooling/high-density HVAC), improving margins and enhancing long-term prospects.
Closing Outlook: Solid momentum. Strong fundamental surprises coupled with the AI infrastructure theme should support the stock price until the close, but profit-taking remains a possibility after such a significant rise. Unless there is a sharp market reversal, the stock price is expected to maintain its upward trend.
Leave your AAON target in the comments section or join our private group for real-time updates and exclusive allocation information. Which AI infrastructure company are you focusing on next?
#AIDataCenter #HVACStocks #BetterEarningsThanExpectations #DataCenterCooling #AAON #StockPriceSurge #TechnologyInfrastructure

$AAON: The AI Boom Is Creating a Massive Opportunity in Data Center Cooling
Most investors are focused on AI chips, GPUs, and semiconductor companies. But there is another critical part of the AI infrastructure market that deserves attention: cooling.
And $AAON is positioning itself right in the middle of this opportunity.
Key Highlights
AAON closed November 9 at approximately $62.87.
Its Q3 2026 results were impressive:
Revenue reached a record $707.4 million, up 84.1% year over year.
Operating income increased 129.3% to $100 million.
Diluted EPS climbed 124.3% to $0.83.
Total backlog increased 40.5% to approximately $1.9 billion.
Year-to-date operating cash flow reached $146.9 million.
Even more importantly, management raised its full-year 2026 revenue growth outlook to 72%–75%.
Why the Macro Environment Matters
AI data centers require increasingly sophisticated thermal management systems.
As GPU computing density rises, traditional air-cooling solutions become less sufficient. Liquid cooling, precision airflow management, and customized cooling infrastructure are becoming increasingly important.
This creates a long-term demand opportunity for companies capable of delivering advanced thermal solutions.
Investment Logic
AAON benefits from two complementary growth engines:
Its traditional HVAC business provides an established customer base.
Its BASX business targets high-performance computing and data center cooling.
BASX revenue has been expanding rapidly, supported by increased manufacturing capacity and strong demand.
The company's approximately $1.4 billion BASX backlog provides meaningful visibility into future project conversions.
Geopolitical and Supply Chain Risks
Tariffs, international trade restrictions, component shortages, and geopolitical disruptions could increase manufacturing costs or delay deliveries.
However, expanding domestic manufacturing capabilities and diversified project locations could help improve operational resilience.
What I Am Watching
Whether the company can convert its $1.9 billion backlog into revenue.
Whether gross margins continue improving.
Whether BASX demand remains strong.
Whether management successfully addresses its disclosed material weakness in financial reporting controls.
The latest restatement and internal-control weakness are important risks that investors should not ignore.
Investment Outlook: Bullish
Short-term price target: $70–$78
Reference price: $62.87.
My view is that the market may be underestimating how important cooling infrastructure will become as AI computing expands.
I am particularly interested in the company's ability to turn its growing backlog into sustainable earnings and free cash flow.
Are you watching the cooling side of the AI revolution, or are you still focused entirely on chipmakers?
Follow my profile for more overlooked AI infrastructure opportunities. I also share additional stock research, entry levels, and market discussions in my investment group. Check my profile if you want to join.
#AAON #AIInfrastructure #DataCenter #LiquidCooling #AIGrowth #SmallCapStocks #StockMarket
1
61
Some opportunities are better discussed in a focused environment rather than posted publicly. Today’s private watchlist includes:
$S
*** I’m sharing the full analysis with my private group members first. The setup includes: Entry → Risk → Momentum → Exit Members will have access to a reference entry range, defined risk level, intraday updates and potential exit signals. The stock could experience 10%–40% intraday movement under the right market conditions, which also means elevated risk. If you want access to the same stock information: Add my WhatsApp through the number on my profile. Send me a message after adding me. I’ll share the information that was posted in the group. Private research. Clear levels. Your decision.
#Stock #StockMarket #NVDA #MSFT #MU #AVGO #TSLA
$AAON: The AI Boom Is Creating a Massive Opportunity in Data Center Cooling
Most investors are focused on AI chips, GPUs, and semiconductor companies. But there is another critical part of the AI infrastructure market that deserves attention: cooling.
And $AAON is positioning itself right in the middle of this opportunity.
Key Highlights
AAON closed November 9 at approximately $62.87.
Its Q3 2026 results were impressive:
Revenue reached a record $707.4 million, up 84.1% year over year.
Operating income increased 129.3% to $100 million.
Diluted EPS climbed 124.3% to $0.83.
Total backlog increased 40.5% to approximately $1.9 billion.
Year-to-date operating cash flow reached $146.9 million.
Even more importantly, management raised its full-year 2026 revenue growth outlook to 72%–75%.
Why the Macro Environment Matters
AI data centers require increasingly sophisticated thermal management systems.
As GPU computing density rises, traditional air-cooling solutions become less sufficient. Liquid cooling, precision airflow management, and customized cooling infrastructure are becoming increasingly important.
This creates a long-term demand opportunity for companies capable of delivering advanced thermal solutions.
Investment Logic
AAON benefits from two complementary growth engines:
Its traditional HVAC business provides an established customer base.
Its BASX business targets high-performance computing and data center cooling.
BASX revenue has been expanding rapidly, supported by increased manufacturing capacity and strong demand.
The company's approximately $1.4 billion BASX backlog provides meaningful visibility into future project conversions.
Geopolitical and Supply Chain Risks
Tariffs, international trade restrictions, component shortages, and geopolitical disruptions could increase manufacturing costs or delay deliveries.
However, expanding domestic manufacturing capabilities and diversified project locations could help improve operational resilience.
What I Am Watching
Whether the company can convert its $1.9 billion backlog into revenue.
Whether gross margins continue improving.
Whether BASX demand remains strong.
Whether management successfully addresses its disclosed material weakness in financial reporting controls.
The latest restatement and internal-control weakness are important risks that investors should not ignore.
Investment Outlook: Bullish
Short-term price target: $70–$78
Reference price: $62.87.
My view is that the market may be underestimating how important cooling infrastructure will become as AI computing expands.
I am particularly interested in the company's ability to turn its growing backlog into sustainable earnings and free cash flow.
Are you watching the cooling side of the AI revolution, or are you still focused entirely on chipmakers?
Follow my profile for more overlooked AI infrastructure opportunities. I also share additional stock research, entry levels, and market discussions in my investment group. Check my profile if you want to join.
#AAON #AIInfrastructure #DataCenter #LiquidCooling #AIGrowth #SmallCapStocks #StockMarket
AAON Inc. (AAON) delivered record third-quarter 2026 results, with net sales jumping 84.1% year-over-year to $707.4 million. Operating income more than doubled to $100 million, and diluted EPS reached $0.83. The strong performance was driven by BASX-branded sales, which soared 218% on robust data center cooling demand, alongside solid AAON-branded growth. The company raised its full-year 2026 sales growth outlook to 72%-75% from 55%-60%, supported by a $1.9 billion backlog. It also disclosed a material weakness in internal controls and restated prior quarters, though results improved overall. Shares jumped more than 20% in premarket trading. This comes as broader AI infrastructure spending continues to lift related industrials, with peers in thermal management and power equipment also seeing interest ahead of today’s CPI data.
#AAON #DataCenter #HVAC #EarningsBeat #Premarket #AIInfrastructure #StockRally
25
$GFS:Close: $40.51 (+4.89%)GlobalFoundries quietly delivered a solid +4.89% session while the broader semiconductor complex rebounded hard. In a market still digesting last week’s volatility, GFS showed relative strength and clean price action above key short-term levels. This is the kind of name that rewards patient, process-driven traders who focus on structure rather than noise.
If you want consistent, high-probability setups like this delivered daily with clear risk levels and full reasoning, follow me and join the private group. We focus on edge, not hype.
#GlobalFoundries #GFS #Semiconductor #ChipStocks #TechRebound #NASDAQ #StockAnalysis

$GFS — GlobalFoundries
Investment Outlook: Bullish | Short-Term Target: $42–$45
The Next AI Infrastructure Opportunity May Be Hiding Behind Semiconductor Manufacturing.
The AI boom is not just about GPUs. Every AI server, networking system, automotive platform and advanced electronic device depends on reliable semiconductor manufacturing. This is where GlobalFoundries ($GFS) deserves more attention.
Key Investment Highlights
AI Infrastructure Demand: Growing demand for data centers, optical connectivity and high-performance computing is creating new opportunities for specialized semiconductor manufacturers.
U.S. Manufacturing Expansion: GlobalFoundries is strategically positioned to benefit from domestic semiconductor investment and supply-chain diversification.
Advanced Packaging Opportunity: Its $2 billion manufacturing agreement with TSMC for silicon interposers could establish an important position in the U.S. advanced packaging ecosystem.
Optical Connectivity: Expanded cooperation with Marvell supports growing demand for silicon photonics, SiGe, NPO and CPO technologies.
Geopolitical Risks and Supply-Chain Advantages
Global semiconductor supply chains remain exposed to geopolitical tensions, export restrictions and regional manufacturing concentration.
Companies and governments increasingly want diversified manufacturing outside concentrated Asian supply chains.
GFS could benefit from this shift through its U.S., European and Asian manufacturing footprint.
However, geopolitical tensions can also increase equipment costs, disrupt material availability and delay expansion projects.
Latest Financial Results
Q3 2026 results:
Revenue: $1.899 billion.
Non-IFRS gross margin: 31.4%.
Non-IFRS EPS: $0.53.
Adjusted EBITDA: $647 million.
Cash and marketable securities: $3.2 billion.
The company also reported an IFRS net loss of $270 million, primarily driven by a $441 million non-cash charge associated with shares issued to the U.S. government.
The underlying adjusted profitability tells a stronger operating story, but investors should not ignore the accounting impact.
Investment Logic
I see three major drivers:
AI infrastructure is increasing demand for specialized chips and advanced packaging.
Government-backed domestic manufacturing initiatives could strengthen long-term revenue visibility.
Optical connectivity and silicon interposers create opportunities beyond traditional semiconductor manufacturing.
What to Watch
Execution of the TSMC manufacturing agreement.
Advanced packaging capacity expansion.
AI and data-center customer demand.
Gross-margin improvement.
Capital expenditure and project execution.
Investment Recommendation
Outlook: BULLISH
Short-term target: $42–$45
Reference price: approximately $38.62 at the November 6 close.
My preferred strategy is to watch for consolidation above $37–$38 rather than chase a sudden rally. A sustained breakout above $40 would strengthen the bullish setup.
Risk: Semiconductor cyclicality, high capital requirements, geopolitical disruption and project delays.
Let's Talk About the Next Semiconductor Winners.
Follow my profile for more overlooked AI infrastructure opportunities. Comment GFS if you want to discuss the next potential breakout, or join my investment group to exchange research, trading ideas and market updates.
#GFS #SemiconductorStocks #AIInfrastructure #ChipStocks #SiliconPhotonics #TechStocks #StockMarket

201
$GFS — GlobalFoundries
Investment Outlook: Bullish | Short-Term Target: $42–$45
The Next AI Infrastructure Opportunity May Be Hiding Behind Semiconductor Manufacturing.
The AI boom is not just about GPUs. Every AI server, networking system, automotive platform and advanced electronic device depends on reliable semiconductor manufacturing. This is where GlobalFoundries ($GFS) deserves more attention.
Key Investment Highlights
AI Infrastructure Demand: Growing demand for data centers, optical connectivity and high-performance computing is creating new opportunities for specialized semiconductor manufacturers.
U.S. Manufacturing Expansion: GlobalFoundries is strategically positioned to benefit from domestic semiconductor investment and supply-chain diversification.
Advanced Packaging Opportunity: Its $2 billion manufacturing agreement with TSMC for silicon interposers could establish an important position in the U.S. advanced packaging ecosystem.
Optical Connectivity: Expanded cooperation with Marvell supports growing demand for silicon photonics, SiGe, NPO and CPO technologies.
Geopolitical Risks and Supply-Chain Advantages
Global semiconductor supply chains remain exposed to geopolitical tensions, export restrictions and regional manufacturing concentration.
Companies and governments increasingly want diversified manufacturing outside concentrated Asian supply chains.
GFS could benefit from this shift through its U.S., European and Asian manufacturing footprint.
However, geopolitical tensions can also increase equipment costs, disrupt material availability and delay expansion projects.
Latest Financial Results
Q3 2026 results:
Revenue: $1.899 billion.
Non-IFRS gross margin: 31.4%.
Non-IFRS EPS: $0.53.
Adjusted EBITDA: $647 million.
Cash and marketable securities: $3.2 billion.
The company also reported an IFRS net loss of $270 million, primarily driven by a $441 million non-cash charge associated with shares issued to the U.S. government.
The underlying adjusted profitability tells a stronger operating story, but investors should not ignore the accounting impact.
Investment Logic
I see three major drivers:
AI infrastructure is increasing demand for specialized chips and advanced packaging.
Government-backed domestic manufacturing initiatives could strengthen long-term revenue visibility.
Optical connectivity and silicon interposers create opportunities beyond traditional semiconductor manufacturing.
What to Watch
Execution of the TSMC manufacturing agreement.
Advanced packaging capacity expansion.
AI and data-center customer demand.
Gross-margin improvement.
Capital expenditure and project execution.
Investment Recommendation
Outlook: BULLISH
Short-term target: $42–$45
Reference price: approximately $38.62 at the November 6 close.
My preferred strategy is to watch for consolidation above $37–$38 rather than chase a sudden rally. A sustained breakout above $40 would strengthen the bullish setup.
Risk: Semiconductor cyclicality, high capital requirements, geopolitical disruption and project delays.
Let's Talk About the Next Semiconductor Winners.
Follow my profile for more overlooked AI infrastructure opportunities. Comment GFS if you want to discuss the next potential breakout, or join my investment group to exchange research, trading ideas and market updates.
#GFS #SemiconductorStocks #AIInfrastructure #ChipStocks #SiliconPhotonics #TechStocks #StockMarket
GlobalFoundries reported Q3 2026 revenue of $1.899 billion (+13% YoY), with non-IFRS gross margin at a record 31.4% driven by high-value AI, data center, and communications infrastructure demand. Non-IFRS net income reached $298 million ($0.53 EPS). Capacity is fully booked through 2027. The company was selected as technology provider/operator for two new Malta, NY fabs under a U.S.-Japan initiative (up to $21B funding) and amended its CHIPS Act award. Shares had reacted to elevated 2027 CapEx plans (~$4B). This fits the broader semiconductor strength as AI infrastructure spending remains elevated across the sector.
#AIDemand #SemiconductorCapacity #CHIPSAct #DataCenterGrowth #FoundryExpansion #MarginExpansion #TechInfrastructure
138
$AMD: In the current US stock market environment, the AI semiconductor sector remains a core driver. As a key player, AMD has recently demonstrated strong price momentum, with its data center business continuing to increase its share. Large order agreements with major AI customers support medium-term growth, while AMD is gradually expanding its market share in inference chips. Investors should pay attention to potential valuation pressures from changes in interest rate expectations, as well as the policy impact of data center construction progress. Rational allocation and setting clear stop-loss orders are key. After tomorrow's market opening, pay close attention to whether trading volume continues to increase.
#AMDStock #AISemiconductors #DataCenterGrowth #ChipRally #TechAnalysis #USStocks #MomentumTrade

45