
Voss Capital
Joined August 2024
- Tweets89
- Following217
- Followers376
- Likes23

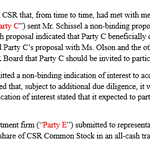




Looks like there was lots of interest in $CSR - 20 parties by my count. Maybe not the strongest of bids but cash proposals of $65 / $65 / $68 per share over the last year.

1
1
336
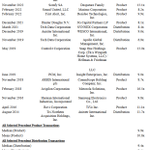
Proxy for $DSGR take private precedent transaction analysis shows median private market valuation of 11.3x EV/LTM EBITDA for distributors.

105

And looking through the $MAIR S-1, it looks like they sold Nortek Global HVAC (NGH) to Rheem / Paloma for somewhere around 15x trailing EBITDA in 2024.

112

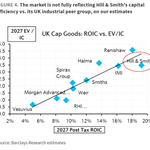
Nice to see Hill & Smith $HILS getting deemed a "quality growth" name with "standout ROIC". Very impressive 26% EBIT margins in the Galvanizing segment and good Transmission & Distribution / Data Center tailwinds in the US Engineered Solutions segment.


Pretty impressive that $350m of software loan exposure in a ~$258b portfolio (~0.13%) has taken $3.4b off of $CRBG's mcap (-21%)
1
1
131


Using $152m of NOI less mcapex and a 6.0% cap rate, the equity value would be ~$74.00/sh for $CSR

1
320
$ARE.to would be at $40/sh using 8x '27 EBITDA, while peers are trading at higher multiples.
"Aecon is the lease expensive construction stock in North America" - Canaccord

2
4
757
S&P 600 fwd P/E ratio is 15.3x and the S&P 500 fwd P/E ratio is 22.4x (per Yardeni). S&P500 cumulative outperformance over the last ~2.8 years is up to ~48%. On the back of the dot com bust, S&P 600 outperformed by a cumulative 43% from '00-'02.

2
333
$PHIN is still at a ~40% discount to relevant public peers according to CEO Brady Ericson at the MS Industrials Conference (6.1x fwd EBITDA vs 10.6x median)

This seems like a fair way to value Aecon ARE.TO. The company is not getting credit for its strong Nuclear and Utilities busineses, IMO. Sell side still seems focused on the very tail end of legacy fixed price contract losses and ignoring DD%+ growth in nuclear.

Given most other nuclear related stocks have performed very well recently, I'm surprised $ARE.TO has languished. Aecon's Nuclear related revenue has doubled over the last 3.5 years.

$ARE.TO 7 out of the 10 directors have bought shares in the open market over the last 5 months, in addition to the CFO & Head of IR/Corp Dev

Any opinion if $BX owned Merlin is clearing the way for a $PRKS acquisition with their plan to divest its aquarium assets (Sea Life)? A combination seems to make a lot of sense, and $BX could monetize the real estate as well as anybody.
blooloop.com/animals/news/me…

1
3
680
