

In-depth research on quality public companies 📖 Free content on Substack 🎧 Podcast: The Synopsis 👇 All Linked below 🔸— @DrewCohenMoney & @kevg1412
Joined September 2022
- Tweets6.2K
- Following263
- Followers12.4K
- Likes6.7K




Speedwell Research retweeted
$GOOG's search headwind

I’ve been thinking more about $GOOGL lately and I am coming more to the opinion that the real disruption to the search business could be around the corner.
With the proliferation of so many different AI chatbots, I would have thought that on its own would have weighed on their search business, but the reason it hasn’t is simple.
There are monetizable searches and non-monetizable searches.
What matters for Google’s profits is monetizable searches, and that is why Google can lose search activity and STILL be at an all-time high in search profits.
The non-monetizable searches are leaving, but not the monetizable ones… yet.
(Google will talk about search queries being at an all-time high, but that includes AI search queries and follow-ups, which aren’t comparable because it is a different product and monetized differently. Apple’s Head of Services, Eddie Cue, noted that Safari search queries were down for the first time in April 2025.)
I think this is just the first wave of AI, and it hasn’t negatively impacted Google’s search profits.
Chatbots are inherently a more informational product, but agents are about action, and with action comes encroachment on monetizable searches.
Booking travel with agents, which has already become a popular Instinct and Muse use case, cuts out Google’s opportunity to show sponsored search ads.
Ask Muse to find you the best running shoes and it will run its own search and give you options. There is no opportunity to show a Google search ad in that transaction.
This goes for essentially all high-intent shopping, where you know what you want but are still in research mode.
While agentic shopping is new and might take years to gain consumer adoption, Meta disclosed that over a quarter of engaged Muse users who shop through it have an average purchase size over $200. Instinct already has $1b in transaction volume, half of it going to travel.
In my conversation with @eric_seufert , he was of the opinion that agentic shopping is largely a mirage and that the commission Muse will charge will be a nonstarter for people.
After thinking about it more, I have two thoughts.
First, I don’t think it’s actually a problem if agents charge a small fee for completing purchases. I could see merchants ultimately bearing the cost of the transaction. Why would they do that?
Because they will get more sales from a new channel.
If we think about how online businesses get sales, it is either 1) through marketplaces like Amazon, 2) through online ads, or 3) direct to their website or app.
1) Marketplaces like Amazon have a commission that often ranges from 8-17% (this is just the sales commission, not including advertising or logistics). Companies accept this fee because they are getting sales they wouldn’t have otherwise.
2) Ads, whether through Instagram, Google search, etc., are usually significantly more than a couple % (if we think of the ad cost as a % of the sale).
3) Direct sales may not have any direct cost, but a lot of brand advertising is needed to build a brand that gets direct sales.
Taken together, I think the agentic channel, even with a business eating an additional ~2-4% fee, could be cheaper than most of their other channels. Said differently, if agentic shopping is bringing the business new sales, the ROI is still pretty high, even with the fee included.
Some businesses may fight this, but others will see the advantage of eating the fee and offering a lower price to win sales.
There is a historic parallel here with credit card fees. Initially merchants scoffed at paying ~3% credit card fees, but eventually they learned that accepting cards led to more sales and often higher tickets too. Most businesses today eat the fee.
Second, some small businesses already surcharge for card usage, and consumers by and large still opt to pay it rather than use a debit card or cash. Consumers have a preference for convenience, and I would imagine that translates to agentic commerce.
It’s the same with food delivery. When you order on DoorDash or UberEats, you can often pay less by ordering directly through the restaurant’s website or app (powered by ChowNow, for instance). Despite being cheaper, it’s still not that popular a way to order food.
While these two arguments point to different parties paying the fee, it doesn’t really matter which one wins out. (And it could be a mix of both). The point is that I don't think a take-rate to monetize agentic AI on its own is going to stop the ecosystem from growing, regardless of where that fee lands.
And for the threat to Google to be real, it doesn't actually matter how Agentic AI monetizes-- it could be through subscriptions or ad supported, but as long as the transaction is not through Google's agent it is still the same threat.
I think agentic shopping will be a real thing, and as adoption grows, we are likely to see more pressure on Google’s monetizable searches.
Google is responding with their own agentic capabilities, so they may be able to preserve some of the activity on their platform and some of the economics, but I still believe they are unlikely to end up with a business as good as their legacy search business.
*~*
This on its own is not a stock thesis on Google, since they still have many other businesses and initiatives that can make up for the shortfall, but I believe this will eventually be a notable headwind for them.
Happy to hear any push back and for more check out my latest video on Google below!

Speedwell Research retweeted

Really honored to have hosted @eric_seufert on our latest podcast!
We talk:
- Google Search Risks
- Agentic Commerce
- AI’s need for ads
- When ad model gains could plateau?
Watch on YT or Spotify now 👇

Speedwell Research retweeted
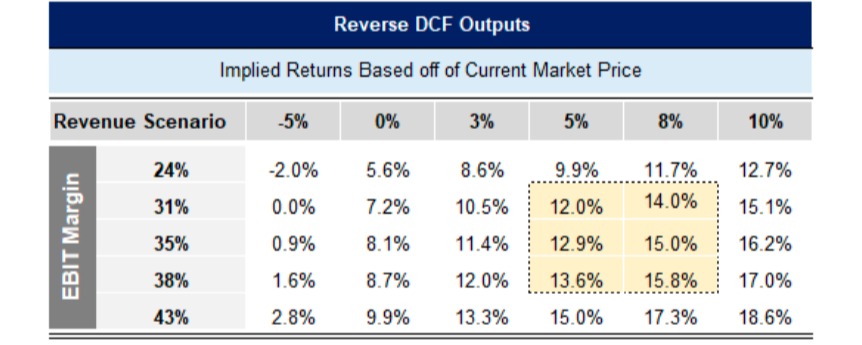
Just running some $SE math. Open invitation to poke holes in it.
Fully Diluted Mkt Cap: $52b
Net Cash (after leases): $5b
Ecommerce: $142b in GMV. Assume 30% isn't real economic activity because of refunds/ brushing.
At a 1.5% EBIT/GMV margin, which I think is conservative, that is $1.5b.
Sea Monee LTM EBIT $1B
Garena $1.5b EBIT
Add in about -$750m of other service losses and unallocated expenses. Then taxed at 32%.
Comes out to 21x earnings.
Last quarter total revenue's grew +48% y/y.
Keep in mind if we assume the higher EBIT/ GMV margin, then growth in that segment would be less, but a 1.5% EBIT/GMV margin is generally not a "fully monetized" ecomm margin, so there is still room for growth investment in that figure.
Also Garena can be a bit volatile and there is still an open question on long term credit risk for Sea Monee.

Speedwell Research retweeted
🚨Announcing New Research Report 🚨
🔻~🔻~🔻
Few industries have more failed businesses than ad tech. Even well established companies that have found their niche in the advertising ecosystem can still get decimated from technological or privacy changes. For a long time, it looked like AppLovin was going to be yet another one of those players, especially when Apple’s App Tracking Transparency changes were being implemented.
AppLovin was just coming off of a Covid-driven mobile gaming boom, having almost tripled revenues in a matter of a few years. However, their games business started to stutter and pending Apple iOS privacy changes would punish all mobile advertising players—even the mighty Facebook was warning they’d endure a $10 billion revenue headwind. To make matters worse, a leading game engine—Unity—was merging with ad tech player ironSource, giving AppLovin another formidable competitor.
While AppLovin’s stock may have been a “Covid darling”, achieving a ~$40 billion valuation at peak in 2021, their fortunes quickly reversed. Their stock would drop from over $110 a share to around ~$9 at the low, taking their market cap to below $4 billion: a ruthless >90% drop.
AppLovin’s response was simple: execution.
They rebuilt their ad model, taking advantage of the latest AI innovations, and rolled out AXON 2.0 in 2023. That year their advertising revenue growth re-accelerated, with record profitability growth coinciding. The business continued to boom in the following years, with revenues reaching ~$7bn LTM and stellar profit margins of 77%.
However, new threats are circling AppLovin with their extraordinary operating margins serving as an invitation to competitors. Unity has restructured their business and aggressively gone after AppLovin’s ads business. They have even gone as far as (allegedly) brazenly stealing data from AppLovin’s auctions, the discovery of which has now landed them in court. Despite the outcome of the litigation, there are already real signs that Unity is improving. And ad tech is a weird business in that you don’t have to actually lose business in order to become less profitable. Since ads are sold in auction, a competitor simply getting better can ruin the spread AppLovin currently makes on their ads.
So is AppLovin overearning currently with competition set to correct that? Investors certainly seem to be pricing in the possibility that their ad take-rates will compress. And their first ever earnings miss has only added fuel to those concerns. While management is guiding the business to still high growth rates (48% for next quarter) and talked about long-term growth of 20-30%, the market is pricing AppLovin as if something is severely wrong at just ~17x trailing earnings. So is the business breaking or is this an opportunity for an investor?
Sign up below to get accesss!

Speedwell Research retweeted
If you've never read a Speedwell Research report, it is a mix of a business case study and investment research report.
If you become a Speedwell Member, you get access to ALL of our research reports PLUS on-going updates.
Check out our latest that just dropped on $APP today.

🚨Announcing New Research Report 🚨
🔻~🔻~🔻
Few industries have more failed businesses than ad tech. Even well established companies that have found their niche in the advertising ecosystem can still get decimated from technological or privacy changes. For a long time, it looked like AppLovin was going to be yet another one of those players, especially when Apple’s App Tracking Transparency changes were being implemented.
AppLovin was just coming off of a Covid-driven mobile gaming boom, having almost tripled revenues in a matter of a few years. However, their games business started to stutter and pending Apple iOS privacy changes would punish all mobile advertising players—even the mighty Facebook was warning they’d endure a $10 billion revenue headwind. To make matters worse, a leading game engine—Unity—was merging with ad tech player ironSource, giving AppLovin another formidable competitor.
While AppLovin’s stock may have been a “Covid darling”, achieving a ~$40 billion valuation at peak in 2021, their fortunes quickly reversed. Their stock would drop from over $110 a share to around ~$9 at the low, taking their market cap to below $4 billion: a ruthless >90% drop.
AppLovin’s response was simple: execution.
They rebuilt their ad model, taking advantage of the latest AI innovations, and rolled out AXON 2.0 in 2023. That year their advertising revenue growth re-accelerated, with record profitability growth coinciding. The business continued to boom in the following years, with revenues reaching ~$7bn LTM and stellar profit margins of 77%.
However, new threats are circling AppLovin with their extraordinary operating margins serving as an invitation to competitors. Unity has restructured their business and aggressively gone after AppLovin’s ads business. They have even gone as far as (allegedly) brazenly stealing data from AppLovin’s auctions, the discovery of which has now landed them in court. Despite the outcome of the litigation, there are already real signs that Unity is improving. And ad tech is a weird business in that you don’t have to actually lose business in order to become less profitable. Since ads are sold in auction, a competitor simply getting better can ruin the spread AppLovin currently makes on their ads.
So is AppLovin overearning currently with competition set to correct that? Investors certainly seem to be pricing in the possibility that their ad take-rates will compress. And their first ever earnings miss has only added fuel to those concerns. While management is guiding the business to still high growth rates (48% for next quarter) and talked about long-term growth of 20-30%, the market is pricing AppLovin as if something is severely wrong at just ~17x trailing earnings. So is the business breaking or is this an opportunity for an investor?
Sign up below to get accesss!
Speedwell Research retweeted

Sorry babe, can't go out tonight...
@DrewCohenMoney just dropped a report on $APP

Our $APP research report was just posted!
This was a fascinating business to learn and write about because at ~17x trailing earnings, their valuation implies an extreme amount of investor doubt that they will continue to be a growth company.
We will be sending out an email out to members shortly, but you can access it through the website right now!

Speedwell Research retweeted
Our $APP research report was just posted!
This was a fascinating business to learn and write about because at ~17x trailing earnings, their valuation implies an extreme amount of investor doubt that they will continue to be a growth company.
We will be sending out an email out to members shortly, but you can access it through the website right now!
Speedwell Research retweeted
Is $GOOGL Search in trouble?
"And if you think about how Google monetizes, a lot of it is you're already looking for a website, and they just sell the sponsored ad of that company in order to get pushed up to the top, where that's not something you're gonna really need to do if you're going through one of these AI agents.
'Cause let's assume that you were looking for Best Buys or something like that to purchase a computer.
And so you went to Google, you typed in Best Buys.
The Best Buy sponsored link came up.
You clicked Best Buy, and Google took a little bit of money off of that transaction.
Now, if instead that behavior changes to you going to Muse, "Hey, I'm looking for a laptop. Can you pull me up laptop options?"
You're not ever doing that search in Google.
So it's gonna be interesting to see how this all unfolds.
I don't see how it's not a headwind to Google search.
The search business, as you point out, is one of the greatest businesses ever.
And even if they capture a lot of demand with their AI, 'cause they do own a lot of surfaces, right?
They still own Android and all of that.
But and so if they replace it with AI search and more targeted ads, it seems like that's gonna still be a lower gross margin business 'cause it's more compute-intensive.
You have to serve people a lot of content basically on the LLM before you ultimately get to that one thing you monetize.
So all of this, it seems like a headwind to the search business.
The tricky part with analyzing Google is they have a lot of bets, right?
Does Cloud make up for it?
Does YouTube make up for it?"


Speedwell Research retweeted

Real example of Muse and the OTA risk. $BKNG $META
I wanted to try what happened when I used Muse to book a stay in Florence, Italy.
First it returned 5 options. The links to ALL FIVE were Booking .com listings.
It did not prompt me to price check or go direct. I did prompt it to check if it was cheaper going direct.
From the time I asked it to check to when it answered me 14 minutes had passed- sure I could do other things in the mean time, but if I was really in the mood to search travel, I would have realistically just gone to different sites or did the check myself.
The conclusion was 2 out of the 5 listings were cheaper to go direct, with the other 3 cheaper on Booking .com. Although 1 of those was only cheaper because it was a non-refundable rate-- the refundable rate was the same as on Booking. (The one that was cheaper was because it had a special 15% discount if you stayed longer than 5 nights).
So really more like 1 out of 5 was clearly cheaper going direct, 1 was a wash, and 3 were more expensive going direct.
The interesting thing is people are acting like the abilit to price compare and shop rates is new with Muse.
Yes, I get it makes it more automatic, but a lot of travelers check the direct rate before booking. If the price is similar enough, they may still prefer to book on a better known site like Booking because of the support they expect to receive if something is wrong.
But also, who books hotels like this?
No pictures, no maps, no reviews. I have to trust it figured out the best one for me.
It makes sense as a place to start a search (better than Google perhaps), but for me at least this wouldn't satisfy me with enough info before booking.
The long wait time inbetween prompts would have compelled me onto a more traditional OTA to speed things up.
I get the interface and speed can/will improve in the future, but it still seems like the path of least resistance to just pull from Booking.
It may keep price checking and some consumers will save money from that, but it isn't built to scrap the entire web everytime a user searches for a hotel.
As Ben Thompson notes, in time they can build out their own web directory, but that still doesn't solve the live hotel inventory link.
I get AI Agents are scary and they will change the world in all sorts of ways that are hard to know ahead of time.
On the other hand, it is very hard for a single business to be great at everything.


There's a new version of this post
Speedwell Research retweeted
New Dialogue Podcast Released!
Is $CPRT now a turnaround story? Is this thesis drift?
AND
What hope does $TTD have of closing the loop and becoming a winner in connected TV?
Watch our first video podcast on YouTube!
👇
youtube.com/watch?v=oHksLk9E…

Speedwell Research retweeted
$BKNG AI Agents Threat
With everyone talking about $META’s Muse, I asked Gemini how my thesis that $BKNG is not at direct risk from AI Agents has held up.
TLDR is that:
1) AI Agents may use Booking but they aren’t likely to want to replace what Booking already does.
2) BKNG pays for a lot of sponsored ads already so that money could go to Meta instead of Google
3) They have a big direct booking business (their app) with a loyalty program and those users are harder to move purchase activity from (however, displacement here means higher ad costs, lower margins, but not an existential risk)
~*~*~
Summary of Drew Cohen’s Argument
In his deep dive on Booking Holdings, Drew Cohen addresses the prevailing bear case: autonomous AI agents will scrape hotel websites, bypass Online Travel Agencies (OTAs), and render Booking.com obsolete.
His rebuttal argues that Booking.com’s moat is operational, regulatory, and logistical—not just a search interface:
The Integration Barrier: Scraping the open web for live travel inventory is brittle and compute-intensive.
In Europe (Booking’s core profit center), supply is heavily fragmented across 100,000+ independent boutique hotels. These properties lack standardized APIs or the technical capability to host server-side agent protocols (like Anthropic’s MCP).
The "Merchant of Record" (MoR) Problem:
Direct booking requires taking on fraud prevention, chargeback risks, cancellation management, dynamic foreign exchange (FX), and compliance with complex regional regulations (such as the EU's DMA, DSA, and GDPR). Cohen argues frontier AI labs have no desire to become the Merchant of Record.
Customer Service & Operational Liability:
Travel is a high-stakes, non-deterministic purchase. If an AI hallucinates or an overbooking leaves a traveler stranded in a foreign city at 2 AM, tech labs will not run a 24/7 human customer service operation to rebook them.
The Intermediary Becomes the Infrastructure:
Because of the friction above, frontier AI companies will opt to plug directly into Booking.com’s aggregated APIs and live inventory feeds rather than trying to rebuild the entire plumbing of global travel.
Does Meta’s Muse Invalidate the Thesis, or Does It Hold Up?
Meta’s launch of Muse—which operates inside a cloud virtual machine (Muse Secure VM), drives a desktop browser, and checks out using Stripe Link—directly tests Cohen's thesis.
The thesis largely holds up, but Muse breaks some of Cohen's technical assumptions while validating his broader economic conclusions.
Where Muse Challenges Cohen’s Arguments
1. It Bypasses the Need for APIs or MCP Cohen argued that 100,000 independent hotels would never adopt modern server-side agent protocols. Muse proves they don't have to. Because Muse controls a virtual browser that reads the DOM, clicks buttons, and fills out forms just like a human traveler, it can theoretically execute a reservation on any hotel's standard website without that hotel building an integration.
2. It Evaporates the "Merchant of Record" Barrier Cohen asserted AI labs wouldn't facilitate direct bookings because they refuse the liability of being the Merchant of Record. Muse sidesteps this entirely by acting as a client-side proxy: it deploys single-use virtual cards generated via Stripe Link, autofilling the guest's payment directly into the merchant's existing checkout form. Meta never acts as the Merchant of Record; the hotel (or OTA) retains that liability.
Why Cohen’s Core Thesis Still Largely Holds Up Despite overcoming those technical hurdles, Muse runs squarely into the structural realities Cohen highlighted:
1. Muse Still Navigates to Booking.com
If a user instructs Muse to "find and book a 4-star boutique hotel in Florence under $250 with free cancellation and great breakfast," Muse does not attempt to scrape and parse 80 separate Italian boutique hotel websites.
Cont…

Speedwell Research retweeted
🔻TOMORROW🔻
Is $CPRT now a turn around story? Is this thesis drift?
AND
What hope does $TTD have of closing the loop and becoming a winner of connected TV?
Watch our first video podcast on YouTube tomorrow!
👇
youtube.com/@TheSynopsisPod

Speedwell Research retweeted
The Synopsis Podcast is coming to YouTube AND we are adding video!
Subscribe @ TheSynopsisPod
Be one of the first followers!
Link 👇

Speedwell Research retweeted
This is the simple explanation why it is so hard to invest on a short-term horizon or trade.

I just released my first investor letter.
You can read it here:
drewcohencapital.com/investo…

