

Active in Asset Management | trading and investing. - Probabilistic market intelligence. - Market-implied expectations, positioning & asymmetric opportunities
Joined February 2022
- Tweets9.5K
- Following1.1K
- Followers5.7K
- Likes32.1K





Pinned Tweet
Markets enter the week with the $VIX at 15.3, near the lower end of its 52-week range.
At the same time:
• U.S.–Iran headline risk remains elevated
• Breadth remains narrow
• AI leadership remains crowded
• Volatility is pricing a relatively calm week ahead
The trend remains constructive. Although some of the strong leaders like $AXTI and $LITE have seen consolidation this week.
The question is whether stability is being priced too confidently.
Asymmetric Opportunities - Week Ahead is now live.
We break down: → expected moves across $SPY, bitcoin:native , $GLD , and $USO (Oil) → volatility structure $VIX→ positioning & flows → narrative vs pricing disconnects → the key catalysts that could force repricing
Link below.

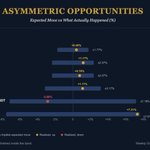
Five of six assets finished inside their options-implied range last week.
$SPY: -0.34% vs ±1.37%
$QQQ: +0.92% vs ±1.84%
$IWM: -1.66% vs ±1.96%
$BTC: +4.17% vs ±4.87%
$GLD: +0.60% vs ±2.61%
Only $USO came close to testing the edges, yet still finished at -0.70% vs ±7.05% priced.
Options priced more movement than the market ultimately delivered. This is common behavior.
Read our upcoming article on this week’s expected moves, which will be released soon to get an update on what’s next.


It seems like they have learned their lesson and are not using leverage anymore. $EWY KOSPI

$TSLA Earnings: The Options Market Is Leaning Bullish
TSLA reports soon, and options are pricing a meaningful move.
- Price: $375.52
- DTE: 2
- Expected Move: ±$21.65 (±5.8%)
- IV: 89.4%
That implies a 1 standard deviation range of $346.77 to $406.65.
Calls are trading noticeably richer than puts, with the 25-delta call at 99.3% IV versus 95.6% IV for the comparable put.

$GOOGL reports in less than an hour, and options are pricing a meaningful move.
• Price: $345.84
• DTE: 2
• Expected Move: ±$20.00 (±5.8%)
• IV: 89.1%
That implies a 1 standard deviation range of $319.45 to $374.42.
What’s interesting is the skew.
Calls are trading noticeably richer than puts, with the 25-delta call at 97.1% IV versus 95.7% IV for the comparable put.

$IBKR: The Options Market Is Leaning Slightly Defensive
IBKR is pricing an outsized near-term move, and the skew is doing something worth noting.
• Price: $95.24
• DTE: 3
• Expected Move: ±$5.67 (±5.95%)
• IV: 76.6%
That implies a 1 standard deviation range of $87.60 to $103.54.
What’s interesting is the skew. Puts are trading slightly richer than calls, with the 25-delta put at 80.0% IV versus 78.9% IV for the comparable call.
That reflects modestly stronger demand for downside protection over the next few sessions and suggests traders are willing to pay up, at the margin, to hedge against a negative surprise.

$TSM Earnings: The Options Market Is Leaning Bullish
TSM reports soon, and options are pricing a meaningful move.
• Price: $419.48
• DTE: 1
• Expected Move: ±$18.10 (±4.3%)
• IV: 65.7%
That implies a 1 standard deviation range of $402.47 to $437.21.
What's interesting is the skew. Calls are trading noticeably richer than puts, with the 25-delta call at 74% IV versus 69.2% IV for the comparable put.
That reflects stronger demand for upside exposure into earnings and suggests traders are willing to pay a premium for a positive surprise.

$AEHR Exceeded the 1-standard deviation move.
Reaching a high of $110.20 so far today.
Significant move. Let’s see what’s next.

$AEHR Earnings: Big Move Priced In
$AEHR reports after market close today, and options are pricing a major move.
Let’s take a look at the expected move.
• Price: $70.49
• DTE: 3
• Expected Move: ±$14.70 (±20.9%)
• IV: 282%
That implies a 1SD range of $51.82 to $95.89.
Looking at the wings, the 25 delta call sits above the 25 delta put, reinforcing the skew toward upside demand.
Calls are trading slightly richer than puts.
The key question: will AEHR move more than ±20.9%?

$BLK Earnings: A Relatively Modest Move Priced In
BlackRock reports in a few hours, and the options market is pricing a relatively contained move compared to many of this earnings season’s high-growth names, which we discussed before.
• Price: $1,026.00
• DTE: 2
• Expected Move: ±$42.73 (±4.2%)
• IV: 55.6%
That implies a 1 standard deviation range of $976.42 to $1,078.10.
Unlike many recent earnings names, skew is essentially flat, with calls and puts trading at almost identical implied volatilities.
The options market isn’t expressing a meaningful directional bias, instead simply pricing the magnitude of the move.

$ASML Earnings: 7.1% move implied.
ASML reports earnings today before market open.
• Current Price: $1,780.57
• DTE: 2
• Expected Move: ±$125.73 (±7.1%)
• IV: 93.8%
That implies a 1 standard deviation range of $1,637.83 to $1,935.75.
Unlike many recent earnings names, ASML is showing a slight call skew, with upside options trading richer than comparable puts.
It’s not an extreme skew, but it suggests traders are willing to pay a small premium for upside exposure into the report.
Will ASML move more than ±7.1%? That’s the question for vol traders.


$AEHR Earnings: Big Move Priced In
$AEHR reports after market close today, and options are pricing a major move.
Let’s take a look at the expected move.
• Price: $70.49
• DTE: 3
• Expected Move: ±$14.70 (±20.9%)
• IV: 282%
That implies a 1SD range of $51.82 to $95.89.
Looking at the wings, the 25 delta call sits above the 25 delta put, reinforcing the skew toward upside demand.
Calls are trading slightly richer than puts.
The key question: will AEHR move more than ±20.9%?
Asymmetric Opportunities retweeted

$UBER: The response to the Uber/Waymo Phoenix partnership end are quite dramatic imo...
Phoenix was a pilot program - that by definition is a test. It’s over because the test is complete...
Phoenix was unique: Waymo was fully established in Phoenix before partnering with Uber. It is literally ground zero for Waymo. Anyone there who wanted an AV was already using the Waymo app. The Uber partnership was a pilot likely to test user acceptance and mixed-fleet utilization. It was likely never structured to be a long term partnership.
Waymo and Uber are becoming competitors. Waymo wants to maximize its independent brand strength and awareness before Uber has a meaninful AV rollout... and they should. Losing a dozen-ish cars in Phoenix is not the end of the world. And it likely unblocks Uber to test other partners (like Zoox) in that market... we don't have pure insight into these deals for all we know there are dual direction exclusivity constraints.
Investors may be getting antsy over short-term stock stalls in price movements movement but the timeline is the timeline... Dara has been very clear about it. We are in a "show me dont tell me stage" and the show me comes late 2026 and 2027.
In the meantime, Uber is generating massive cash flow, growing, scaling the UberOne membership program, and launching new verticals.
The real rollout is late 2026/2027 and even then, AVs will be a minuscule fraction of ride-share for the next few years... you cannot flip a switch and speed up the supply chain.
The Uber Waymo pilot worked and led to rollouts in Austin and Atlanta that were likely much more fully fledged negotiation processes.
Don't see what all the fuss is about... but thats just me.

$UBER has wound down its Waymo robotaxi offering in Phoenix.
Uber said Phoenix was an intentionally limited deployment with just over a dozen vehicles, while Waymo said the program completed hundreds of thousands of trips.
Uber plans to announce a new Phoenix robotaxi partner in the future.

$MU earnings are pricing an absolutely massive move. This earnings report could potentially make or break the current AI narrative and as such the market $SPY.
2DTE options imply roughly ±$117 around a $1,016 stock price.
IV is sitting near 193%. That creates an interesting question: Is the market correctly pricing one of the hottest AI/semiconductor earnings events…
or is the event premium now rich enough to sell?
This week’s Asymmetric Setups piece looks at two ways to think about it: (see link in the comments) ⬇️
The short straddle:
→ maximum premium, maximum gamma risk.
The $905/$1120 short strangle
→ less premium, more room, still very real tail risk.
This is not an income trade. It is a short-volatility trade for more experienced traders..
If $MU stays inside the implied range, IV crush can pay quickly. If it gaps beyond the range and keeps moving, the losses can be significant.
The edge only exists if the premium is too high relative to the distribution that actually realizes.
Full breakdown in today’s Asymmetric Setups article for FREE.

At Apollo’s $APO flagship retail private credit fund, investors requested redemptions equal to 17% of NAV last quarter. Only a fraction got out. The rest hit the fund’s 5% quarterly gate.
Across nine major private credit funds (~$200B), investors requested nearly $15B back in Q2, with less than 40% redeemed.
The structure is doing exactly what it was designed to do.
When markets are calm, illiquidity is a feature. When investors want out, it becomes a constraint.


