
Moonlighting as an Indian public markets investor. DYOD. Nothing is Investment recommendations.
Joined December 2020
- Tweets84
- Following1K
- Followers369
- Likes26






Pinned Tweet
Inspired by @persistencecap @9onecapital @SamitVartak @amitmantri @2point2capital @MGSolidarity and their efforts to discuss ideas in depth on X, wanted to share our thesis on PVR INOX. 🧵
Disclaimer: may hold a position. Academic discussion only, not investment advice.
Razor Capital retweeted
What we watch: the small-business book, rivals moving into its ticket size, Andhra Pradesh at 43% of AUM, and growth fading.
Each one runs through the multiple. On its own, none costs more than ~2 points of IRR at a 2.75x exit.

Razor Capital retweeted
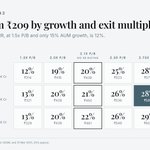
At a 2.75x exit, still 28% below the median, that is a ~28% IRR from ₹209.
With no re-rating at all, ~21%. The worst case on our grid, 1.5x book and only 15% growth, is ~12%.

Razor Capital retweeted
Our base case sits below guidance: 17.5% growth (guide 22–24%), yields down 75 bps, funding cost up 25 bps, credit cost 0.55%.
Book value per share goes from ₹101 to ₹214 by FY31.

Razor Capital retweeted
Four reasons, none about the franchise:
PE exit: WestBridge went ~37% to 4%, all above ₹290
Credit cost up to ~0.5–0.6%, partly a stricter write-off policy
Growth slowed to 21%, above the industry’s 19–21%
Debt costs ~70 bps more than peers; the gap is closing

Razor Capital retweeted
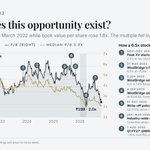
So why does this great business trade at 2.1x?
The price is down 45% since March 2022 while book value per share rose 1.8x. The whole affordable housing group de-rated, and Aptus de-rated the most, along with Aavas.

Razor Capital retweeted
And the model travels. Tamil Nadu went from 72% to 31% of AUM as Andhra Pradesh became the largest state. Of ten regional lenders we looked at, none moved faster without an acquisition.

Razor Capital retweeted
It is run by its founder. M Anandan spent 20 years at Cholamandalam before starting Aptus in 2010.
ROE has gone from 14.5% to 20.1% over FY21–26. The founder family holds 23.9%, unchanged through the PE exits.

Razor Capital retweeted
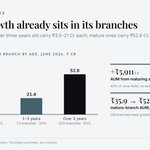
Growth is already sitting in the branches. 147 branches under three years old carry ₹3.5–21 Cr of AUM each; mature ones carry ₹52.6 Cr.
Maturing alone adds ~₹5,900 Cr, about 43% of today’s AUM.

Razor Capital retweeted
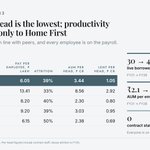
Cost per head is the lowest in the group (₹6.05 lakh), staff turnover is in line with peers, and everyone is on the payroll.
Live borrowers per employee went from 30 to 49 over FY21–26.

Razor Capital retweeted
The underwriting has been tested: IL&FS, COVID, 250 bps of rate hikes, small-borrower stress.
Seven years, four shocks, ROA never below 7.4%.

Razor Capital retweeted
And it does not give up credit quality for it. Credit cost averaged 0.44% of AUM over FY21–26. Gross NPA has never passed 1.7%. Average loan-to-value is ~40%, against 52–60% at peers.

Razor Capital retweeted
The higher ROA comes from a higher yield and lower opex: 17.2% on loans against 12.8–14.8% at peers, and opex of 2.7% of assets against 2.7–4.5%.

Razor Capital retweeted
And with the lowest leverage among its peers: 2.6x assets to equity, against 3.0–4.2x.
7.8% ROA × 2.6x = 20% ROE. Low leverage leaves room to absorb a macro or industry shock.

Razor Capital retweeted
While earning 2x the industry’s ROA: 7.8% in FY26, against 3.4% for affordable housing finance companies (CARE). The next-best listed peer is at 5.8%.

Razor Capital retweeted
The business has grown at 25%+ a year over FY21–26:
AUM: 26.4%
Disbursements: 25.3%
Live borrowers: 26.5%
Branches grew 12.3% a year, so each branch now serves 1.8x the borrowers it did in FY21.

Razor Capital retweeted
Aptus lends to self-employed families in Andhra Pradesh, Tamil Nadu, Telangana and Karnataka, secured on their homes. About ₹7 lakh outstanding per borrower.
Today: ₹209, 2.1x book, 11.1x earnings. Median since listing: 3.8x book.

Razor Capital retweeted
It has happened before in Indian NBFCs:
Gold loans, 2013: Muthoot fell to 0.9x book, back to 2.0x in eight months.
Vehicle finance, 2020: Chola went from 1.6x to 5.7x within a year.
Microfinance: CreditAccess halved twice and re-rated twice.


Razor Capital retweeted
One of our favourite mental models: when the market de-rates an entire industry, it throws the baby out with the bathwater.
The highest-quality names often fall more than the industry, then re-rate first and come out stronger.
We think Aptus Value Housing is one. A 🧵. Please share your thoughts, and happy to discuss this!
This is just for academic purposes, not a recommendation. Please do your own research and diligence.

Razor Capital retweeted
7/ Content and advertising remain the test.
Industry box office rose 23% to ₹4,443cr, versus 18% growth in PVR INOX ticket sales. Management points to a mix favouring mass-market and single-screen hits.
Ad income grew only 4.3% to ₹131cr.
The company's H2 slate includes Ramayana, The Hunger Games, Avengers: Doomsday and King, with Love & War in Q4. That's management's pipeline, not guaranteed collections.
Verdict: MIXED. H1 shows the earnings power when content works; weak ads and dependence on the next slate remain risks.
1/ PVR INOX Q2 FY27 vs our thesis.
Pre-Ind AS 116 (after rent): total income ₹2,133cr (+17%), EBITDA ₹475cr (+44%), PAT ₹273cr (+111%).
That includes ₹28cr of other income, mainly old provision reversals, and ₹21cr lower depreciation from longer asset lives. Excluding both, pre-tax profit still roughly doubled YoY (my calculation).
Verdict: SUPPORTS.

Inspired by @persistencecap @9onecapital @SamitVartak @amitmantri @2point2capital @MGSolidarity and their efforts to discuss ideas in depth on X, wanted to share our thesis on PVR INOX. 🧵
Disclaimer: may hold a position. Academic discussion only, not investment advice.
6/ Returns on capital is improving.
Company ROCE, pre-Ind AS 116 and excluding merger goodwill, reached 16.5% on a trailing-12-month basis vs 10.2% in FY26 and ~13% pre-COVID.
The EBIT used includes other income. And excluding ₹5,737cr of goodwill makes this a measure of operating capital efficiency, not the return on all capital invested in the merger.
Verdict: SUPPORTS the cash flow generation lever
7/ Content and advertising remain the test.
Industry box office rose 23% to ₹4,443cr, versus 18% growth in PVR INOX ticket sales. Management points to a mix favouring mass-market and single-screen hits.
Ad income grew only 4.3% to ₹131cr.
The company's H2 slate includes Ramayana, The Hunger Games, Avengers: Doomsday and King, with Love & War in Q4. That's management's pipeline, not guaranteed collections.
Verdict: MIXED. H1 shows the earnings power when content works; weak ads and dependence on the next slate remain risks.