

Long-term investor. Looking for businesses I can own forever, knowing most don’t deserve that
Joined July 2022
- Tweets2.2K
- Following579
- Followers1.9K
- Likes15.4K




"For the full year 2026, Amphenol expects sales to be in the range of $36.9 billion-$37.1 billion, representing an approximately 60% increase [YoY], while Adjusted Diluted EPS is expected to be in the range of $2.82-$2.84, representing an approximately 70% increase.."
$APH

Moody's anticipates >$1 trillion in hyperscaler capex in 2027:
"They [ratings analysts] expect that to grow to somewhere $1 trillion or more. What that tells you is we expect that there will be continued growth in the hyperscaler issuance and AI infrastructure build-out"
$MCO

My $ABG.OL shares are ~flat since I first bought around 2 years ago, excluding a 7.5% dividend yield
The stock hasn't worked even though corporate financing + M&A ⬆️ since the '22-'24 downcycle
2-yr revenue growth +32.6%
2-yr EPS growth +37.7%
Stock trades at 9.7x trailing EPS
Zuck: “Muse is very compute-intensive to run, but we expect to improve its cost efficiency by more than 10x in the next year, which will enable it to be profitable once the revenue lines are at scale.“
$META


Morningstar: "[W]e continue to view ads, new products, and potentially subscriptions as much more enticing areas for AI monetization for Meta when compared with enterprise wallet share, an area in which the firm has little to no experience."
$META

"As a result, we will close approximately 250 coffeehouses later this week. This represents approximately 1% of our more than 18,000 North America coffeehouses."
$SBUX


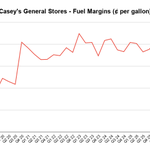
$CASY CEO: "We've taken significant share in fuel... with higher fuel prices, we're seeing exactly the type of behavior that we would expect to see. Fewer gallons per trip, but more trips made, which ultimately accrues to our benefit if we have more people coming to the store."

$MELI already +11% since the stock sold off after last earnings call
Slightly discouraging to see a stock move like that as I'm looking into it. But I also know that's an irrational way to look at it if the opportunity is still there
"We have a once-in-a-generation opportunity to transform how hundreds of millions of Latin Americans shop, pay and access financial services..
[W]e expect today's investments to compound into the same kind of structural advantages that our past investments have created."
$MELI

“Have you ever read management interviews that claim they aren’t innovative, don’t have the best business leaders, aren’t ‘leveraging’ technology…
Excellence is rare in this world, including the business world. You just won’t know it if you are relying on management interviews”

$MUSA: "New store growth will be closer to 45 new stores...While the stores are costing more, they're actually higher returning due to this fuel margin impact"
Murphy USA opened 51 stores last year, so 45 new locations in 2026 would be its 2nd fastest pace of openings since 2017

FY26 guide less than two months ago was for 7-9% organic sales growth and 7-10% EBIT growth
Now, 4-5% sales growth and low single digit EBIT growth
$HONA


Brian Niccol: "Sales growth in Q3 was broad-based across generations and income groups, and across both Starbucks Rewards members and non-members, even with the continued pressure on US consumer sentiment."
FYI, no YoY comp as $SBUX paused active member reporting in FY25

After two years of declines, Starbucks is expecting at least 6% growth in comparable store sales in FY26
Another positive is that a majority of the 8% Q3 SSS growth came from transactions (4.5%) compared to price (3.5%)
$SBUX

"For the 3rd quarter of 2026, Amphenol expects sales to be in the range of $9.3-$9.4 billion, representing a 50%-52% increase over the prior year. Adj. Diluted EPS is expected to be in the range of $1.40-$1.42, representing a 51%-53% increase from the 3rd quarter of 2025."
$APH
Morningstar on $TSCO: "We view shares as attractive and think the market is pricing in perpetual, rather than transitory, weakness in comps...We don’t see much change to our long-term prognosis"
Stock is now trading at ~16x trailing EPS