

Growth-focused stock picker
Canada
Joined July 2025
- Tweets1.3K
- Following92
- Followers670
- Likes2.6K




Pinned Tweet
The $APP Thesis in One Post:
1. Fundamentals
• Revenue: $1.924B (+53% YoY) | Management guided 20%–30%+ baseline CAGR
• Adj. EBITDA Margin: 84% ($1.614B)
• Free Cash Flow: $863.3M
• Diluted EPS: $3.76 (+57% YoY)
2. Valuation
• Forward P/E: ~14x
• P/S (NTM): 15x
3. The Core Business / MOAT
• MAX (The Supply Moat & Fee Arbitrage): AppLovin owns MAX, the core mediation layer controlling mobile app ad supply. When external DSPs (like Meta or Google) bid on inventory, they are charged standard platform mediation fees (5%–15%) and bid blindly with delayed feedback loops. Because AppLovin owns the pipe, they don’t charge themselves fees. This zero-friction advantage lowers Axon’s net clearing cost threshold, allowing them to submit the highest net-clearing bid and win high-value impressions while capturing sub-100ms real-time auction telemetry.
• AXON (The Compounding AI Demand Engine): Running directly on top of MAX’s live telemetry, Axon 2.0 evaluates 2.5M+ requests/sec across a single unified auction layer. Instead of selling brand awareness, it operates on a pure pay-for-performance/ROAS model. High-frequency deep learning predicts conversion value with unmatched precision creating a closed data flywheel where every impression won improves future model accuracy.
• AppLovin Ads (The Open Self-Serve Inflection): AppLovin has generated billions in run-rate revenue while operating as a restricted, managed-only platform for a small pool of accounts. With AppLovin Ads now open globally via self-serve and direct Shopify integrations, millions of DTC merchants, web apps, and autonomous AI media buyers can deploy spend programmatically on demand with zero onboarding friction.
Fundamentals ✅
Valuation ✅
Core Business ✅
Im long $APP


Aria is entirely correct.
This is an official chart published by AppLovin related to population growth vs. audience growth.
Mobile gamers almost perfectly mirror the general U.S. population across every age bracket and gender split. These aren't just kids; they are everyday American adults, professionals, homeowners, and core consumers working full-time jobs.
When you buy mobile gaming inventory through AppLovin, you are buying high-intent, mass-market consumer reach that directly scales across mainstream America.
$APP


“Even on a lower budget if you crack it right you can get good results.”
This advertiser spent $15k in the span of 7 days and the campaign averaged a 169.82% D0 ROAS and a 216.14% D7 ROAS.
In other words; $15k in ad spend returned $33k of ad spend.
$APP


“Less than 1% of advertisers in the world use @AppLovin yet we have north of $11B of annual ad spend on the platform and reach over a billion users daily.”
— Rafael Vivas, Growth Marketing
I mean how are you not bullish…
$APP

Less than 1% of advertisers in the world use @AppLovin yet we have north of $11B of annual ad spend on the platform and reach over a billion users daily.
In baseball terms, the players just walked onto the field for the national anthem. The first inning hasn’t even started yet.


$NFLX
When a company blatantly says they're doubling advertising revenue YoY, you pay attention.
• Ad revenue scaling 100% from $1.5B to $3.0B
• Advertiser base up +70% YoY (>4,000 active clients)
• Ad-tier captures over 60% of new sign-ups in active markets
• High-margin programmatic platform + live sports driving premium CPMs
The market still views Netflix as a mature streaming subscription.

Netflix Advertising MAUs:
- Nov 2025: 190 million
- May 2026: 250 million
Increase of +32% in 6 months. While 60% of all new sign ups are on the ads plan.
That's larger than the U.S. population in 4 years.
$NFLX


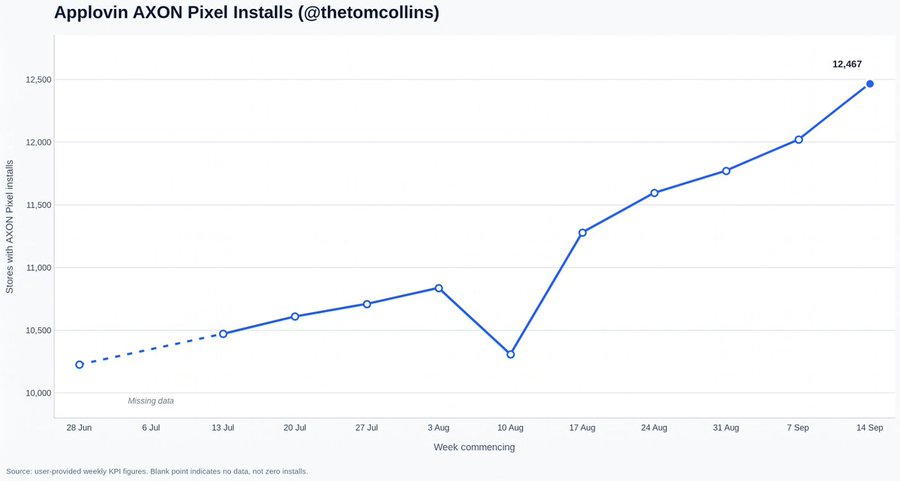
AppLovin's AXON pixels continue to climb.
+3.27% WoW.
An AXON Pixel is a tracking snippet placed on e-commerce storefronts to log checkout events and purchase values.
This conversion telemetry feeds directly back into AppLovin’s AI bidding models, validating merchant ROAS and sharpening predictive ad targeting across the network.
Pixels increase > model gets smarter > ROAS improves
$APP


"In December, we reached a run rate of roughly $1 billion a year of gross advertiser spend in the e-commerce category alone from around 600 customers."
— Adam Foroughi, CEO of AppLovin
Think about it, if 600 advertisers generated a $1B run rate in gross spend, meaning an average of $1.6M spend. That volume occurred under strict spend minimums and manual onboarding bottlenecks.
Expanding their services to self-serve tools opens the exact same performance engine to hundreds of thousands of merchants.
Let the flywheel spin.
$APP


$APP
At the Nasdaq Investor Conference, AppLovin management outlined what a 10-year, 25% annual growth trajectory looks like:
• Over $200 Billion in gross advertiser spend
• Over $70 Billion in net platform revenue
• Operating inside a $1 Trillion+ global digital ad TAM
Reaching $200B+ in gross media spend means AppLovin only needs to capture roughly ~15% to 20% of global performance ad budgets.
They currenttly capture around ~1% of budgets.


