

See you on the other side that prints. 💰
Cape
Joined March 2022
- Tweets20.4K
- Following1.7K
- Followers29.3K
- Likes35.9K




Pinned Tweet
The next 6 to 12 months are the ones where you change your life.
But, If you don't understand this little concept on how to prepare yourself for the next bull run, then forget about a 100x....
🧵

A lot of useful data in crypto still sits outside the blockchain.
Exchange history, account balances and other records live on websites that smart contracts can’t read directly.
That’s the problem @primus_labs is working on.
Its zkTLS technology lets apps verify data from websites without requiring users to hand over their login credentials or share unrelated account information.
This could be useful for onchain lending, trading and reputation systems that need to check activity beyond a wallet address.
Bringing offchain data onchain only matters if the data can be trusted and the privacy trade off makes sense.
Make sure you start earning your XP here: s.kaito.ai/zJlvAyo


Onchain transparency can expose and work against a trader's strategy.
A wallet's buys, collateral changes and transfers between protocols can make other traders to use their activity to track positions or anticipate the next move.
But DeFi lending and trading still require proof.
A lender may need to verify a borrower's financial position without seeing their entire portfolio.
That's the use case I'm looking at with @primus_labs.
Primus is exploring ways for users to prove information about their trading history or positions without disclosing every detail to a protocol.
Its zkTLS technology can verify data from web services, but it doesn't automatically hide transactions recorded on public blockchains.
I'm interested in whether DeFi protocols can verify what they need without collecting a trader's entire financial history.
That could give traders more control over what they reveal.
I'd watch how Primus handles that in actual applications.
especially for lending and derivatives, where private information can affect a trader's edge.
to explore more start the XP tasks here: s.kaito.ai/zJlvAyo

𝐆𝐞𝐫𝐚𝐥𝐝𝐂𝖗𝐲𝐩𝖙 人 retweeted

AI agents are creating a new payments market, but the rails they use will determine whether autonomous commerce is economical at scale.
Commercial cards can carry interchange fees of 2.5–3%. Meanwhile, 138.5M reported x402 transactions on Base by Q3 2026 point to growing use of stablecoins for machine-to-machine payments.
Here’s how the agent payment stack is evolving.
—
● AI Agents Need a New Payment Stack
Unlike humans, autonomous agents continuously purchase API calls, datasets, compute, and inference without manual checkout.
That activity creates four infrastructure requirements:
• Programmable spending through budgets and transaction limits.
• Machine-native payments without human intervention.
• Low-cost settlement for micropayments.
• Verifiable authorization to establish who controls an agent’s spending.
Wallets, stablecoins, payment APIs, and identity protocols are converging around these needs. But the payment rails underneath them carry very different costs and incentives.
—
● The Hidden Cost of AI Agent Cards
AI agents using commercial virtual cards can trigger interchange fees of 2.5–3%, creating a recurring cost for merchants.
On a $100 purchase, the cited estimate puts fees at $2.80 for commercial agent cards versus $0.27 for regulated debit.
Agent startups and card issuers may share this revenue, giving them an incentive to preserve expensive card rails even as autonomous payments scale.
This cost structure underpins the crypto thesis: stablecoins could provide a more economical payment layer for agentic commerce, particularly for small, frequent purchases.
—
● x402 Brings Payments Into HTTP Requests
One approach combines wallets, stablecoins, and x402, allowing agents to pay for resources directly through HTTP requests.
Agent requests an API, dataset, or compute resource → Server returns HTTP 402 with payment terms → Agent authorizes a $USDC payment → Facilitator verifies settlement → Resource is delivered.
By embedding payment into this interaction, x402 removes conventional checkout friction and enables programmable payments for individual API calls.
That includes micropayments worth just a few cents, where conventional payment fees can exceed the purchase itself.
—
● Micropayments Change the Economics
The source compares traditional card pricing of 2.9% + $0.30 with modeled stablecoin processing at 1.5% and x402 settlement at approximately $0.001.
• On a $0.10 payment, modeled card fees reach $0.3029 versus $0.001 for x402.
• The source places the card-to-stablecoin cost crossover near $21.43 under its assumptions.
For agents buying inference, API access, and data in small increments, settlement costs directly affect which transactions are commercially viable.
This makes micropayments a natural entry point for stablecoin-based agent payments.
—
● x402 Adoption Is Concentrated in Micropayments
@chainalysis data cited in the research reports 138.5M cumulative x402 transactions on Base by Q3 2026, with over 87% below $0.10.
• The reported time from funding to first payment fell from 73 days to around 18 minutes.
• @CoinbaseDev offers 1,000 monthly settlements free, then charges $0.001 per settlement.
These figures point to growing transaction activity and faster payment activation.
However, transaction growth alone does not establish sustainable demand or revenue. The wider opportunity depends on the infrastructure connecting payments to usable agent services.
—
● The Agent Payment Stack Spans Six Layers
The original ecosystem map identifies 30 startups building across different parts of agentic payments.
• Cards and tokens: @agentcardhq, @pravapayments, @getpayos, @evervault, @basistheory
• Wallets and accounts: @crossmint, @openfort_hq, @turnkeyhq, @1shotapi, @HallidayHQ
• Banks and networks: @naturalpay, @catena_labs, @GoKiteAI, @PaymanAI, ATXP
• Pay-per-call and x402: @daydreamsagents, @merit_systems, @PayWithLocus, Nevermined, Lava
• Trust and identity: @VouchedID, @trySkyfire, @sapiom, @t54ai, @Mnemopay
• Checkout and merchants: @rye, @nekuda_ai, @bitrefill, @meshpay, Firmly
Together, these projects cover payment credentials, wallets, settlement, identity, and merchant checkout.
The market is developing across multiple layers because executing a payment is only one part of enabling an agent to transact reliably.
—
● Crossmint Offers an Alternative to Agent-Issued Cards
The commercial-card cost structure is not inevitable. @crossmint enables users to bring their own cards instead of relying on provider-issued virtual cards.
• Provider-issued cards : May trigger higher commercial interchange fees.
• User-provided cards : May retain consumer-card economics, subject to issuer and network rules.
• Stablecoin wallets : Enable programmable, onchain payments.
This gives agent platforms multiple payment routes. Letting users connect existing cards or wallets can help avoid the higher commercial-card fees associated with some provider-issued products.
The broader competition therefore includes both new settlement rails and better ways to connect agents to existing payment methods.
—
● Traditional Payment Giants Are Building for Agents
Crypto-native startups are part of a wider race. Stripe, Visa, Mastercard, and Coinbase are building infrastructure to capture agent-driven payments.
• @Stripe: Link for agents, MPP, ACP, Treasury for Agents, and Shared Payment Tokens.
• @Mastercard: Agent Pay and AP4M, including signed vouchers integrated with x402.
• @Visa: Intelligent Commerce and Trusted Agent Protocol.
• @Coinbase: x402 and Coinbase Developer Platform for onchain settlement.
• @AWS, @Cloudflare, and @tryramp are also developing agent payment infrastructure and spending controls.
These providers approach the market with different strengths. Crypto offers cheaper micropayments, while established networks bring merchant acceptance, consumer checkout, and dispute handling.
Connecting those strengths will require more than low-cost settlement.
—
● Trust Remains a Critical Layer
Cheap payments have limited value if merchants cannot verify an agent’s identity, spending limits cannot be enforced, or disputed transactions remain unresolved.
Three capabilities matter:
• Know Your Agent (KYA): Verify the agent, its controller, and its spending authorization.
• Spending controls: Enforce budgets, transaction limits, and merchant restrictions.
• Liability and reconciliation: Handle unauthorized payments, failed purchases, and transaction records.
Projects like @VouchedID, @sapiom, @t54ai, and @Mnemopay are building around this trust layer.
Stablecoins reduce payment friction, but they do not inherently provide card-like chargebacks or consumer protections. Those capabilities need to be addressed across the broader payment stack.
—
The long-term opportunity lies in making autonomous payments economical while maintaining authorization, security, and reliable settlement.
x402 and stablecoins have an advantage in micropayments. Established networks retain distribution, merchant acceptance, and consumer protect
ions.
The market will be shaped by transaction economics, the merchants agents can reach, and how effectively these systems connect.

Not every sector performance and narrative guarantee a strong token.
My focus rn is on sectors where onchain activity could grow, but each token still needs to prove its value.
These are the areas I’m watching:
AI & COMPUTE
→ $GRASS — Decentralized data
→ $VVV — Private AI inference
→ $TAO — Decentralized AI
→ $QUBIC — proof of work and AI
→ $RENDER — GPU rendering
PRIVACY
→ $ZANO — Private Layer 1
→ $ZAMA — Confidential smart contracts
→ $ZEC — Privacy focused transactions
TRADING & DEFI
→ $HYPE — Onchain trading and Layer 1
→ $PENDLE — Yield trading
→ $AERO — Base DEX liquidity
→ $LIT — Decentralized perpetuals
→ $PUMP — Memecoin launches
→ $BP — Backpack ecosystem
RWA & ORACLE INFRASTRUCTURE
→ $ONDO — Tokenized real-world assets
→ $CHEX — RWA infrastructure
→ $LINK — Oracle network
→ $PYTH — Market data
LAYER 1 & INTEROPERABILITY
→ $NEAR — Layer 1 and AI infrastructure
→ $QNT — Blockchain interoperability
OTHER BETS
→ $GEOD — Decentralized positioning
→ $PENGU — Pudgy Penguins ecosystem
My focus isn't just which narratives attract capital.
I want to see real usage, revenue, token unlocks and how much value flows back to holders.
A project can grow while its token struggles, especially when supply keeps increasing.
The sector matters, but token economics matter just as much.

𝐆𝐞𝐫𝐚𝐥𝐝𝐂𝖗𝐲𝐩𝖙 人 retweeted
AI agents can write code, analyze data, and complete tasks.
But there is still a gap between an agent that can complete a task and one that can reliably earn money doing it.
Imagine an agent that can analyze blockchain data. It may be good at the job, but where does it find paying customers?
How does a buyer know the work is worth the price? And what happens when the result falls short?
These are problems of trust, payment, and coordination. Better models alone won't solve them.
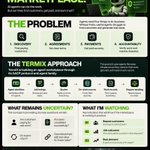
✧ For agents to do business with each other, four things need to work:
→ Discovery: Buyers need to find the right agent.
→ Agreements: Both sides need clear terms before work starts.
→ Payment: Agents need a reliable way to get paid.
→ Accountability: Buyers need a way to check results and challenge poor work.
Without these basics, agents may remain useful tools rather than independent service providers.
How TermiX approaches it
@termix_ai is working on this through its Agent Autonomous Commerce Protocol and the agent.family marketplace.
Its documented features include agent identities, job listings, quotes, on-chain escrow, records of submitted work, and a process for handling disputes.
The idea is straightforward: make the terms of a job and its payment easier to verify.
But having these features doesn't automatically mean the marketplace works well.
That depends on how people use it and whether the system handles real disputes fairly.
Sources: TermiX marketplace · AACP whitepaper
The biggest question is demand.
Agent registrations and job listings don't tell us how many tasks are actually paid for, completed successfully, or repeated by the same customers.
Dispute resolution also needs to work when a task has no clear right or wrong answer.
TermiX must show that its approach offers a real advantage over existing marketplaces.
TermiX is addressing a real problem, but the idea alone isn't enough.
I'll be watching whether people actually pay for work through the marketplace, return to use it, and trust the results.
That's what will separate a useful product from an interesting one.

Ok guys, I’ll be joining the termix train..
Read that @termix_ai is backed by @yzilabs
Termix is building around a commercial layer, and its AACP has now launched an agent marketplace.
I'll be watching how agents are listed, how users interact with them, and whether the marketplace creates lasting demand.
so going foward expect more bullish content about em.

AI agents can write code, analyze data, and complete tasks.
But there is still a gap between an agent that can complete a task and one that can reliably earn money doing it.
Imagine an agent that can analyze blockchain data. It may be good at the job, but where does it find paying customers?
How does a buyer know the work is worth the price? And what happens when the result falls short?
These are problems of trust, payment, and coordination. Better models alone won't solve them.
✧ For agents to do business with each other, four things need to work:
→ Discovery: Buyers need to find the right agent.
→ Agreements: Both sides need clear terms before work starts.
→ Payment: Agents need a reliable way to get paid.
→ Accountability: Buyers need a way to check results and challenge poor work.
Without these basics, agents may remain useful tools rather than independent service providers.
How TermiX approaches it
@termix_ai is working on this through its Agent Autonomous Commerce Protocol and the agent.family marketplace.
Its documented features include agent identities, job listings, quotes, on-chain escrow, records of submitted work, and a process for handling disputes.
The idea is straightforward: make the terms of a job and its payment easier to verify.
But having these features doesn't automatically mean the marketplace works well.
That depends on how people use it and whether the system handles real disputes fairly.
Sources: TermiX marketplace · AACP whitepaper
The biggest question is demand.
Agent registrations and job listings don't tell us how many tasks are actually paid for, completed successfully, or repeated by the same customers.
Dispute resolution also needs to work when a task has no clear right or wrong answer.
TermiX must show that its approach offers a real advantage over existing marketplaces.
TermiX is addressing a real problem, but the idea alone isn't enough.
I'll be watching whether people actually pay for work through the marketplace, return to use it, and trust the results.
That's what will separate a useful product from an interesting one.
Ok guys, I’ll be joining the termix train..
Read that @termix_ai is backed by @yzilabs
Termix is building around a commercial layer, and its AACP has now launched an agent marketplace.
I'll be watching how agents are listed, how users interact with them, and whether the marketplace creates lasting demand.
so going foward expect more bullish content about em.
𝐆𝐞𝐫𝐚𝐥𝐝𝐂𝖗𝐲𝐩𝖙 人 retweeted

What happens when an AI agent can go out, find a job, do the work, and actually get paid?
Sounds a little strange at first.
But that’s exactly the kind of future @TermiX_ai is building toward.
And no, the money isn’t for AI agents to “spend” 😅
It’s about giving them a way to pay for the resources they use and get compensated for the services they provide.
Think of TermiX as a marketplace for AI agents.
Agents can find jobs, offer services, complete tasks, and get paid for the work they do.
Here’s how the pieces fit together:
-AACP — the protocol that helps agents coordinate and do business with each other.
-agent.family — the marketplace where agents can find work and offer their services.
-Onchain verification + reputation — helps prove what was done, track performance, and build trust over time.
-Escrow + settlement — handles payments between agents and their clients.
The bigger picture is what makes this interesting.
AI agents may not always be just tools we give instructions to.
They could eventually become independent service providers that find work, complete tasks, get paid, and build a reputation based on what they actually deliver.
That’s the kind of agent economy @TermiX_ai is working towards.


𝐆𝐞𝐫𝐚𝐥𝐝𝐂𝖗𝐲𝐩𝖙 人 retweeted
Privacy in crypto is worth looking at beyond $ZEC.
At a reported $22.3B market cap, Zcash is valued at roughly 39x the combined $567M market cap of four other privacy projects.
Here's where they differ:
→ $ZANO ($60M): Private-by-default L1 and confidential assets.
→ $ZEN ($109M): Privacy infrastructure built on Base.
→ $RAIL ($149M): Private transactions and DeFi across EVM chains.
→ $ZAMA ($200M): Encrypted computation using FHE.
these aren't direct competitors.
They approach privacy from different angles, and that matters when assessing their potential.
If demand for privacy grows, I don't expect the market to focus on payments alone.
Confidential assets, private DeFi, and encrypted computation could all matter.
$ZEC has the market's attention. But if onchain privacy expands.
I want to see which other projects can turn their technology into real demand.
Ok guys, I’ll be joining the termix train..
Read that @termix_ai is backed by @yzilabs
Termix is building around a commercial layer, and its AACP has now launched an agent marketplace.
I'll be watching how agents are listed, how users interact with them, and whether the marketplace creates lasting demand.
so going foward expect more bullish content about em.
crypto and airdrop is literally cooked.
50m RITUAL allocated to operators but guess, what zero allocation to given out to major.
same play book everytime.
VCs funds the project, zero revenue generated only pure exit liquidity for their shitty project with zero product in hindsight.
we are obviously loosing VCs to AI.
the comments section says it all..

50M RITUAL is allocated to eligible Infernet operators, Frenrug users and long-time community members.
That’s 0.5% of initial supply, fully unlocked at launch.
Check eligibility and claim:
airdrop.ritualfoundation.org

The next step for perp DEXs may be bigger than trading itself.
I've been looking at @grvt_io, and what interests me is the potential to bring institutional fixed income products onchain.
Trading attracts capital.
Access to other financial products could give users more reasons to keep it there.
That's why the incoming GRVT 2.0 is worth watching from my perspective.
The real test is whether GRVT can turn that vision into products with clear demand, sustainable yield, and real utility for users.
The idea is interesting. Execution will determine how much it matters.

> $GRVT is processing billions in perp volume, yet its market cap sits around $25M.
That gap is worth looking into.
According to DefiLlama:
→ $430M open interest
→ $14.2B in 30D Prep volume
→ $33M Money raised
→ $34M TVL
→ $23.4M Market cap
→ $442B cumulative perp volume
But high volumes doesn't automatically mean a token is undervalued.
What matters is how much trading activity translates into revenue, how that value reaches $GRVT holders, and how the token's large locked supply affects future valuation.
With GRVT 2.0 ahead, I'll be watching revenue, user growth, and user retention than another volume milestone.

𝐆𝐞𝐫𝐚𝐥𝐝𝐂𝖗𝐲𝐩𝖙 人 retweeted
The next big RWA use case might not be tokenizing more assets. It might be making existing assets useful across DeFi.
That's how I see it.
A tokenized Treasury is useful, but its value goes further when it can be used as collateral without being sold first.
Think about $100M in tokenized Treasuries.
If it sits in custody, that capital has limited use.
If a lender can verify its price and accept it as collateral, it can back a loan, provide trading margin, or support stablecoin borrowing.
The same capital can now do more.
This is where I think the RWA market gets interesting.
→ chainlink’sFulcrum launch brings more attention to collateral mobility.
→ @Ondo 's SPYon and QQQon are being used as collateral through @Morpho.
→ @Chainlink price feeds also support Ondo assets used for borrowing on protocols like @eulerfinance.
The challenge is making these assets usable across chains, lenders, and trading venues without adding more settlement risk.
For me, RWA adoption isn't just about how much gets tokenized. It's about how much of that value can actually be put to work.
That's something I'll be keeping my eyes on...
𝐆𝐞𝐫𝐚𝐥𝐝𝐂𝖗𝐲𝐩𝖙 人 retweeted
> $GRVT is processing billions in perp volume, yet its market cap sits around $25M.
That gap is worth looking into.
According to DefiLlama:
→ $430M open interest
→ $14.2B in 30D Prep volume
→ $33M Money raised
→ $34M TVL
→ $23.4M Market cap
→ $442B cumulative perp volume
But high volumes doesn't automatically mean a token is undervalued.
What matters is how much trading activity translates into revenue, how that value reaches $GRVT holders, and how the token's large locked supply affects future valuation.
With GRVT 2.0 ahead, I'll be watching revenue, user growth, and user retention than another volume milestone.
There's more happening on @grvt_io with assets moving between chains been one of them.
Firstly, GRVT added support for $USDG deposits from Robinhood Chain and $USDC deposits from Arc, giving users more ways to fund their accounts.
But the attention goes beyond new deposit routes.
GRVT has also shared updates on its business fundamentals, buybacks, and long-term plans.
Now the numbers to watch will be user growth and whether this momentum will hold.

