

Founder @3F_Research | PM $RAA | $FCTE | Formerly with Ned Davis Research | Recovering Attorney (step 4) - Not investment advice
FL
Joined February 2014
- Tweets10.5K
- Following1.9K
- Followers79.5K
- Likes16.4K





Pinned Tweet
Historically, during soft landings, the S&P 500 rips in 6 months leading into a first Fed cut.
Would put the market at 5,200 by May...
First time speaking w/ the great @ScottWapnerCNBC was a blast!


Bears out discussing AI's vulnerability to a VC funding retrenchment
IF VC funding tracks the last hike cycle, ~25% of lab ARR is at risk
However, the likelihood that the current tightening tracks 2022 is v low + ex-labs VC funding is below last cycle's peak (excerpt 9/17 3FR)

more below...
xitter.cf/WarrenPies/status/2107…

Warren Pies retweeted
New report out to 3FR clients discussing:
-Credit spreads (Caa) blowing out.
-Weak breadth has been bullish in the AI-era.
-Datacenter supply projections for 2027...no signs of a slowdown.
-Lab ARR fears.

Good thread from Gavin citing some of our work.
As he points out, almost all IRR calcs assume a decline in GPU rents...the math gets wild if rents are RISING as they have been this year.


1) Trying again.
TLDR: Everyone can win. Open-source, frontier labs, infrastructure, applications and most importantly the American people.
I understand all of the jitters about Anthropic losing share, real rates, spreads and second derivatives. Still think the most likely future outcome is a hybrid, multi-model future where almost everyone wins, open-weight tokens are likely the overwhelming majority of tokens, the dominant frontier model companies still do well albeit perhaps not the outcome that seemed possible in May and AI infrastructure/applications benefit immensely from the increased fragmentation, competition and lower margins at the model layer.
Lower margins at the model layer mechanically drive higher compute demand as long as someone is willing to pay for the training. And Jensen is obviously willing to be the “trainer of last resort.” As below-market compute contracts signed in 24/25 roll-off and reprice higher, cloud and neocloud revenue should continue to accelerate which will help address financing fears; I think we may be near peak external financing for this buildout. Noteworthy that using data from 3Fourteen Research, B200 clusters will generate a 37% IRR *if* their rental price declines 40% per year. Prices are still going up, but that IRR math is too ridiculous to print. 37% IRRs available at scale should get funded.
Re: this weekends controversy about MOUs, Anthropic’s $413 billion of real contractual commitments sounds scary. Reality is that it works out to roughly $31 billion of annual cloud spend, which is easily internally financed given their reported ARR, and $161 billion of spend at Broadcom which will be financed by Broadcom and private credit.
Continue to believe fragmentation at the model layer is the best outcome for ordinary Americans and humans everywhere. As I have said before, do not trust any 5-20 individuals to make the best possible decisions about the direction of this technology. I want as many AIs as possible to maximize the odds that they encompass the diversity of human values across the world and richness of human variation. And I want an AI that shares my own personal values. Safety, freedom and the maximization of human agency through democratization, distribution and diffusion vs. centralization. History has spoken on the dangers of the latter path.
Finally, from my perspective anything that slows this buildout down is net positive over the long-term as the biggest risk and worst outcome is an *actual* overbuild. We are structurally short watts, wafers and increasingly capital. That is all good. God forbid we were still in ZIRP, TSM ramped capex to 3x their current plan and we weren’t short turbine blades: there would almost certainly be an overbuild and a bubble. That would be terrible. Slower and smoother for longer is better both for investors and for the world. A terrible cyber event is the most plausible near term bear case IMHO, but AI cyberdefense ramping quickly and I was happy to hear Sholto say that cyber probably becomes defense dominant in the near future.
Longer, threaded version follows:

Warren Pies retweeted

Rising rates and a collapse VC funding could threaten 25% of frontier AI labs' recurring revenue.
That could then trigger a sell off in the broader AI trade.
@WarrenPies unpacks the bear case.

The AI trade is accelerating on record earnings, massive compute demand, and high rental rates for chips.
I sat down with @WarrenPies to discuss the under-the-radar indicators he's tracking in the market right now, his favorite sectors and opportunities for the year ahead, and his latest views on the macro setup.
This conversation will make you think critically about the AI trade.
TIMESTAMPS:
0:00 - Overweight equities
3:30 - Tech-heavy market and AI leadership
5:29 - Macro shocks
11:05 - Low correlations and pair trades
13:37 - Semis and broadening trade
17:35 - GPU availability and rental rates
21:22 - Compute indicators flashing bullish
25:08 - Frontier lab ARR
30:08 - Hyperscalers leadership
32:34 - AI CapEx and the Fed
36:38 - What ends the bull run?
40:32 - Favorite sectors
41:46 - @3F_Research
So, let's say combined lab ARR is actually $126B vs $146B...
The annualized growth rate for 2026 is 577% instead of 724%.
I get the danger of relying on non-GAAP metrics, but IF THIS IS ACCURATE, it is not "popping anything."
More hawkish than I would have guessed his dot to be...Seems like the early-27 data will dictate whether this is a two-hike adjustment or a full-fledged cycle.
Given residual seasonality, base case has to be hot early-27 data.

Waller: “I anticipate additional hikes to support a timelier return of inflation to our 2% goal. But there is some flexibility about when those hikes will occur. The hikes do not need to come at consecutive meetings, but they should be in place in an acceptable period of time.”
wsj.com/livecoverage/stock-m…

Warren Pies retweeted

let's fucking go
IMO, the most interesting macro development post-Fed hike has been the (bear) steepening yield curve (from 26 to 53 bps - since 9/17).
In a true hike cycle, YC steepening is anomalous.
IMO, this is the market pricing in:
1) A two-hike "mini-cycle" AND
2) A higher neutral rate.


Is AI impervious to higher rates?
VC funding is one channel that monpol could impact datacenter construction.
Last hike cycle, VC funding fell by 66%
Startups are disproportionate users of AI (i.e. clients of Anth/OAI). In a similar scenario, ~25% of lab ARR could be at risk.

Not our base case, but, it is worth considering how rate hikes could impact the AI buildout (consensus assumes AI won't crack)...
xitter.cf/bencasselman/status/21…

The A.I. investment boom is contributing to inflation. It also appears nearly immune to high interest rates. That’s a challenging combination for the Fed — with potentially serious implications for the rest of the economy.
With @colbyLsmith:
nytimes.com/2026/10/05/busin…

Warren Pies retweeted

Interesting… Curious how much of this is just AI being an excuse for layoffs/consolidation? Would also be curious to see how this pairs with construction/electrician job creation for data centers
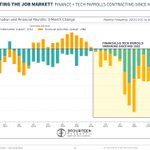
It is becoming obvious that AI is impacting the labor market.
Going back to mid-2025:
-Finance + Tech industries -246k jobs.
-All other industries +812k jobs.
This dynamic will most likely intensify next year and expand into other industries.

First Williams and now Jefferson urging patience for another rate hike.
Predictably, longer-term yields (and SOFR implied rates) fall.
All it takes is some dovish Fed speak to "control the long end."

Warren Pies retweeted

For all the angst about lab ARR (“where is ANT now?!”), remember that revenue growth is still constrained by how much compute the labs can bring online.
I see two races being run in real time. A race at the frontier and a RACE TO SERVE. The latter matters more short term for the AI trade, imho, bc demand for intelligence keeps outrunning supply.
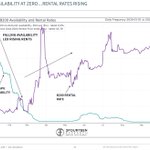
AWS is raising reserved GPU prices for a 4th straight quarter (H200s +75% YTD), and compute availability is near the lows. H/t @WarrenPies, who does some of the best work around this. Hard to see much slack in the system.
Yields are clouding the picture today, and folks are understandably cautious. But zoom out, and the key investment question remains how to get the most upside to Jensen’s right tail scenario (longer/bigger build, tighter compute). If 2027-28 looks as different from today as today does from 2023, there’s an immense opportunity ahead.
In that scenario, a levered balance sheet can be an asset, even if the current rate path suggests otherwise. Tighter compute can mean stronger cash flows and faster deleveraging. And if AI disinflation eventually lowers the cost of capital, you have yourself quite the parlay…
Jensen seems to especially like this trade :). Sized right, a small position can offer option-like upside. Good luck out there.
Warren Pies retweeted

Excellent discussion between @WarrenPies and @FrankCNBC on @CNBCClosingBell.
Warren lays out the bullish thesis, thinks tech will lead, pushes back against the narrow breadth argument, and thinks the Fed isn't going to hike nearly as much as expected.
We are similar, hope he is right ;)
Last Friday, I joined @FrankCNBC on @CNBCClosingBell to discuss our bond upgrade (from underweight to benchmark) and how that flows into equities.
Link below:
cnbc.com/video/2026/09/25/fe…
