

Focus on quality US compounders and durable businesses. In-depth analysis, clear thinking, long-term perspective. No hype — just better investment decision
New York, USA
Joined September 2010
- Tweets203
- Following36
- Followers384
- Likes593





🚨 $NBIS: FOMO AT $276. OPPORTUNITY AT $123?
While everyone was screaming BUY at $276, the DCA Optimizer was flashing STRONG TRIM.
Now look where we are:
📉 From $276 to $123: DOWN 55.4%
🔥 The DCA Optimizer has now flipped to:
STRONG BUY ZONE
3X DCA SIGNAL
Price: Around $123
The lesson is simple:
FOMO makes you chase the top. Patience gives you the opportunity to buy when fear takes over.
The best investors don't blindly follow the crowd. They follow their strategy, manage risk, and wait for better opportunities.
Don't chase hype. Buy with discipline. 🚀

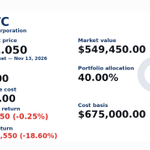
$INTC Position Update 🔥
I added another 3,000 shares of $INTC yesterday.
My total position now stands at 9,000 shares.
CEO Lip-Bu Tan recently invested $9.7 million of his own capital to purchase company stock at a price of approximately $64.73 per share. Yesterday, he also spoke publicly about the company’s multi-year transformation plan, the demand for artificial intelligence (AI), and his personal commitment—a "mission"—to get the company back on track.
Furthermore, Intel has just announced a significant partnership with RadixArk, aimed at optimizing the open-source AI inference framework (SGLang) directly on Intel’s platform. This serves as further evidence that they are building real momentum across their AI software and hardware stack.
I remain bullish on $INTC for the long term. While there may be some market noise in the short term, given the CEO’s significant personal financial commitment and the company’s ongoing AI partnerships, I have chosen to hold my position and add more shares.
If you also hold $INTC, drop a 🔥 in the comments and follow me!
I will continue to share the latest updates.
The above does not constitute investment advice; it simply reflects my own firm conviction. 🚀
#INTC #AISTOCKS #Semiconductors

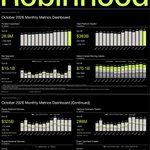
🚨 $HOOD JUST DROPPED ITS OCTOBER 2026 METRICS!
Some impressive numbers, but one area is showing weakness. 👀
📈 Key Highlights:
Funded Customers: 28.9M (+1.8M YoY)
Total Platform Assets: $383B (+12% YoY)
Net Deposits: $15.1B (46% annualized growth rate)
Equity Trading Volume: $325B (+2% YoY)
Options Contracts: 289M (+8% YoY)
Event Contracts: 5.9B (+136% YoY)
⚠️ The Weak Spot:
Crypto Trading Volume: $17B (-48% YoY)
🔥 MY TAKEAWAY:
Robinhood continues to expand its customer base and attract significant new capital.
Event contracts are growing rapidly, while options and equity trading remain resilient.
Crypto trading is clearly the weak spot this month, but the broader platform growth remains impressive.
$HOOD is becoming much more than just a stock trading app. 🚀

🚨 $NBIS: IS ASSET-LIGHT REVENUE REALLY RECURRING?
The answer is BOTH. And investors need to understand the difference. 🧐
Nebius’ asset-light model allows partners to fund infrastructure while Nebius provides the AI technology, expertise, and cloud platform.
This creates two potential revenue streams:
1️⃣ Initial Deployment: Non-Recurring Revenue
Nebius helps partners secure capacity, equipment, supply chains, and infrastructure design.
This is where the $325M in non-recurring revenue recognized in Q3 came from.
Each transaction is tied to an initial deployment, so it doesn't automatically repeat every quarter.
2️⃣ Operational Phase: Potentially Recurring Revenue
Once the infrastructure becomes operational, Nebius can monetize that capacity through its AI cloud platform.
As customers use the infrastructure, it can generate ongoing revenue over time.
🔥 Here's what the market may be overlooking:
Every new asset-light partnership could create another initial deployment revenue opportunity, while previously deployed infrastructure could continue generating operating revenue.
In other words, individual deployment payments may be non-recurring, but signing multiple partnerships could make this a more regular source of revenue.
What about 2027?
Management's comment about a small contribution to available capacity refers to operational capacity, not necessarily revenue from new partnership deployments.
Importantly, potential revenue from additional asset-light partnerships was not included in the initial $12–13B 2027 revenue guidance, according to the information discussed.
My takeaway: Asset-light could become a powerful growth engine for $NBIS. It allows Nebius to monetize its technology and expertise without funding every dollar of infrastructure itself.
The opportunity is compelling, but profitability, deal economics, and repeatability still need to be proven.
Don't confuse non-recurring transaction revenue with a business model that can generate new transactions repeatedly. 🚀

🚨 $INTC: DOWN 38%, YET UPGRADED TO STRONG BUY!
While many investors are focused on Intel's massive selloff, a bullish signal is emerging.
An analyst has upgraded Intel to STRONG BUY following a 38% decline in its share price.
And there's another potential catalyst:
🔥 Intel's Crescent Island AI GPU is reportedly attracting up to $2 BILLION in demand.
If confirmed, this could become Intel's best-selling GPU product ever.
Think about the combination:
A 38% selloff creating a potentially attractive entry point.
A Strong Buy upgrade despite the market weakness.
Potential $2B demand for Crescent Island.
Growing opportunities in AI inference and data center infrastructure.
The market may still be focused on Intel's past struggles, but the company's next growth chapter could look very different.
I'm increasingly bullish on $INTC's long-term potential. The turnaround could be bigger than many investors expect. 🚀
Are you watching Intel at these levels?

🔥 $INTC — A NEW ERA OF EXECUTION!
Intel CEO Lip-Bu Tan sat down with Yahoo Finance's Brian Sozzi to discuss the company's transformation and the opportunities ahead.
His priorities are clear:
Rebuild Intel's execution culture.
Put engineering excellence back at the center.
Make customers the top priority.
Simplify decision-making and strengthen accountability.
Position Intel to capitalize on the growing AI and semiconductor markets.
Intel's turnaround is about more than just new chips.
It's about rebuilding the culture, restoring customer trust, and proving that the company can execute.
I'm bullish on $INTC's long-term potential and believe the company has significant room to grow.
If you believe in Intel's comeback, follow me for more $INTC updates, news, and insights! 🚀

🤔 Why is $IREN trading below $20 again after delivering such an impressive earnings report?
Am I missing something here?
AI Cloud revenue surged to $200M, up 182% QoQ. The company also exited September with $1B in operating ARR and a massive $20.3B revenue backlog.
But the market seems focused on:
The delay in reaching $4B+ ARR
Massive CapEx and financing requirements
Execution risks surrounding Microsoft deployments
Persistent concerns about profitability and dilution
Are investors simply looking past the near-term growth and focusing too heavily on execution risks?
Or is there something fundamentally bearish that I'm overlooking?
I'd love to hear other $IREN investors' perspectives. 👀

🔥 $KEEL IS NOT RUSHING TO SIGN JUST ANY DEAL.
CEO Ben Gagnon made it clear:
“We are not setting a hard deadline for ourselves just to get a lease signed.”
KEEL is advancing three major projects in parallel, and management isn't willing to sacrifice deal quality just to meet an arbitrary deadline.
The strategy is simple:
Don't rush into the first offer.
Don't compromise on long-term deal economics.
Focus on securing the best possible lease agreements.
Yes, getting leases signed is important. But signing the RIGHT deals matters even more.
For a data center company building long-term infrastructure, patience could pay off.
The goal isn't to sign leases quickly. It's to sign leases that create lasting value for shareholders. 🚀
🤯 DID YOU KNOW NVIDIA HAS A BIGGER REPORTED STAKE IN $NBIS THAN BLACKROCK?
👀 NVIDIA reported beneficial ownership of 22.26M shares of Nebius, compared with BlackRock's 11.53M shares in its Q2 2026 filing.
That's nearly 2X BlackRock's reported position!
🟢 NVIDIA: 22.26M beneficially owned shares
🏦 BlackRock: 11.53M reported shares
But here's an important detail:
Most of NVIDIA's reported stake comes from a pre-funded warrant, not shares already held outright.
Still, NVIDIA isn't just Nebius' chip supplier.
It's also a major strategic investor with significant exposure to Nebius' growth. 🚀

🚨🟩 NOW THIS IS WHAT INSIDER CONVICTION LOOKS LIKE FOR $NBIS!
Nebius Director Grimme reportedly made 11 purchases in just 11 days.
🟢 Shares purchased: 2,014
🟢 Total value: ~$330,000
🟢 Average purchase price: $164.07
11 transactions in 11 days certainly get investors' attention. 👀
While the purchases may have been pre-planned, the buying activity is still worth watching.
One insider sale can make headlines. But repeated insider buying deserves attention too. 🟢🚀


🚨 H.C. WAINWRIGHT REMAINS BULLISH ON $IREN!
H.C. Wainwright reiterates its BUY rating, maintaining a $56 price target.
The firm sees asymmetric upside potential at current levels ahead of a meaningful revenue inflection in Q1 2027.
The key catalyst? IREN’s rapidly expanding AI Cloud business and its transition toward large-scale revenue generation.
The opportunity could be significant. 🚀


🚨JUST IN: Intel and Altera expand collaboration for Edge & Physical AI.🔥
They’re building a flexible real-time sensor bridge for healthcare, aerospace, defense, and robotics.
While the market focuses on the weak guide…
Intel is quietly expanding into the next wave of AI at the edge.
Fresh catalyst. Under-discussed.$INTC

$CRWV Q3 just crushed estimates.🔥
Revenue $3.66B vs $3.54B expected
EPS -$1.27 vs -$1.55 expected Adj. operating income $379M vs $246M expected
Contracted power is now over 4.6GW
Active power is 1.7GW+, doubled since the start of the year
Backlog jumped to $132.5B, up about 27% QoQ
They raised 2026 guidance too
Revenue $13.0–13.3B (street was at $12.5B)
Capex $37–39B (street was at $36B)
Exiting the year at $20–21B ARR
Overall a beat. Short term sentiment should get a bounce first
🚨 GOLDMAN SACHS INITIATES COVERAGE ON $KEEL WITH A $2 PRICE TARGET!
Goldman Sachs starts coverage with a Neutral rating, acknowledging the massive opportunity in AI data centers.
Here's the key takeaway:
🔥 Demand for data center capacity could exceed available supply.
⚡ Power availability and long equipment lead times create significant barriers to entry.
⚠️ But KEEL still needs signed lease agreements and more visible construction progress to prove its execution.
The opportunity is there. The challenge is turning power capacity and development projects into signed contracts and recurring revenue.
KEEL has already started construction at Moses Lake, targeting its first HPC revenue in 2027.
The next major catalyst? The first major AI data center lease. 👀
If you found this post helpful, hit LIKE and FOLLOW for more updates! 🚀
#KEEL #AI #DataCenters

🚨 J.P. MORGAN CUTS $IREN PRICE TARGET — BUT REMAINS OVERWEIGHT!
Richard Choe lowered his target from $65 to $55, despite keeping revenue and EBITDA estimates largely unchanged.
But here's what matters:
🔥 Contract pricing continues to improve.
🔥 New 5-year deals are reaching ~$22M per IT-MW.
🔥 Customers are prepaying up to 90% of associated GPU CapEx.
🔥 Hyperscaler interest in 90% prepayments for Vera Rubin capacity is emerging.
More customer prepayments = less capital IREN needs to borrow for GPUs.
The market is focused on execution risk. But improving pricing and funding flexibility could be an important part of the bigger picture.
#IREN #AI #Stocks


$RKLB – key chart in space sector right now.
MOAT trendline crystal clear.🚀
Holding 54–58 support after earnings.
Higher lows forming. Bottoming time?? Bounce!
Either bounce or wait and see.


$RKLB 🔥
Position Update!
My total holding is now 5,000 shares.
I’m very bullish on RKLB’s long-term potential. Yesterday’s Q3 earnings showed record $268M revenue (+73% YoY) and a massive backlog surge to $3.57B, including over $515M in new Neutron contracts. The space launch and systems business still has huge runway, and I see $80–$100 as a realistic long-term price target. 🚀
I’m staying confident and focused on the bigger picture.
If you’re also holding or following $RKLB, FOLLOW ME NOW! I’ll keep sharing my latest position updates, insights, and key developments.
The journey is just getting started!
#RKLB #RocketLab #Space #Stocks #Investing

$RKLB 🔥
Position Update!
My total holding is now 5,000 shares.
I’m very bullish on RKLB’s long-term potential. Yesterday’s Q3 earnings showed record $268M revenue (+73% YoY) and a massive backlog surge to $3.57B, including over $515M in new Neutron contracts. The space launch and systems business still has huge runway, and I see $80–$100 as a realistic long-term price target. 🚀
I’m staying confident and focused on the bigger picture.
If you’re also holding or following $RKLB, FOLLOW ME NOW! I’ll keep sharing my latest position updates, insights, and key developments.
The journey is just getting started!
#RKLB #RocketLab #Space #Stocks #Investing
🚨 7 TECH GIANTS ARE INVESTING $26 BILLION IN $ANT!
Some of the biggest names in tech are buying Anthropic shares at its IPO price:
🔥 Google ($GOOGL): $10B
🔥 NVIDIA ($NVDA): $10B
🔥 AMD ($AMD): $2.5B
🔥 Broadcom ($AVGO): $1B
🔥 Micron ($MU): $1B
🔥 Microsoft ($MSFT): $1B
🔥 TSMC ($TSM): $500M
That's $26 BILLION in strategic investments!
The purchases are expected to take place immediately after the IPO closes, subject to conditions.
When the world's biggest technology companies invest billions in the same AI company, the message is hard to ignore.
The AI race is entering another level. 🚀
Follow me for the latest stock market news, market trends, and investment opportunities!

🚨 BREAKING: TEXAS GOVERNOR-ELECT GINA HINOJOSA PLANS TO FREEZE RESIDENTIAL ELECTRICITY RATES.
Her proposal aims to protect households from rising power costs by making data centers and other large energy users pay their fair share of grid expenses.
This could have major implications for Texas' AI infrastructure boom.
Energy costs and data center expansion are becoming increasingly connected. ⚡
$IREN $KEEL $CIFR $WULF
